Wefox MGA
High-level objective:
- Use the wefox Italy platform to generate multiple streams of income from the Italian market with focus on affinity and motor.
Tasks:
- Corinne to review for the MoU
- Sign MoU
- Get data from them Motor MOD
- Try to get data on the live WindTre affinity program
- Validate LR on Dealerships MOD/Ancillaries
- Validate LR and volume on Affinity
- Come up with our LR view of market MTPL
- Reinsurance with Hannover RE
- Meetings with Milliman and WTW
- Send spec for MTPL pricing to Milliman & WTW
- Send Hannover MOD reinsurance submission
- Sort out the licensing
- Get reinsurance for the motor
- Perform Triage (waiting for docs)
- Benchmark other lines besides motor
- Set out our parameters
- Talk to HR this Wednesday
- Get transparency over sales process
- Sforni to send HRe expected margin
- Arch to agree internally on acceptable structure
- WeFox to send MTPL information to Arch (portfolio information from targeted brokers)
- Arch send proposed structure to WeFox
- Arch prepare reinsurance pack
- Sforni send RI pack to Hannover
- Hannover provide quote
- Axeria prepare submission for ACPR
- WeFox / Italian law firm prep local requirements
- Arch hire external actuaries to design MTPL tariff
- Discuss and agree MTPL tariff together, Arch does analytical work, propose and discuss final tariff with WeFox
- Arch to send termsheet to WeFox
- Axeria perform Due diligence
- Axeria send TOBA to WeFox
- Operations begin, target live date 1 July. If necessary, start with MOD only.
Minutes from calls/meetings:
24.05.2024
Call with Matteo to understand the current situation.
07.05.2024 meeting with WTW / Wefox
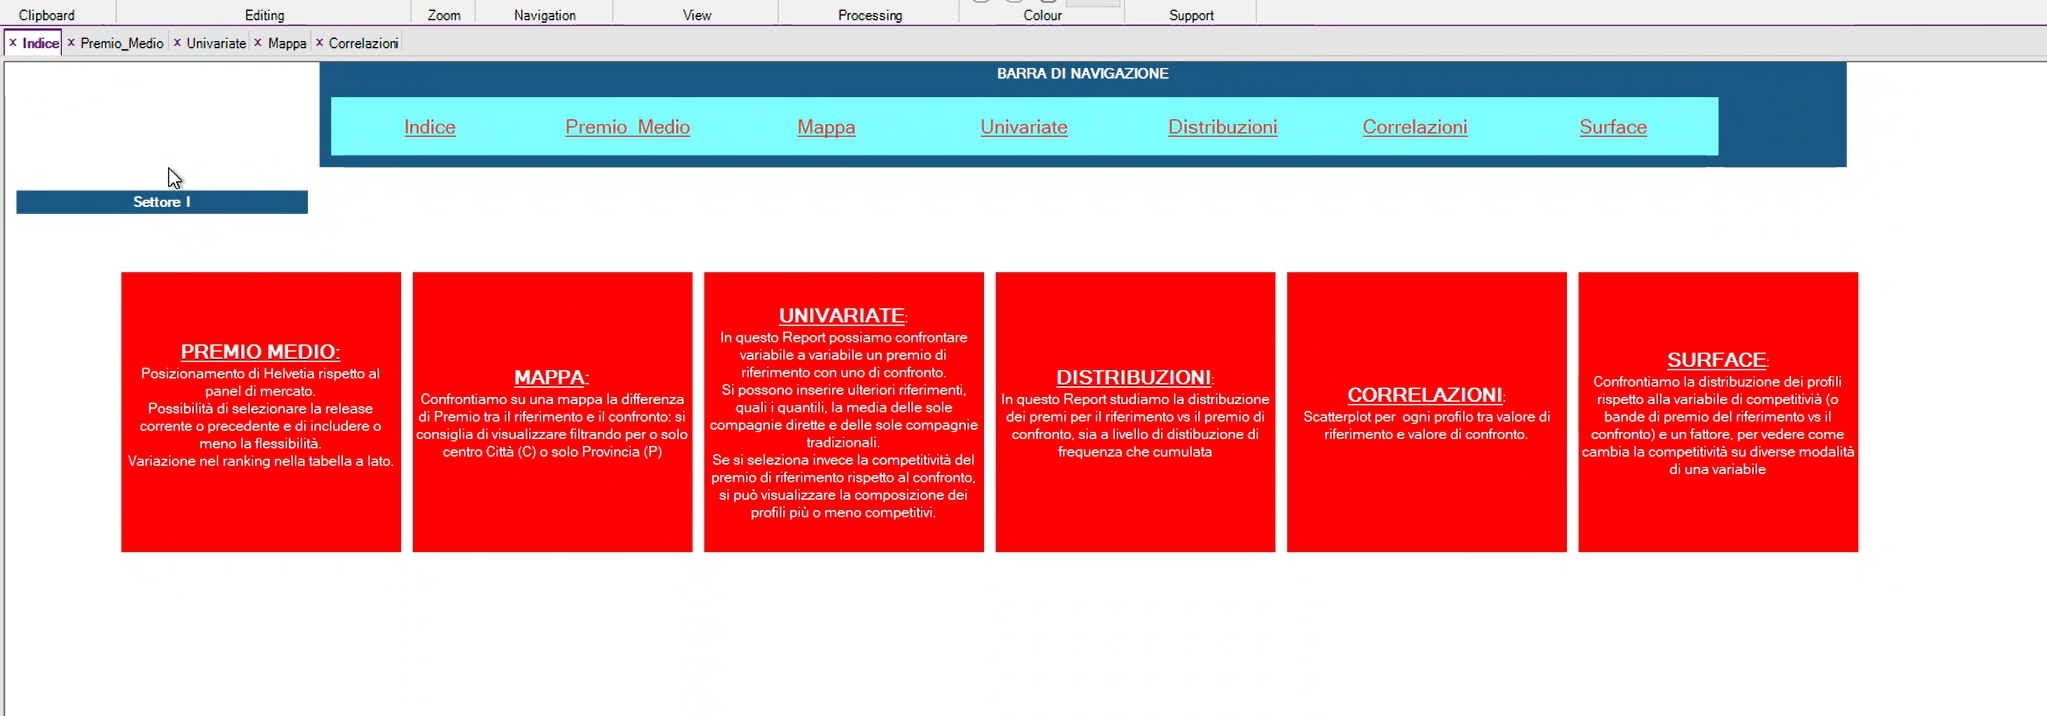
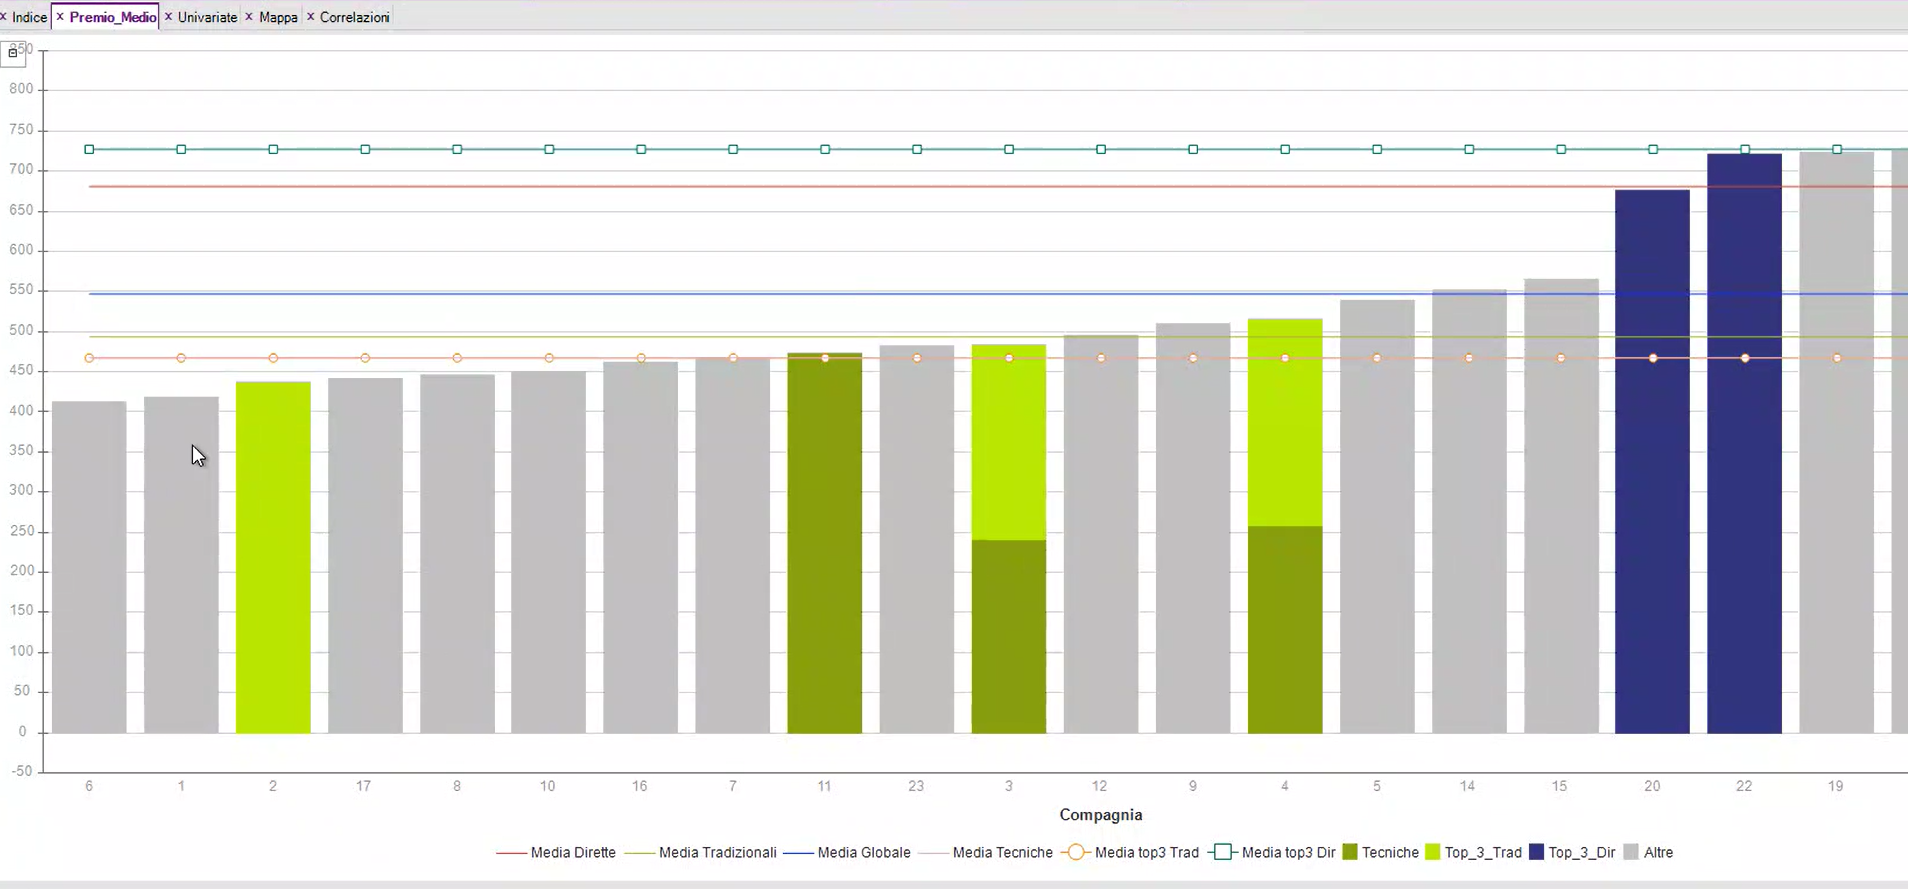
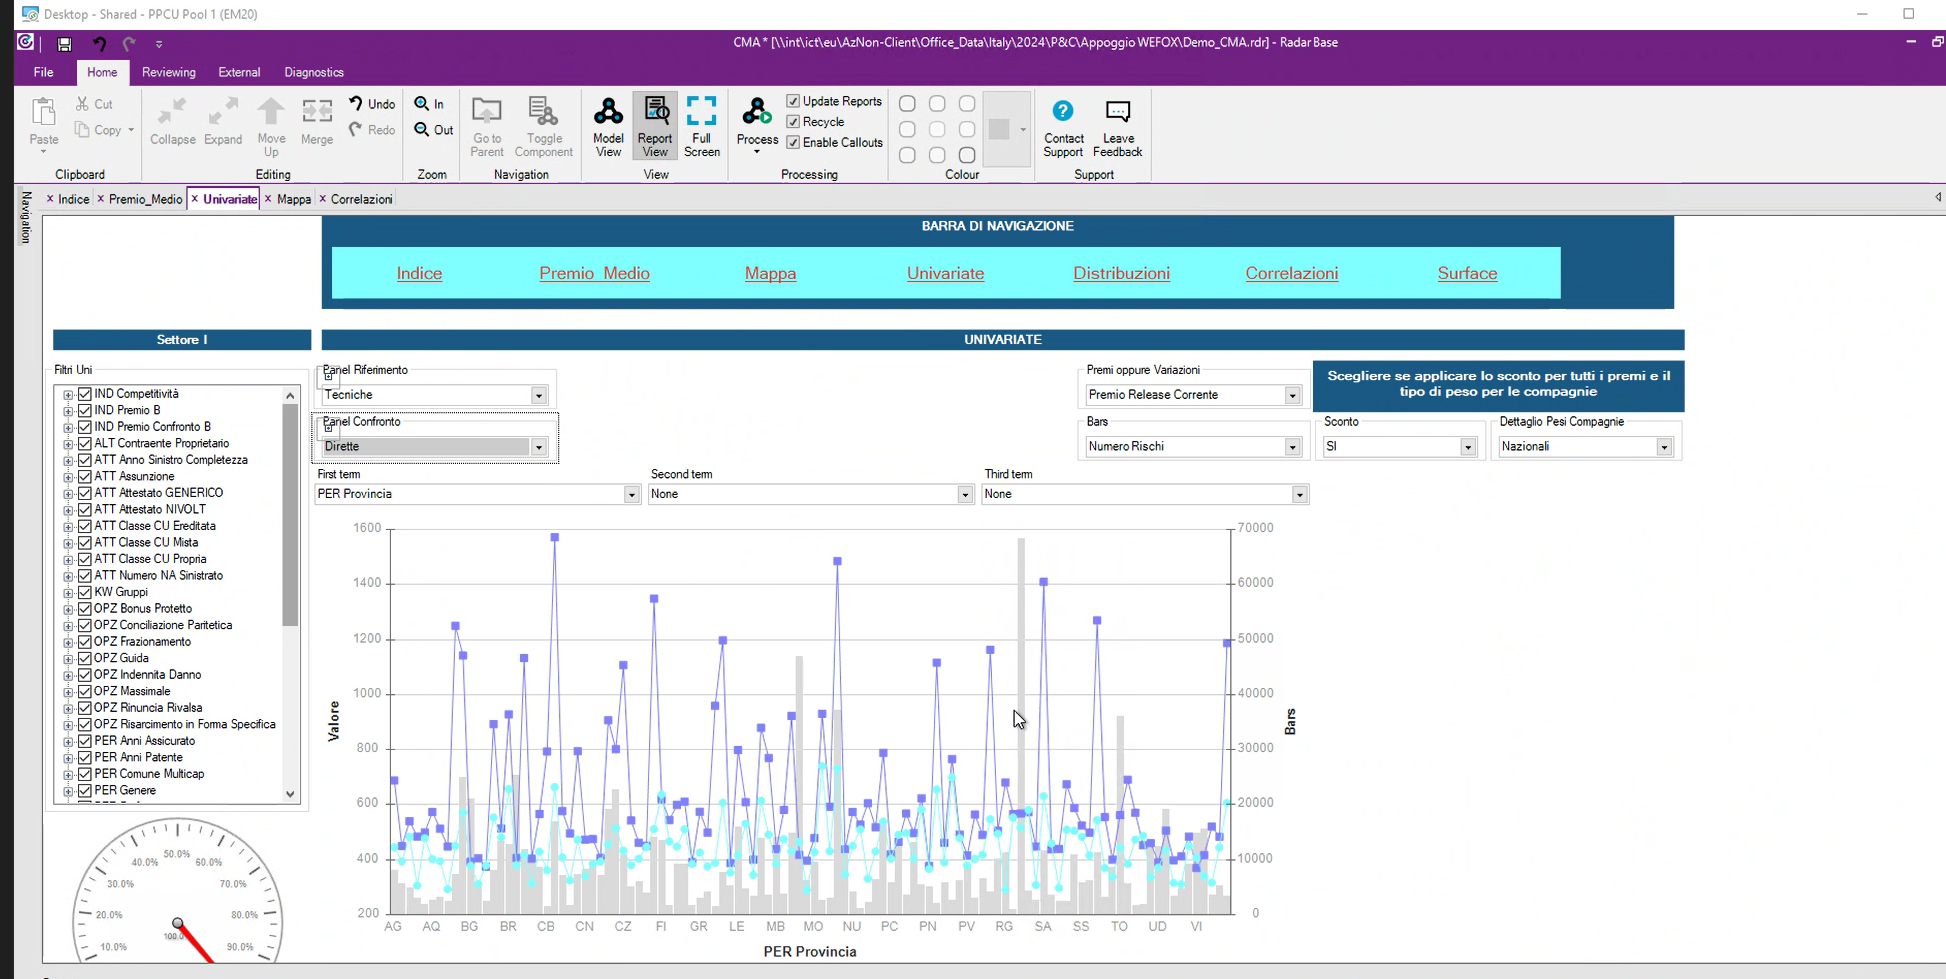
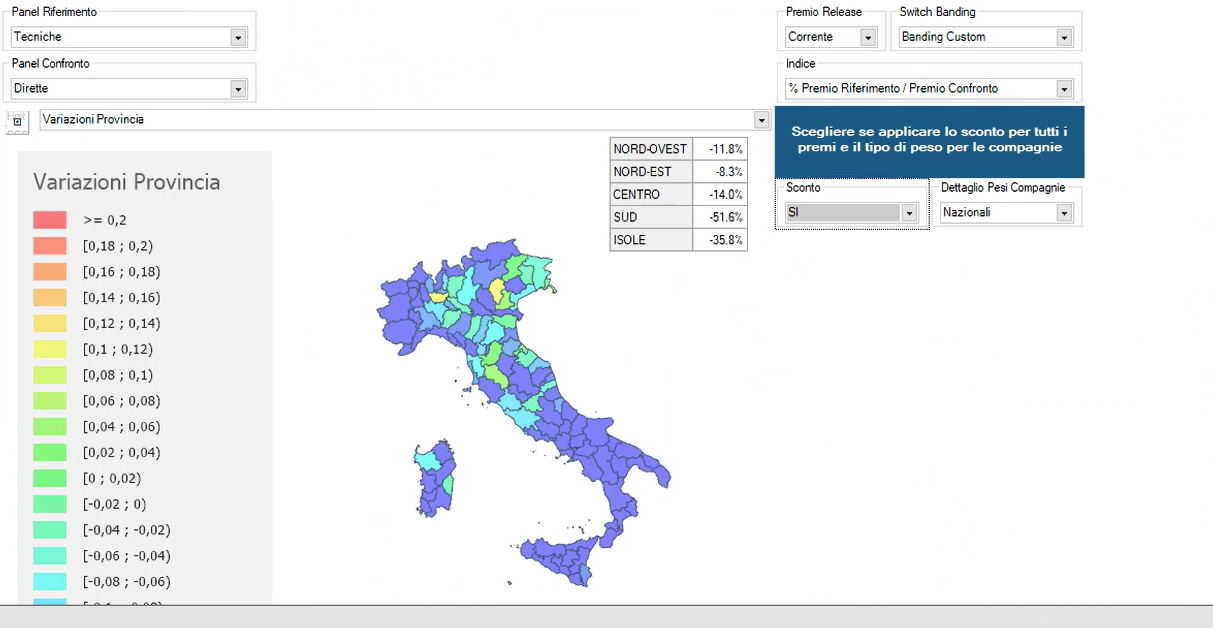
sources : webcrawling directly from the website of the company.
1M record sample, new business in the new market
44 Million vehicles --> new business --> sample 1M rows.
5k --> low sophisticated tarifs
10k --> high sophisticated prices
--> algorithm to calculate discounts
--> standard 1000 quotes per moth
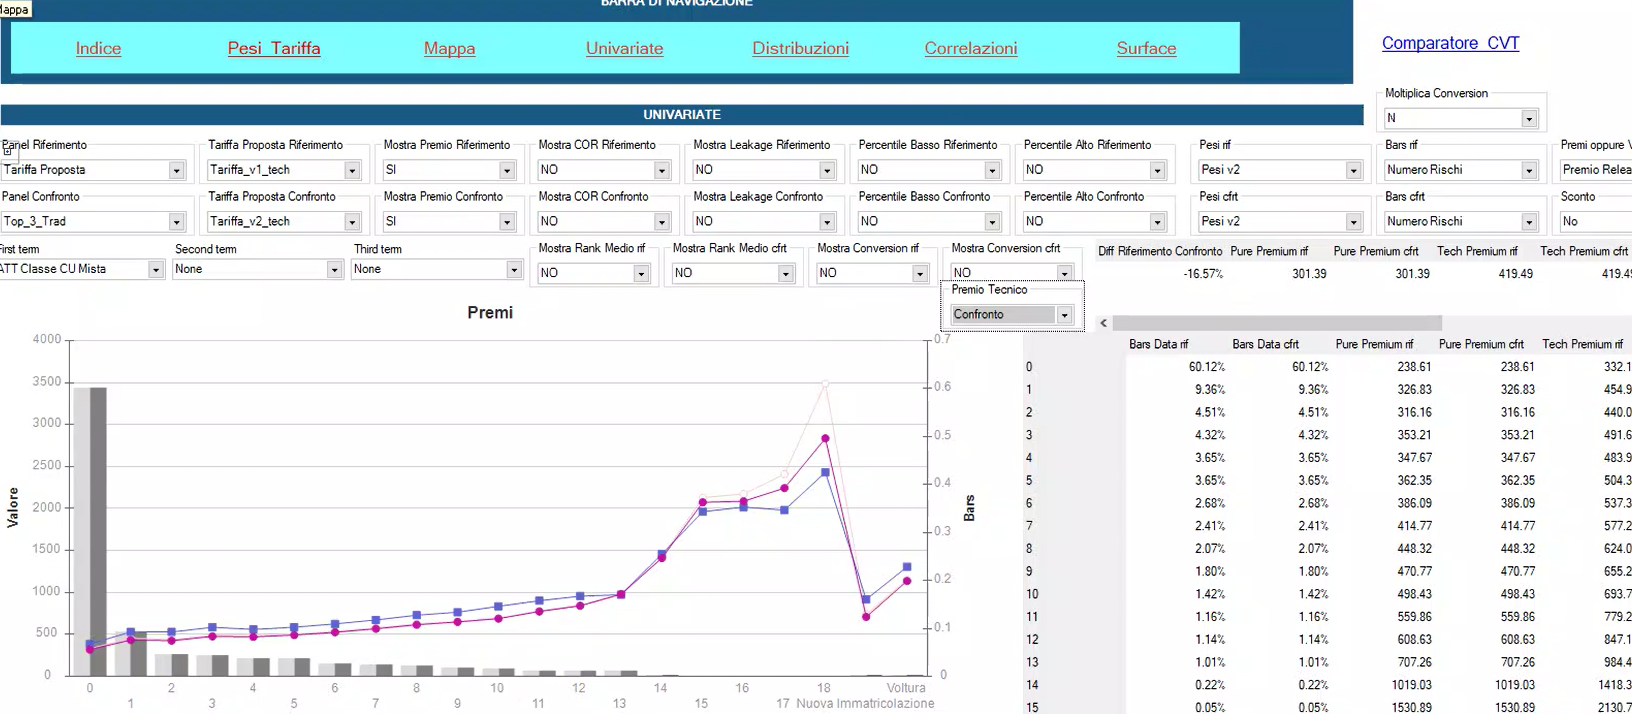
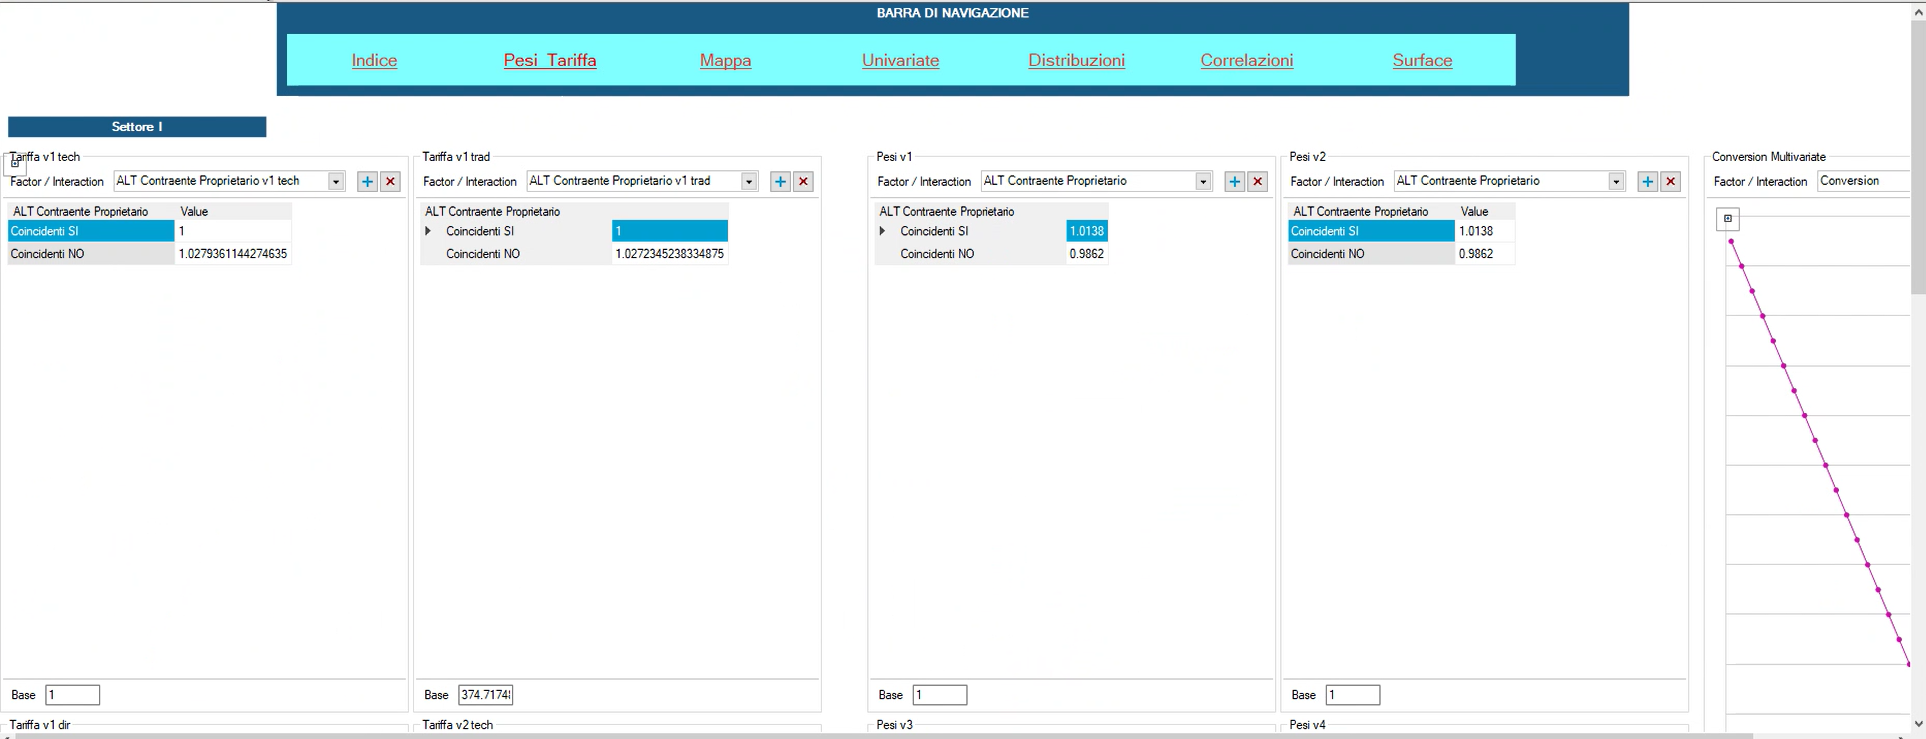
06.05.2024 Wefox/ Miliman
--> need for significant data, market knowledge, competitor analysis, comparison to competitors. Software.
--> radar Emblem Miliman
--> Data to be used.
--> Vehicle data : mainly private car private car.
--> MOD maybe motorbike
--> Fake tariff approach for non target segments.
--> Distribution : traditional intermediaries, higher acquisition costs- > better performing portfolio.
--> ANIA data source, how much is the commission. Base premium - loadings of Allianz.
--> Pooling data for frequency estimated by GLM. smoothing cluster in terms of frequency.
--> Allianz tarif very technical
--> 6 are using postal codes,.
--> Vehicle type : external data base provide a lot of information quotes.--> value of the car MOD side.
Risk tariff
Minimal can propose a tariff proposed using market data, claims frequency and claims severity or pure premium approach.
Ania + non disclosed benchmark.
Commercial tariff: monitoring day by day, 100k policies ( Unipol and generali )
daily quoting prices, scrapping for world market, aggregations, traditional insurer ( outside aggregation)
Miliman clients : aggregated level information from competitors.
Data from brokers agents. information from.
Quotes from motor own damage, competitive analysis for telematics and traditional.
80% of the market competitors. Generali, Axa.
20% irrelevant prices.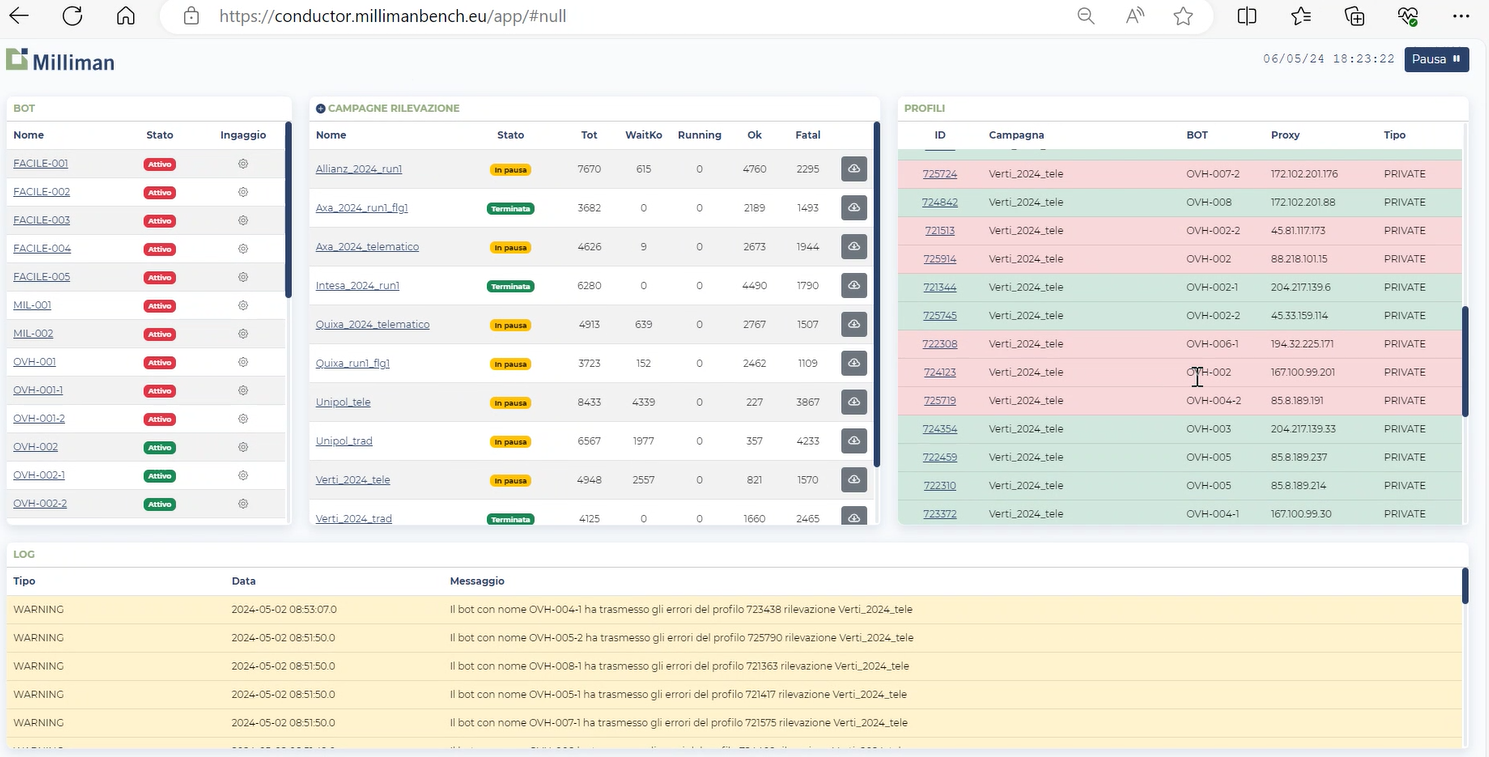
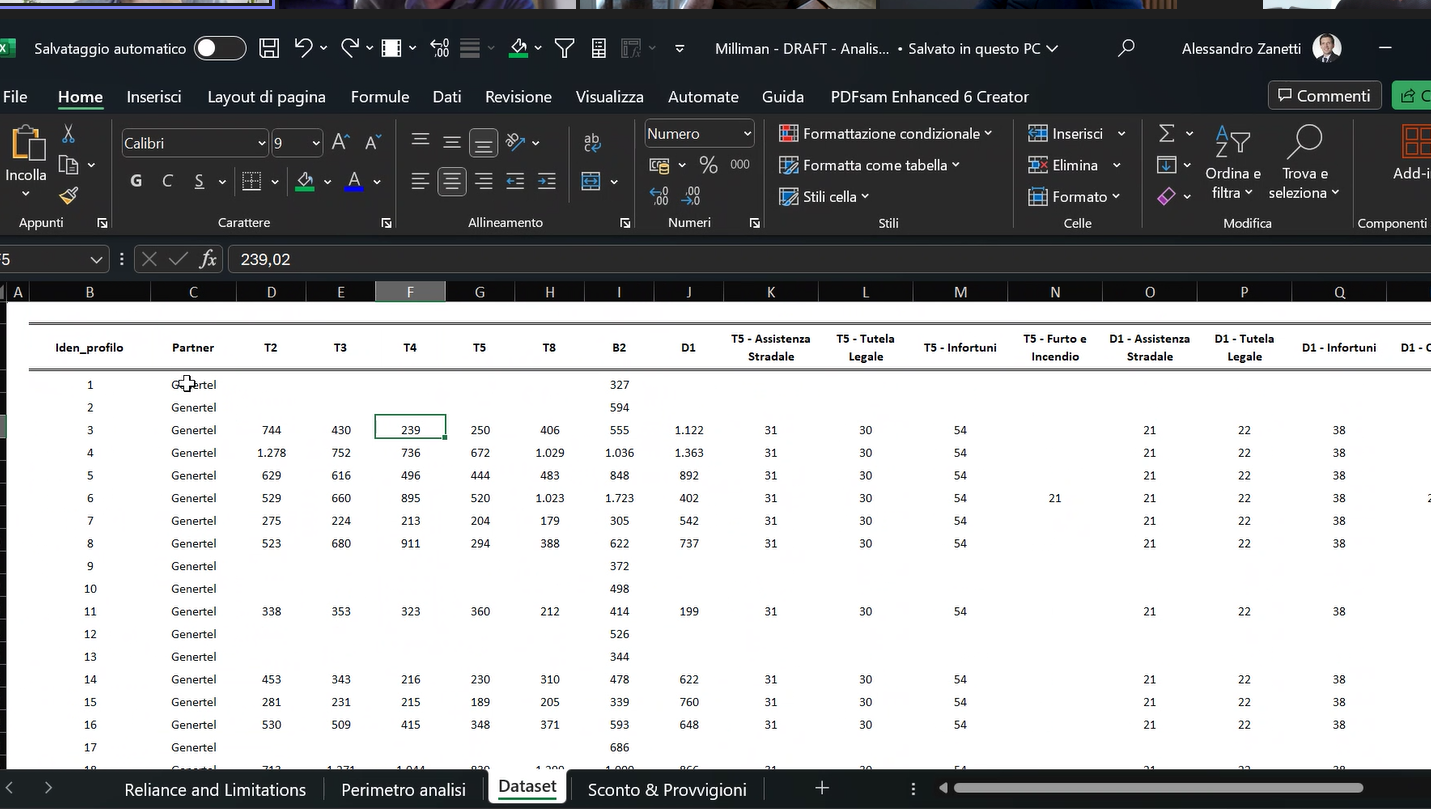
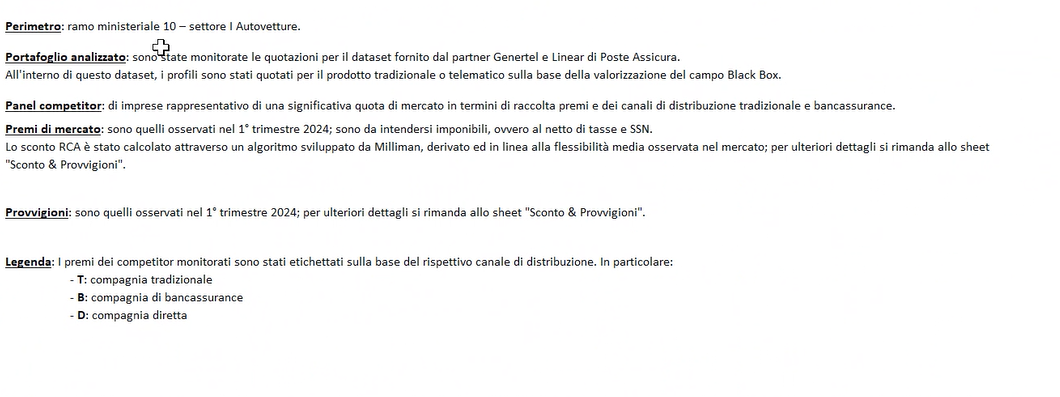
Data set :
Best price, lowest price.
line by line.
13 years, they said market knowledge.
Scrapping directly the company website.
Prices including discount,
Target start date June first. + 12 weeks
Market knowledge:
Some companies are making well and some are making money. some others loosing.
Increasing average premium, retention is decreasing.
All groups have traditional and direct companies, hard market. --> technical
Expenses: commission side.
Traditional channel is predominant.
15 to 20% directly.
10 April, 2024, 16:00
Meeting with Akur8:
They don’t have data, but work with a number of partners.
They will send us a list of partners (anonymised) and the level of data they offer.
Post-call discussion with Massimo, Emmanuele:
Most of the market uses GLM as their main risk model, with GBM / other machine learning models used in demand modelling, lifetime modelling, etc.
To find an edge you need to bring in new factors / sources of information, rather than trying to rate differently with the same factors.
Need to start writing and participate in data collection with ANIA to get information from their DB.
Data would be of limited use to us - limited to querying 3 factors for a given KPI (e.g. frequency).
Regulator would issue warning if an insurance company scrapes the DB. But not an issue for a consultancy.
08.04.2024
Meeting with WTW:
Market view of TW: Margin opportunity, market is hardening after 10 years of soft market, profitable niches ( good technology is key here ), 10m--15m GWP is a feasible,
Strategy:
--> MGA is a market trend, Entering a market requires investments.
--> Investment in technology
Being able to change rates on a daily basis
Creating a trading entity.
UW strategy : Motor MGA instead of only motor, most relevant part is how much you can sell MOD to the right people. MTPL is compulsory and there are maximum premiums.
Technical tarif : WTW :
1m sample of risk profiles, analysing Ania data, and also competitors data.
No claims data.!
Ania --> Fake risk profiles --> 2 sources --> web crawling to get the rates.
25 players --> 50% web crawling , in aggregators age and plate --> fake price.
Traditional players are not making this controls.
Expenses : Ania , infoBila provides loadings. Expense ratio for each,
Output :
Level of service1 :1M profiles, with market rates ( average, top 5, last 5), technical price.
Level of service2: full detail of prices with each competitors price.
Distributions by ages, municipalities, 30. 35 risk factors
Selecting a number of insurers that are more technical.
13 February, 2024, 15:30
AÓF call with Bruno and Stefano.
They’ve already set up a meeting with Hannover, but would like to approach reinsurers together.
Queried whether we need reinsurance in place to get license. They were trying to push to get everything included.
Pricing: We can go one of two ways on MTPL - WeFox design a tariff, or we design one together. I said we are open to both, but if neither of us have data, we need a reliable way to benchmark, and pricing must be iterative.
Sforni suggested an actuarial consultancy firm in Rome that will be able to verify a proposed tariff for us.
WeFox getting anxious; we should go and see them in Milano asap. Stefano wants to know our target commission, etc.
6 February, 2024, 14:55
Call with Bruno. He spoke to Matteo and he expressed our concerns with Massimo leading this project. Matteo made it clear that Massimo is only on the sales/distribution and responsible for the products is Mauro and under him Emanuele, the actuary. Mauro is Head of Products.
Call 19.02.2024
Scope is motor MOD + MTPL plus Ancillary + WIND Tre, the didn’t provide data cause the current volume is very little.
Axeria is expected to get 100% on Motor, 50% on WindTre
WindTre porfolio is composed of Home , Affinity ( White goods + electronics)
Arch discussion ;
Wefox wants to put both both carriers on same pricing.
who are the other carriers / previous carriers,
- MOD/ancillaries portfolio versus MTPL portfolio -> 2:1 volume ratio
- Changes to their pricing to become more risk sensitive. No loss making segments. More expensive on the cat-prone areas, prices have gone up significantly from other players on cat covers. 50-50 random selection.
- Slide on their over-rider
- Business must make sense even if we cannot find reinsurance for it
- Affinity is too small, will be judged on stand-alone basis after we understand the products.
MTPL and ancillaries.
1 portfolio dealerships, fee + PC overall
Dealerships : MOD+ PA + Legal assistance + minor coverages
MTPL: MOD + PA legal assistance
9 % on MOD
Reinsurance --> Convince Hannover to improve the LR
28.02.2024
Portfolio consists of 500 cars dealers, some car dealers produce only 1 policy per month.
they approach directly the owner of the car dealer, on a specific approach with commissions and profit shares agreement.
Majority : range 45% -48% premium before VAT, to include the insurance offer.
Complete embedded in the financial offer (75%), 25% outside of the financial program.
- Financially embedded : less risk of fraud
- sold separately: increased financial risk
- Dealerships - partnerships with banks. Direct competition with bancassurance.
- Best commission on the financial side and best commission on the insurance offer.
- 50% operate through a captive , 50% operate through a carrier ( Wefox)
Business is driven by the commission and pricing :
- Sophistication: car dealerships have a knowledge of the market. they want an offer not sophisticated, 10 quotations with the captive and wefox, and they compare the level of commissions and prices.
- Proposal a light customisation of the product to compare many offers. to get a simple quote.
- 48% vs. market 45%.
- Exeple Multibrand dealerships : Auto torino has 18 brands, they chose to sell Wefox policies on the used car perimeters on every brand except Toyota.
- 52% of the portefolio is new cars ( stellantis and ford). Insurance carriers with sophistication are loosing care dealers to Wefox
- Nobis is seen as a standard reference of a product.
Pricing:
- Age of the policy holder ( not of the driver )
Car dealerships are reluctant to accept more sophistication.
Reinsurance Meeting:
Positive reaction of Hannover Re, they know that Wefox is more of a broker than an insurer.
They also see it as positive that Axeria / Arch provides Underwritting and Pricing capabilities.
Framework we are going to offer
- 2 to 1 ratio MTPL
- Financing only
- 1 to 5 years,
- only variable we are going to use is geography
- 50% of the affinity
- MTPL minimum fee + PC
- MOD slide on the MOD.
Meeting with Yannis on Wefoy MTPL:
- MTPL pricing.
- Online market : very sophisticated.
- Off line market : not very sophisticated.
- Not an expert in Italian Market.
Meeting 13.03.2024 Bruno Sforni
- Wefox wants to limit UW to 7 instead of 5
- 66% deales13 March, 2024, 16:0313 March, 2024, 16:03
- 33 Brokers and dealers
- They agree on this mix 1 to 18months, and they could re-evaluate after this period
- we need the split the acquisition cost bewteen
- dealers
- wefox
- Ganularity of the data brokers ( basic information than the broker is already collecting)
- Location
- licence plate
- age of policy holder
reinsurance
- sliding scale, whats the margin in MTPL.
- Sforni has both structures for
- MOD GWP Fixed basis
- MTPL GWP = 10m€ fixed commission 20.5% , sliding scale no PC
- TimeFrame
- @Juan Rerun analysis
- Vehicles up to 5 years ( fixed price )
- Second Price for older than 5 years
- Loadings calculation
- As if on the LRs, ( charge properly for each province --> homogeneus)
- Tarif
- Back to Hannover --> recreated the target porftolio --> LR and results.
- End of April Arch
- Package 2 - 3 weeks
- Reinsurers 2 - 3 weeks
- End of April
- May June