DGI
Intro Call M Beckers / SSE
Domestic & General (blanc / brun)
- Decision to be made by DGI for second round (end of week 11th of June)
- VEL working on the proposal
Insurer in the UK et Germany
From Insurer to MGA for 2 reasons:
- Regulation (should be class 13 with very high cost of capital ; but PRA has accepted specific model)
- Efficiency in Europe : They prefer one carrier in Europe rather than opening insurance companies all around Europe or having multiple carriers (Wakam one of the carriers)
In the UK they want to remain insurer.
Loss ratio: 30%
Combined ratio: 85%
1Mds de prime UK et Europe
200M€ en Europe
D&G = Insurer & Reinsurer
16.07.2024
Distribution model : Bosch, Siemens, Retailers,
Board meeting 17 may. Feedback in principle from us before.
Next step: intro call on 30th of April
Full ppt presentation available
Domestic and General
European Insurer DGI (EU) -> German licensed
Writing business in Europe, through branch of UK DGI.
Forced to create a European subsidiary. Transferred the business.
Branches or FOS in others.
Spain/Portugal (Iberia), Germany, smaller in other markets.
Retail business (major retailers), also OEM. (>50% retail).
Not about risk transfer. Not about capital release.
Reinsurance between UK and EU.
business model -> forced to create this insurer, a lot of admin
Scaling more efficiently, through an MGA structure. Serve our clients better.
Outside perception. Investor's view.
Strategic imperative.
Alignment of interest, uw/product development, claims handling, working with insurer/reinsurer. Size/countries.
Rating Criteria:
- Pricing backet (margins)
- Quality of the counter-party (capital element, solvency)
- Experience (ability to help across Europe, expertise)
15/5/2024 Dealine for RFP
09.07.2024 Meeting with DGI
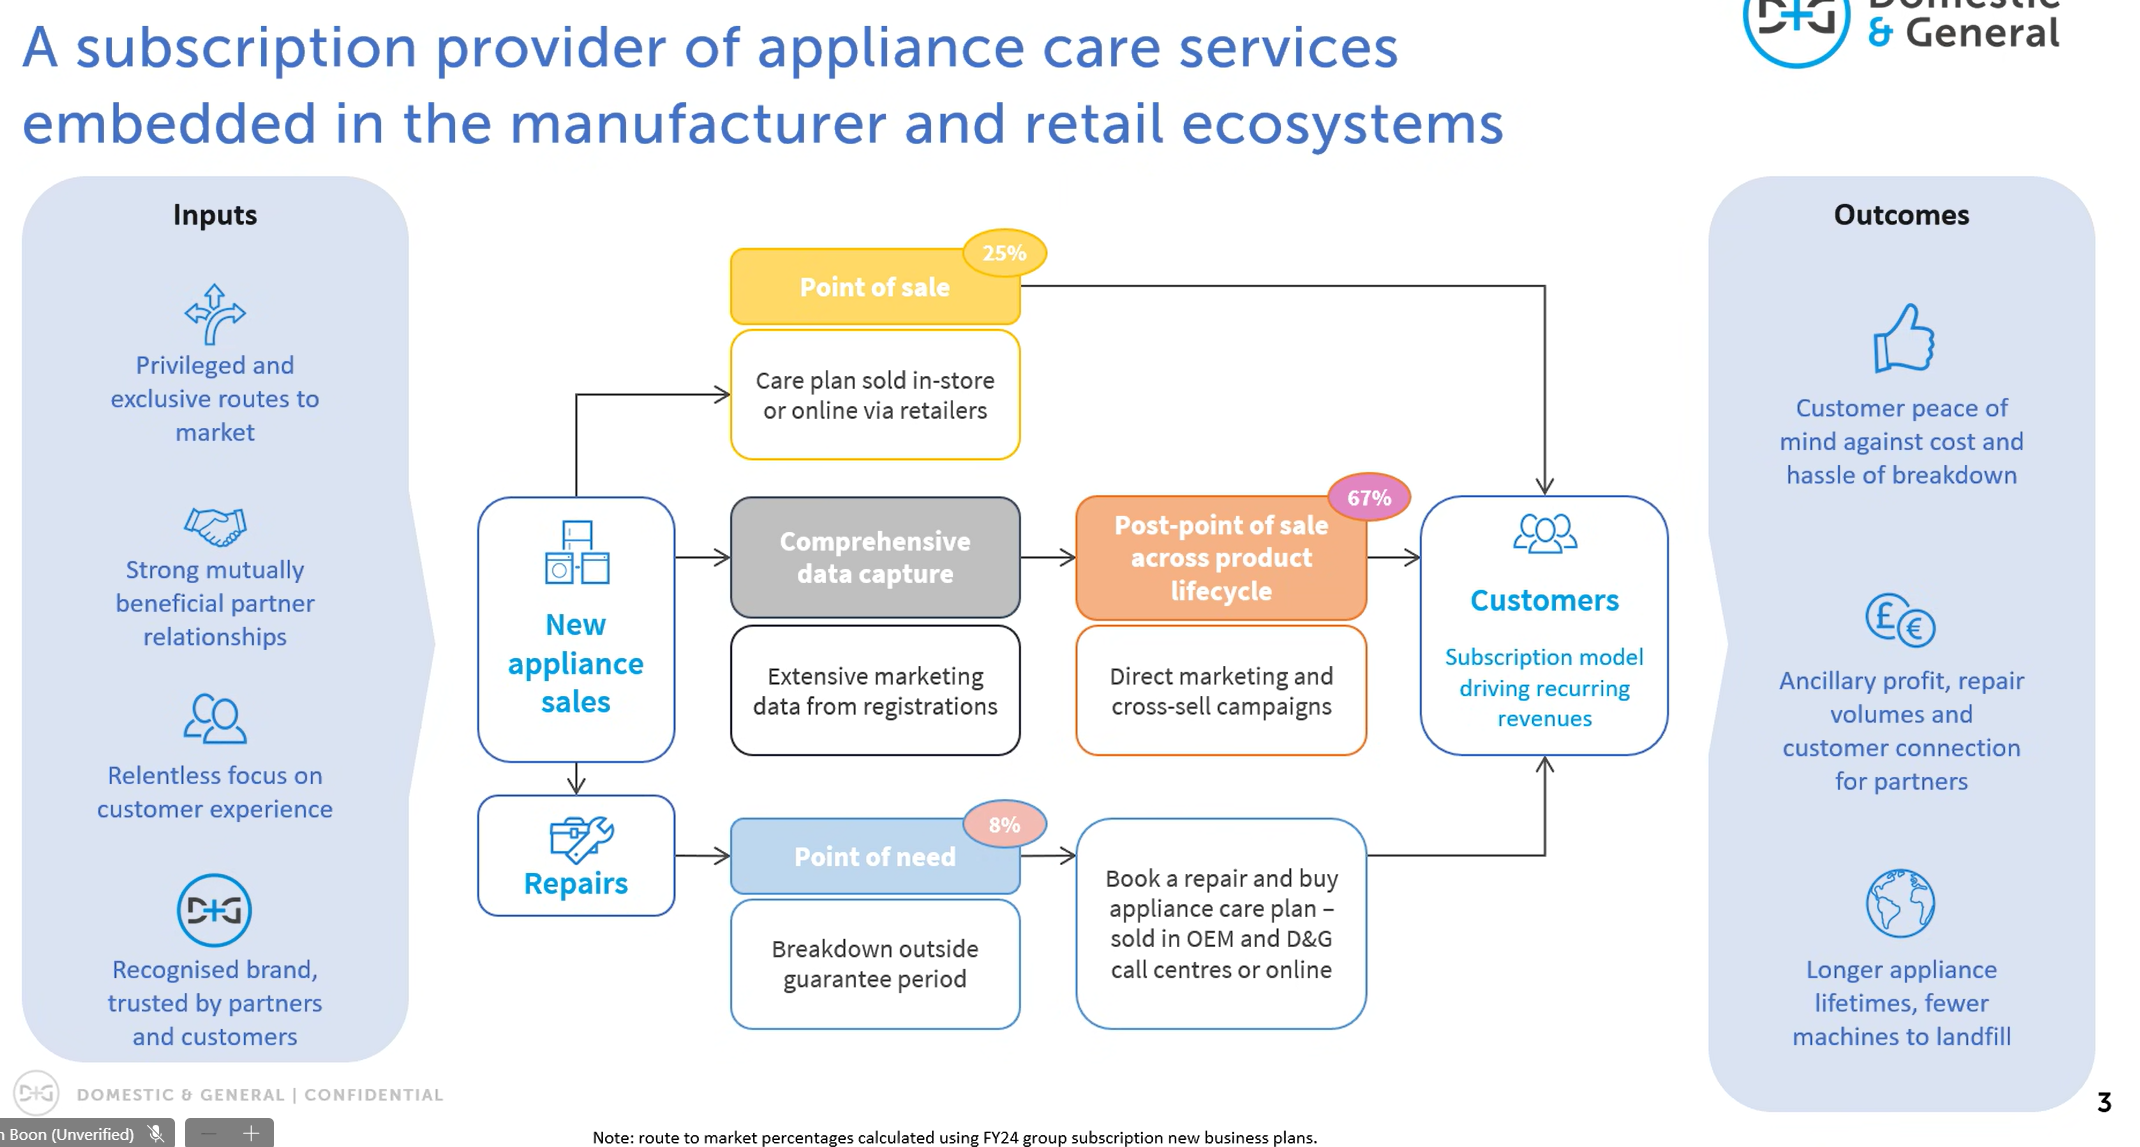
Most of the business come from post point of sale.
Competitors :
In the UK are retailers doing it themselves with insurance carriers or captive behind.
In Europe, Square Trade, casual term business.
OEM is less competitive because of the complexity of the LoB.
Not really major Insurers competing.
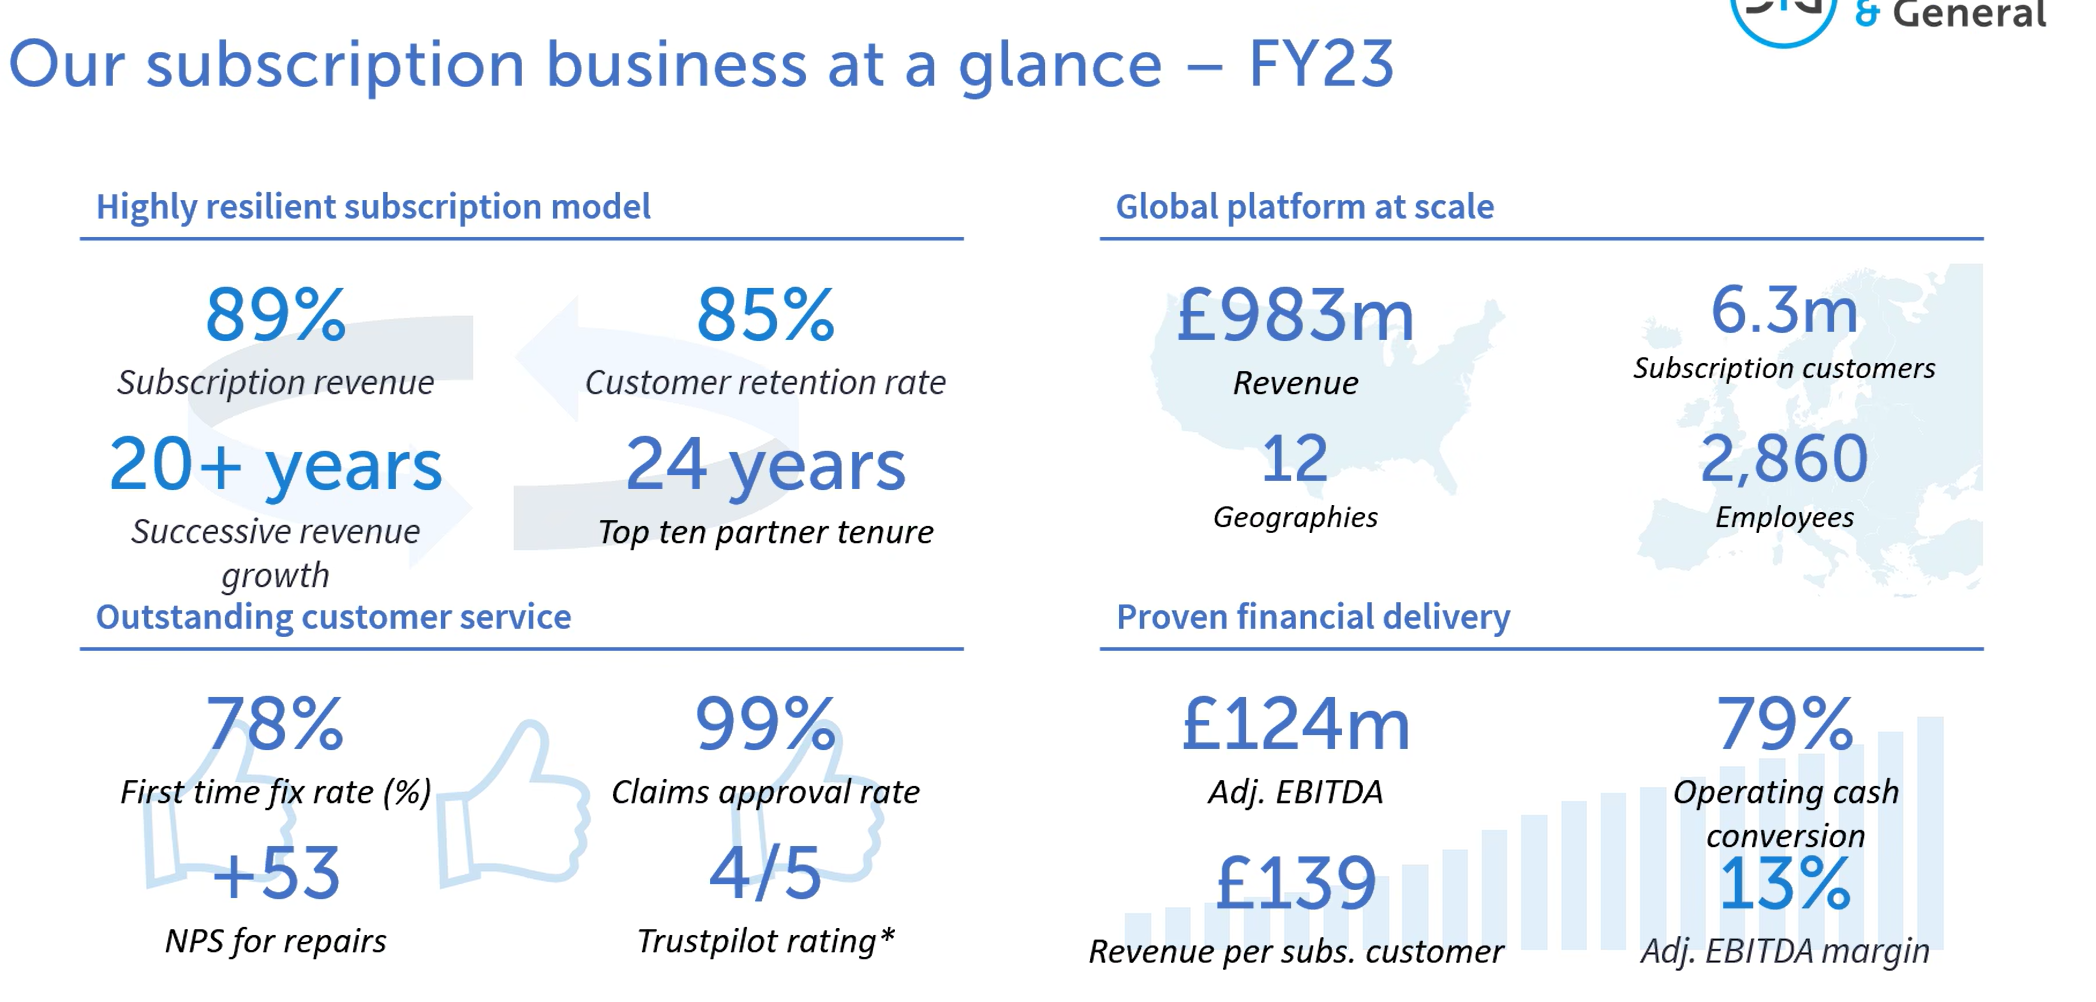
Barriers to new EU markets:
- They have passports and licence to opperate across europe
- But they want to get rid of regulatory complexity.
- They have turned down opportunities in EU because of regulatory reasons and cost of opportunitiy in regards to US business.
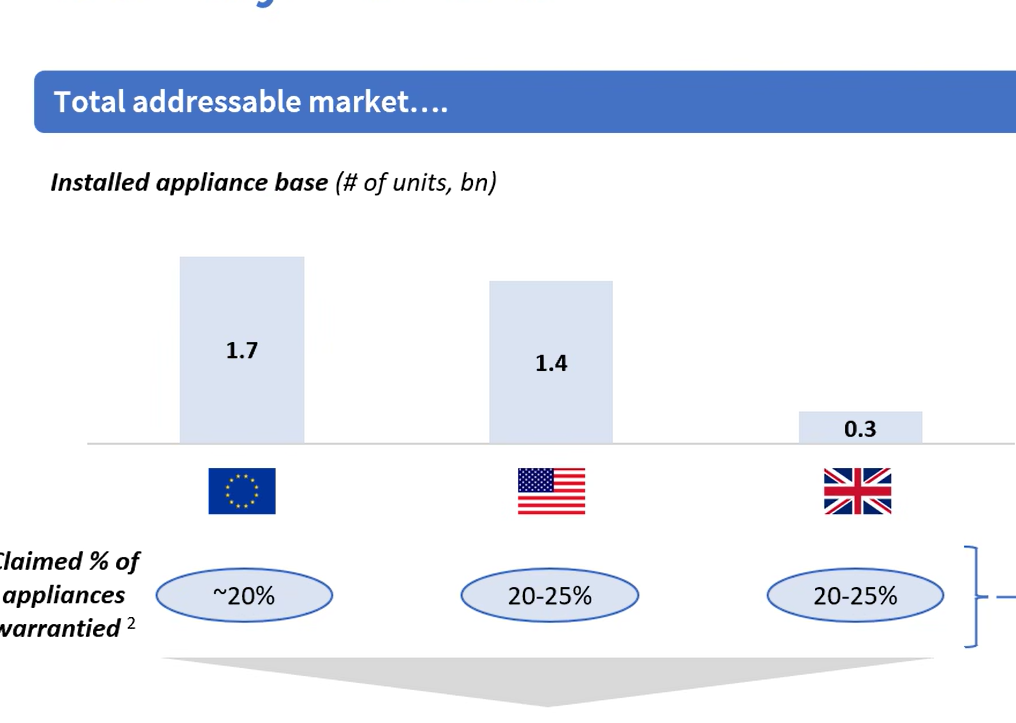
Target market is the US because Barrier languages and scalable.
2nd growth opportunity : Europe Pan european markets with digital solutions, althought EU market was harder to penetrate because of the retail market fragmentation, and language barriers, unscalability-
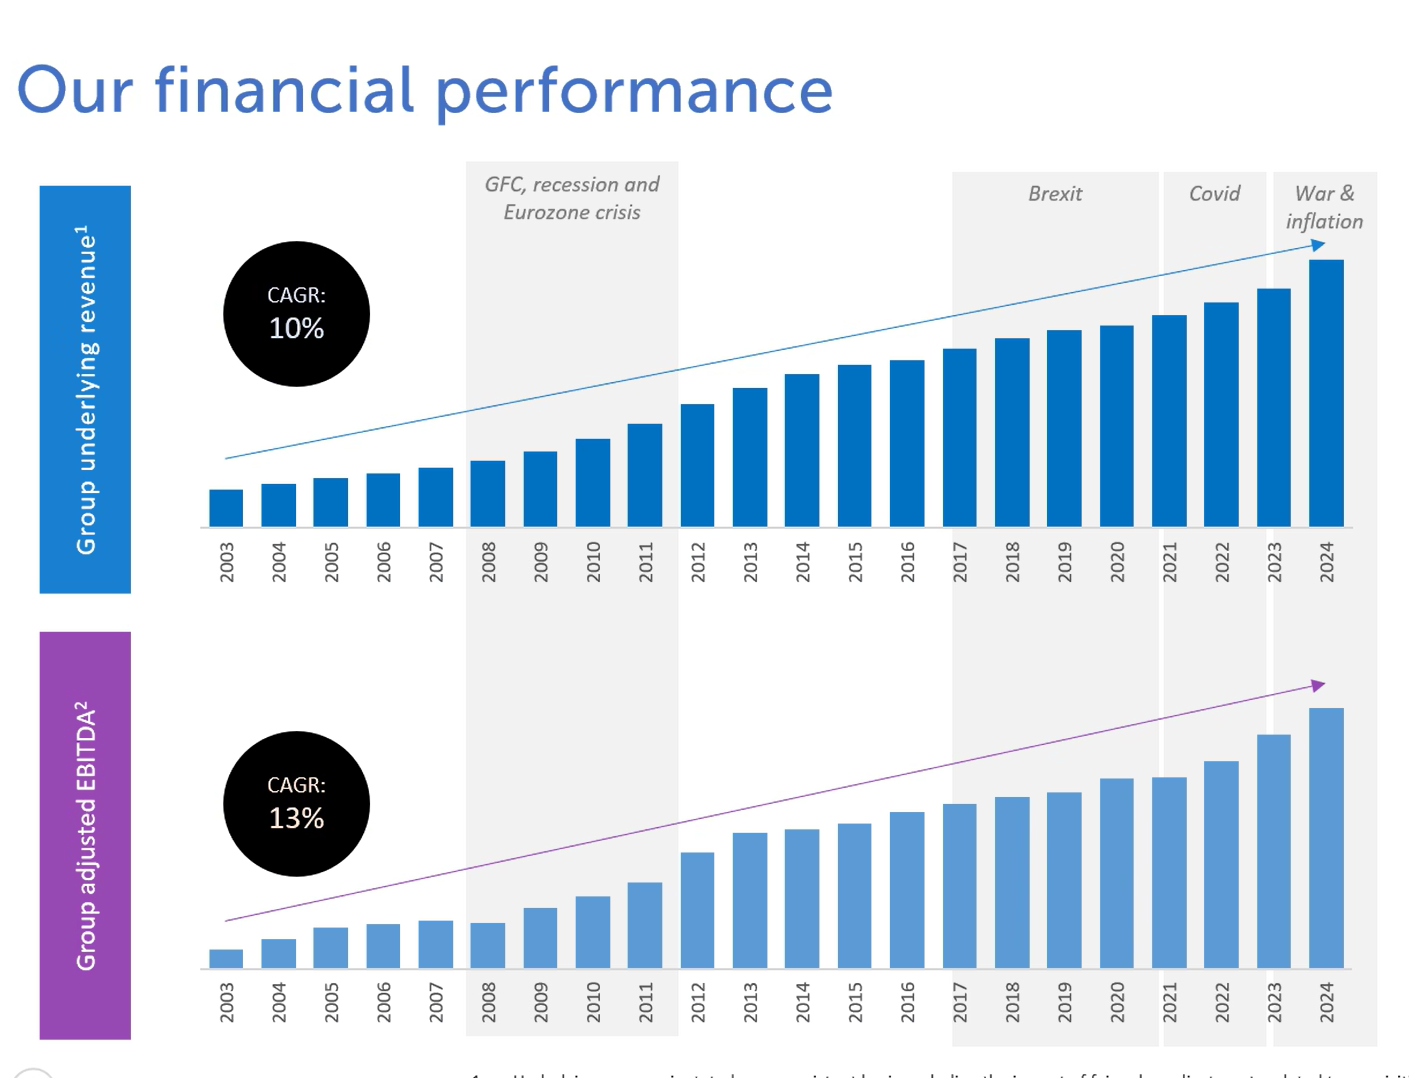
Business has been very resilient to Macro Economic events, with constant growth and profitabiltiy
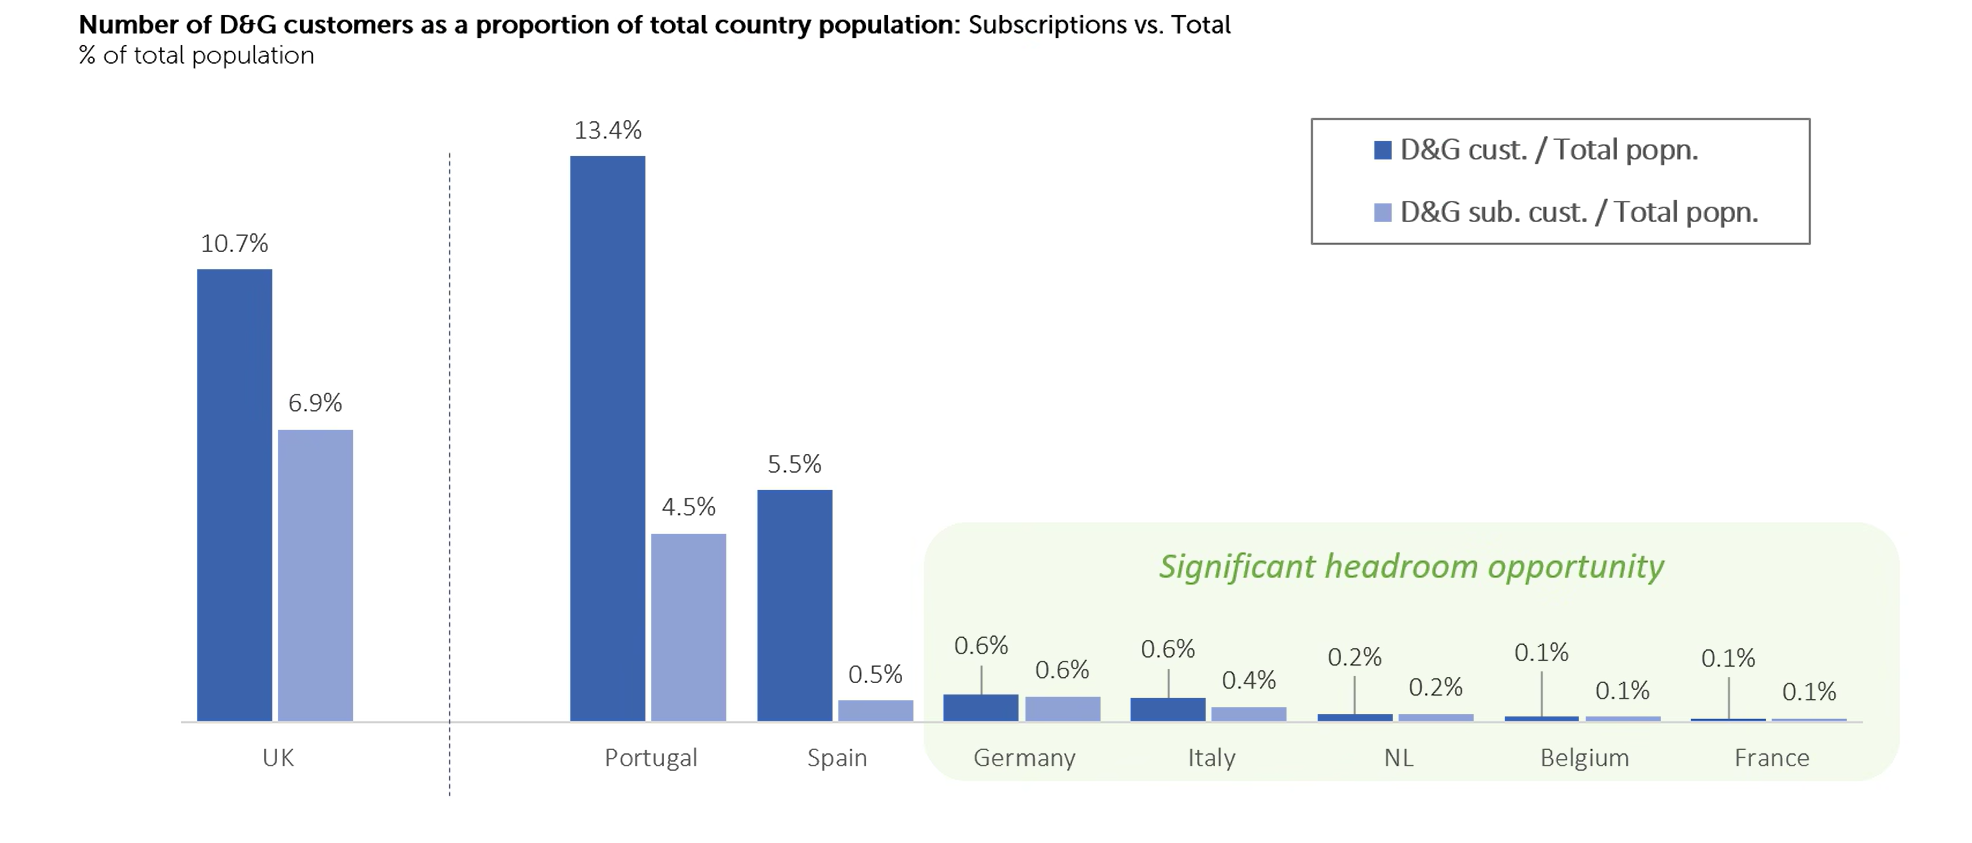
Penetration rates are still low in Europe.
Spanish account has not been doing a lot of subscriptions.
Non subscription business will decrease with this spanish account expiring.
David, commissions on subscription model ?
They sell both products, and migrate over time.
Mga will pay advanced commissions
Conversions rate is higher with subscription models.
Cash business -> Subscription (60% uk, 60% 70%)
Post point sale:
- Contact them with the info they provided
- After a claim the can cross sell
- EU ( more retail focused).
Level commission:
OEM: less commission on retail points of sale.
Motivation switching to MGA:
- MGA will pay advanced commissions to the retailer.
Operations
They don’t expect major cost reductions, besides actuarial functions and little compliance functions
Regulatory Burden
Why FOS and not brunches?
In most territories it is the case, branches were opened during the brexit.
They also did it for reputational reason.
If they were to enter a new market they would do it under a MGA structure.
What kind of regulattory constraines?
Understanding local nuances of each partner.
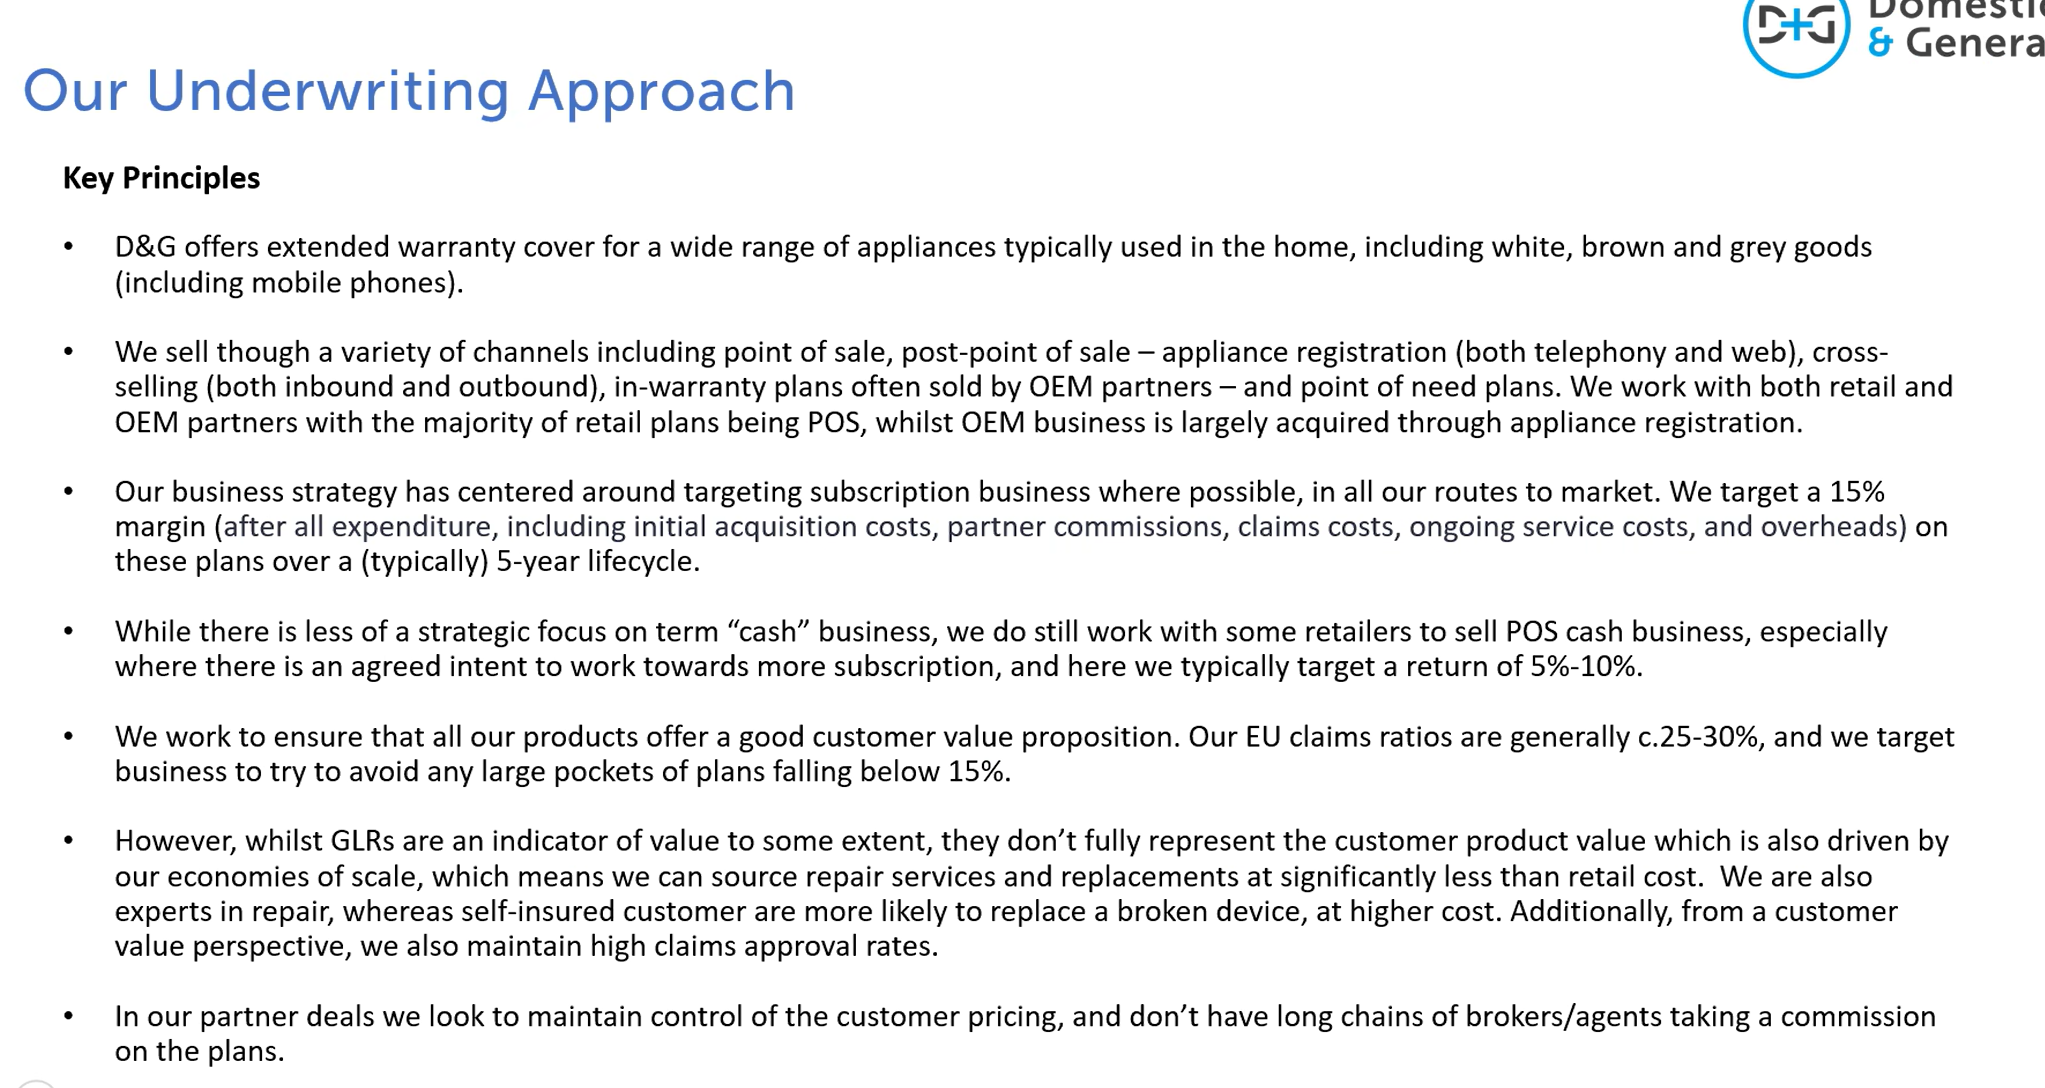
Pricing can change during the course of the policy.
Competitive advantage vs. SPB:
Customizable product, they do everything.
Chain value
Overall package
Product:
Appliances : AD and EW
Mobile Phones: customizable deductibles, Theft more flexible.
Questions
- Existing insurance company will change permissions and surrender insurance licencees and become overnight an MGA and invite customers to change of insurer.