Liabilities
In financial accounting, a liability is defined as the future sacrifices of economic benefits that the entity is obliged to make to other entities as a result of past transactions or other past events,[1] the settlement of which may result in the transfer or use of assets, provision of services or other yielding of economic benefits in the future.
A liability is defined by the following characteristics:
- Any type of borrowing from persons or banks for improving a business or personal income that is payable during short or long time;
- A duty or responsibility to others that entails settlement by future transfer or use of assets, provision of services, or other transaction yielding an economic benefit, at a specified or determinable date, on occurrence of a specified event, or on demand;
- A duty or responsibility that obligates the entity to another, leaving it little or no discretion to avoid settlement; and,
- A transaction or event obligating the entity that has already occurred.
Liabilities in financial accounting need not be legally enforceable; but can be based on equitable obligations or constructive obligations. An equitable obligation is a duty based on ethical or moral considerations. A constructive obligation is an obligation that is implied by a set of circumstances in a particular situation, as opposed to a contractually based obligation.
The accounting equation relates assets, liabilities, and owner's equity:
{\displaystyle {\text{Assets}}={\text{Liabilities}}+{\text{Owner's Equity}}}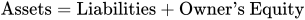
The accounting equation is the mathematical structure of the balance sheet.
Probably the most accepted accounting definition of liability is the one used by the International Accounting Standards Board (IASB). The following is a quotation from IFRS Framework: