fed reserve bak
==
format problem see bak (is none? powell? 1020 --> txt)
html Echoes
promote 2nd 4/18 see
oops see thefed bak
Nomi Prins
moderation but interest of corps?
===
mma
Trump sycophants are trying to bully the Federal Reserve away from expected interest rate cuts
Fox Business host Larry Kudlow has been leading the right-wing charge to attack the Federal Reserve this year
Written by Zachary Pleat
Published 08/28/24
Former president and current Republican presidential nominee Donald Trump and his media allies have already begun laying the groundwork to intimidate the Federal Reserve away from expected interest rate cuts this September. Trump and one of his long-time advisers and allies in particular, Fox Business host Larry Kudlow, have specifically demanded that the Fed take no action before the election in November, accusing it of purposefully boosting the economy in the short-term in order to benefit Democrats.
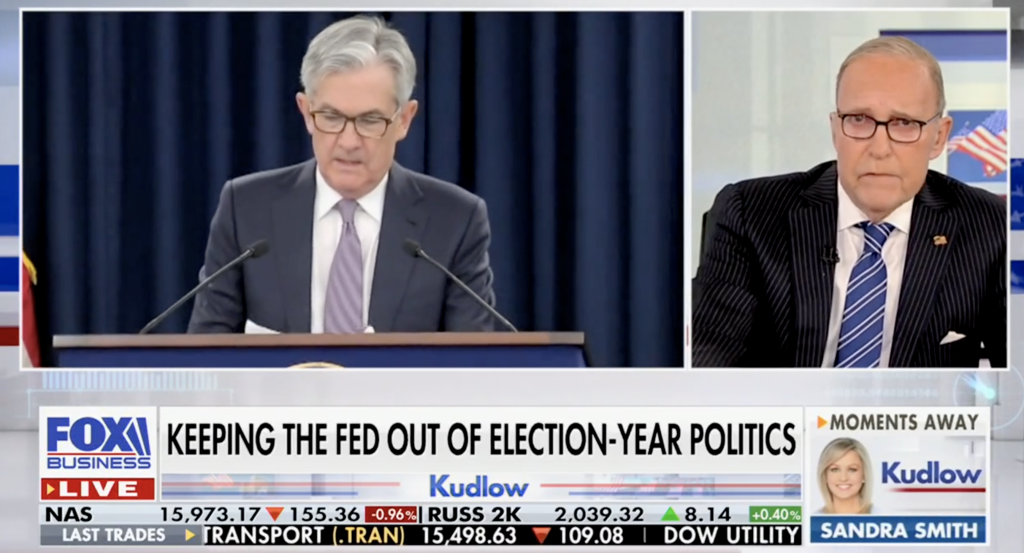
After employment statistics came in below expectations, including downward revisions for job creation in the previous year, and in light of increasingly stable inflation data, Federal Reserve Chairman Jerome Powell announced on August 23 that “the time has come” for interest rate cuts. Many economists had already been clamoring for the Fed to relieve pressure on the economy by lowering interest rates, with some citing an underwhelming July 2024 jobs report as evidence the Fed should have acted sooner.
The Fed is an independent agency and presidents traditionally do not interfere with its interest rate decisions. Trump broke with that tradition during his presidency as he appeared to sour on the independence of his own appointed chairman, Powell. As The Wall Street Journal reported, “beginning in the 1990s, presidents avoided publicly complaining about the Fed,” but as Trump’s “trade war unsettled markets, he steadily berated the Fed chair and called for lower rates.”
The Journal also reported that “Biden has mostly avoided discussing Fed policy, reverting to pre-Trump tradition.” (Biden re-appointed Powell to run the nonpartisan central bank for a second term in late 2021.) Additionally, Forbes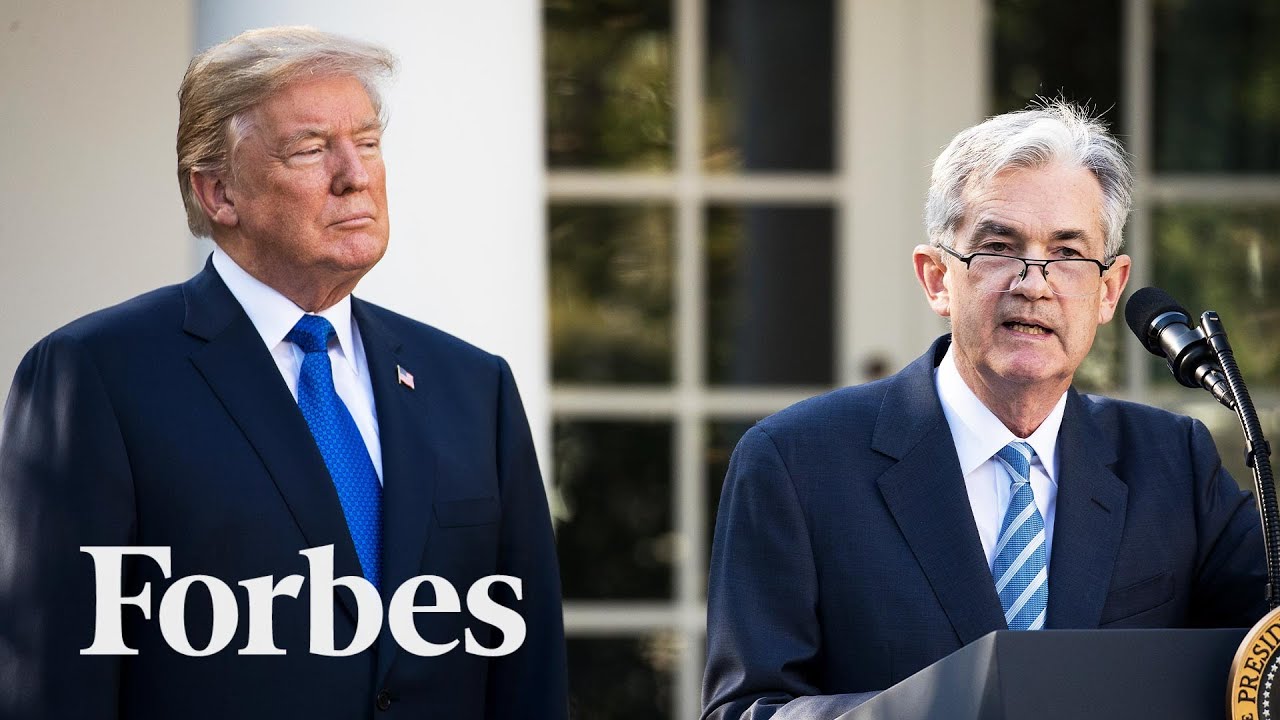 that according to former Trump Cabinet official Wilbur Ross’ upcoming memoir, in 2018, “Trump demanded his Commerce Secretary, Wilbur Ross, call the chair of the Federal Reserve … and demand that he cut interest rates.”
The Journal explained that it’s not unusual for the Fed to change interest rates during election years; it has previously done so in 2004, 2012, and 2020. Yet right-wing media began projecting politicization onto the upcoming rate cuts following recent economic reports, joining Fox Business host and former Trump economic adviser Larry Kudlow, who as far back as January began trying to bully the Fed out of cutting rates prior to the election.
Earlier this year, Trump and his allies preemptively attempted to bully the Federal Reserve away from cutting interest rates prior to the presidential election
- Trump and his allies warned the Fed against cutting interest rates prior to the election. The Wall Street Journal reported that in a June Bloomberg Businessweek interview, Trump said cutting interest rates before the election is something that Fed officials “know they shouldn’t be doing.” The story also quoted Michael Faulkender, chief economist at the Trump-aligned America First Policy Institute, who “said starting a rate-reduction campaign before the election would tarnish the Fed’s credibility.” The Wall Street Journal, [7/31/24]
- Fox Business host Larry Kudlow said the only reason for Powell to cut interest rates would be if the Fed “wants to completely politicize monetary policy, and slash interest rates in order to juice the economy and re-elect Biden.” Instead, Kudlow suggested that Powell “is an honorable man” who would not seek another term as Fed Chair regardless of the election result, and instead “establish his historical reputation” for getting inflation back to the target level. Fox Business, *Kudlow*, [1/17/24]
- Kudlow claimed that Biden’s prediction of lower interest rates meant, “The big guy wants a little juice from the Fed to get re-elected.” Kudlow then countered that “for all the cynical talk about how the Fed somehow must bend to the political whims of the president and his little minions, I actually think Powell is immune from that kind of thinking.” Fox Business, *Kudlow*, [3/15/24]
- Kudlow said the Fed would “just be creamed, reamed, destroyed,” and that Trump and Republicans would “correctly go after” it if there is an interest rate cut — unless it happened after the election. “Well, they could cut two times after the election, OK,” Kudlow said with a laugh. Fox News, *America Reports*, [4/5/24]
- Kudlow later imagined that Biden would be the one to attack the Fed for not cutting rates. During a panel discussion on his Fox Business show, Kudlow said: “Joe Biden forecasted rate cuts. He did it at least twice, maybe three times. He’s going to be very disappointed. Do you think he’ll attack the Fed?” Fox Business, *Kudlow*, [5/1/4]
- Kudlow declared, “The Fed can’t cut interest rates, because if they do, it’ll be so political.”Fox Business, The Big Money Show, [5/15/24]
- Right-wing legal activist Paul Ingrassia wrote that “the Federal Reserve needs to raise interest rates now” to prove that it’s independent. Ingrassia added: “But unfortunately we’re in the midst of a presidential election cycle, so they won’t raise rates because it’s not politically advantageous for Kamala Harris.” Twitter/X, [8/5/24]
Some conservatives fabricated a conspiracy theory that a routine revision of jobs reports was done specifically to push the Fed into cutting rates
- The Daily Wire’s Ben Shapiro pushed a conspiracy theory that the annual Bureau of Labor Statistics revision to jobs reports was deliberately timed “to jog the Federal Reserve to lower interest rates” in time for the election. Shapiro said: “You have to understand the game that's being played here. For the entirety of this year, the federal government has been radically overestimating the number of jobs created under the Biden administration so that he can go around bragging about jobs that he didn't create. OK, that revision is likely to be in the range of at least 600,000 jobs they say exist that do not exist in the Biden economy. Now why is that coming out right now?
- Because the goal is to jog the Federal Reserve to lower the interest rates and thus to blow more money into the economy, recapitulating inflation, and to do that off the basis of weak job growth. So that is the game. The game is: you hide the job failures until now. Then you let that news out of the bag just early enough that the Federal Reserve can lower the interest rate and then artificially boost spending in the economy.” (In fact, these revisions are scheduled at the same time every year as more accurate jobs data become available, and one previously showed a revision of -501,000 jobs in 2019 under Trump.) The Daily Wire, *The Ben Shapiro Show*, [8/21/24; Media Matters, 8/21/24]
- Shapiro also spread the conspiracy theory on X. On X, formerly known as Twitter, Shapiro wrote: “This is amazing for two reasons.1. They've been lying for a year about Biden job creation. 2. They're dumping this data just in time to justify a Federal Reserve interest rate decrease for the election.”Twitter/X, [8/21/24]
- Right-wing commentator Bill Mitchell pushed a similar conspiracy theory: “WE GOT PLAYED” on the BLS jobs report revision; “That was just cover to let the Feds cut interest rates before the election.” Twitter/X, [8/23/24]
Conservatives are increasingly accusing the Fed of cutting rates to help Democrats, or framing the cuts as political
- Fox host Sean Hannity: “Watch the Fed. Mark my words: September, they’re going to lower rates to help Kamala and Tim Walz.” Premiere Radio Networks, The Sean Hannity Show, [8/14/24]
- Shapiro: “They’re going to shove a Fed rate cut through as fast as humanly possible,” and “the idea that politics comes into their considerations not at all is ridiculous.” Shapiro added, “The notion of Federal Reserve independence is complete hogwash.” The Daily Wire, The Ben Shapiro Show, [8/15/24]
- Shapiro: “There is one sort of last hope for Joe Biden, and that is maybe Jerome Powell will save him” with interest rate cuts “just in time for the election, almost as if it’s on cue.” Shapiro continued: “It’s just so convenient. … We got to cut those interest rates just in time for the election and hopefully jog Joe Biden to victory. But don’t worry, it’s all apolitical.” The Daily Wire, The Ben Shapiro Show, [7/12/24]
- Right-wing X account End Wokeness posted: “If the Biden-Harris economy is so strong, why cut rates before the election? 🤔This announcement either means: 1. The economy is about to tank. 2. The federal reserve wants to artificially boost the economy before the election. 3. All of the above.” Twitter/X, [8/23/24]
- Conservative Substack author amuse: “ELECTION INTERFERENCE? Powell confirmed the Fed would be cutting rates between 25bps to 50bps in September depending on the August payroll report.” Twitter/X, [8/23/24]
- Gateway Pundit: “Fed Chair Announces Incoming Rate Cut… Just in Time to Boost Kamala Harris.” The Gateway Pundit, [8/23/24]
---
https://www.alternet.org/2022/06/economy-tanks-thank-ronald-reagan/
yesterday the Fed started something it hasn't done for quite a while. It started dumping bonds.
The Fed has been goosing the economy steadily since the Bush Crash of 2008, buying US and corporate bonds with money it creates out of thin air (only the Fed can "print money" like this by simply willing the dollars into existence).
By purchasing and holding those bonds over the past 14 years, the Fed has created and then flushed into our economy$8 trillion in liquid cash. This is how the Fed stimulates an economy in crisis: pouring newly-created money into the system.
As a result, our economy has been running on high-octane sugar-high stimulus (free money from the Fed, as you can see above) ever since 2008.
Several trillion of that came in the last year of the Trump presidency. While Republicans scream about spending for social needs that might also stimulate the economy, they and Trump were quite happy to see that money from the Fed.
But now the Fed and it's Trump-appointed Republican Chairman, Jerome Powell, are backing off.
Yesterday the Fed started selling those bonds, reversing the process after 14 years and now sucking money out. Instead of stimulating the economy, they're trying to slow it down in the hope that will cool off inflation.
When they receive the money back from those sales they'll simply drop it into the same Schrödinger's Cat-box from which it came: it'll vanish into the icy, dark depths of fiscal interstellar space, never to be seen again. What the Fed creates, the Fed can dissolve.
This month the Fed expects to "retire" $47.5 billion from its balance sheet — retire that amount from our economy — rising to $90 billion a month by the end of the summer.
While these aren't huge sums in the grand scheme of things, the very fact that the Fed has gone from pumping created-from-nothing money into the economy to pulling that money back out is a Very Big Deal.
Add that to its plan to continue increasing interest rates, which also slows the economy, and we're looking at a potential Category 5 event.
Thus, the Financial Times was the bearer of the predictable bad tidings yesterday. Just from that day's FT's (digital) front page's "Live News Updates" column, these were some of the headlines:
- Ford forecasts car industry consolidation as capital becomes constrained
- Treasuries and US stocks slip as investors gird for monetary policy tightening
- Bank of Canada prepared to 'act more forcefully' after latest rate rise
- European stocks enter June on a muted note after turbulent month
- German retail sales fell 5.4% in April
- UK house price growth slows in May
- China's manufacturing sector activity shrinks for third consecutive month
- Government bonds sell off as eurozone inflation hits record high
- JPMorgan chief says 'hurricane' is bearing down on economy
In that last article, JPMorgan CEO Jamie Dimon, who a week ago had predicted "storm clouds" on the economic horizon, became far more blunt yesterday.
'I said they're storm clouds, they're big storm clouds here,' Dimon said, adding, 'It's a hurricane.'
Elaborating that the war in Ukraine and Europe's disconnection from Russian fossil fuel markets could drive oil as high as $175 a barrel, Dimon worried out loud:
That hurricane is right out there down the road coming our way. We just don't know if it's a minor one or Superstorm Sandy . . . And you better brace yourself.
So, how did we get here?
Between the Republican Great Depression of 1929-1937 and Reagan's inauguration in 1981, the United States experienced a few recessions, but nothing as severe as Republican President Herbert Hoover oversaw back on Black Tuesday, October 29, 1929.
Hoover's crash was set up by the election of 1920, when Republican Warren Harding convinced Americans to abandon the trust-busting, high tax, progressive policies of Presidents Teddy Roosevelt, William Howard Taft, and Woodrow Wilson in favor of that generation's version of neoliberalism or what we today call Reaganomics.
Harding referred to it as "Horse and Sparrow Economics" — it was the early 20th century version of what Reagan later reinvented as "trickle-down economics."
If the horses (rich people and big business) were fed more oats (through deregulation and tax cuts), more of those oats would pass undigested into the horse manure that then littered the streets of American. The sparrows (working class Americans) could then pick the extra oats out of the manure.
In 1920, Warren Harding won the presidency on a campaign of "more industry in government, less government in industry" — privatize and deregulate — and "a return to normality," his promise to drop the top tax bracket from its then-91 percent rate down to 25 percent.
Harding kept both promises, putting the nation into a sugar-high spin called the Roaring '20s, where the rich got fabulously rich and working-class people were being beaten and murdered by industrialists when they tried to unionize. Harding, Coolidge, and Hoover (the three Republican presidents from 1920 to 1932) all cheered on the assaults, using phrases like "the right to work" to describe a union-free nation.
In the end, the result of the "horses and sparrows" economics advocated by Harding was the Republican Great Depression (yes, they called it that until after World War II).
FDR's response to Hoover's Depression was to raise the top income tax bracket back up to 91% and impose stiff regulations on banks and Wall Street, creating the Securities and Exchange Commission (SEC) and putting Joe Kennedy in charge of it.
Gloria Swanson, who knew Kennedy well and intensely disliked him (he'd robbed and exploited her), told me over one of our many dinners in her New York apartment that FDR knew, "It takes a crook to catch a crook." And FDR was going after the crooks.
High taxes on the morbidly rich and aggressive government enforcement of banking and securities rules prevented another large-scale crash for a half century until Reagan came along and repeated Harding's mistakes in the 1980s.
After Reagan finally dropped the top tax rate from the 74% he inherited when he came into office to 28% there was a one-day 22% stock market crash — Black Monday on October 27, 1987 — that rivaled 1929's Black Tuesday for the first time.
When Reagan deregulated the Savings & Loan industry the banksters stole so much money they crashed S&Ls across America, the first serious bank panic since the Republican Great Depression.
We're still living in Reagan's neoliberal deregulated economy. It brought us two financial crises while he was President, the dot-com bubble-bust of 1999/2000, the Bush Crash of 2008, and arguably the trillion-dollar-heist of 2020 when Trump passed out money to his fat-cat buddies without controls (we're still trying to figure out where all that money went).
Now, if Dimon is right, hang onto your hat for another "event."
The core tenet of both Harding's and Reagan's versions of neoliberalism is that the economy is essentially a force of nature. It's why Harding did away with regulations on stock speculation and why Reagan deregulated everything he could as fast as he could.
The economy "operates according to its own rules," they'd tell you, and anything government does to interfere with it will simply produce a bad outcome.
In actual fact, the opposite is true.
Players in the top reaches of finance, banking, and speculation are much like players in boxing or football: they're engaged in a competitive high-stakes game defined by very specific rules, and when they know they can get away with breaking those rules, they'll often do it.
The difference is that instead of winning or throwing a football game or boxing match, when bankers and speculators violate the rules they can take down the entire economy.
The financial speculators, of course are rarely injured in the process. We bailed out the banksters and speculators in the 1980s, 1999/2000, 2008, and 2020 to the tune of trillions of dollars. Senior executives and shareholders took home hundreds of billions of those dollars, looting the system they themselves had crashed.
Since 2008, most of that money was created out of thin air by the Fed. Now the Fed wants it back, but the banksters and speculators have already stashed it in their offshore tax havens. As a result, working class Americans and small- and medium-sized businesses will largely foot the bill.
Dimon and the purveyors of doom may be wrong about a crisis at this particular moment, but the system is still shaky and fraud is rife across banking, brokerage and finance, as Elizabeth Warren and Katie Porter continually remind us.
As I lay out in The Hidden History of Neoliberalism: How Reaganism Gutted America, it's probably going to take another 1929-type event to shake Americans up enough to reject Reagan's vision of a deregulated economy and put the nation back on the course of the stable and steady Keynesian growth that FDR gave us from 1933 to 1981.
Now, in addition to an economy held together with the baling-wire of Fed stimulus (that's coming to an end), both the US and the world are facing a wild spectrum of assaults that could have huge economic impacts.
And Republicans are committed to doing everything they can to cripple our economy, refusing to pass much of Biden's economic agenda, in their belief that a Crash will help them in the 2022 and 2024 elections.
Between the worldwide food and oil crises the Russian invasion of Ukraine are provoking, billions in climate change damage and millions of climate change refugees, Republican intransigence, and the Fed's claiming back that $8 trillion they gave our banksters and speculators, a real crisis may be at our doorstep sooner than any of us would like.
Brace yourself.
==
https://www.alternet.org/2020/11/trump-fed/
alexh
no twt
In the financial world, there has been much discussion over the nomination of Judy Shelton — a former campaign adviser for President Donald Trump — for the board of the U.S. Federal Reserve. Shelton is likely to be confirmed by the U.S. Senate, where Republican senators are still terrified of offending Trump even though he lost the 2020 presidential election to Democratic nominee Joe Biden. And according to Washington Post columnist Catherine Rampell, Shelton's likely confirmation is a travesty.
"The Senate is expected to vote as soon as this week on Trump's nomination of Judy Shelton to the Fed," Rampell explains. "Simply put, Shelton is a demonstrably unqualified partisan quack who has no business working at the world's most powerful central bank. Her nomination has been condemned by hundreds of economists and Fed alumni, including prominent Republicans and at least seven Nobel laureates. The senators poised to confirm her appear to know she is unfit; ahead of February hearings, a former Republican Senate Banking Committee aide said that 'the idea of even calling her as a witness for something was beyond the pale' not long ago."
rampell cites someexamples of why many economists consider Shelton a "quack," including "her multi-decade effort to bring back the gold standard" — which, Rampell notes, "might be popular among the right-wing fringe, but it was abandoned worldwide long ago and remains almost unanimously rejected by economists. For good reasons, including that gold prices are volatile. Linking the dollar to gold can also restrict liquidity when the economy needs it most — as happened during the Great Depression."
On top of that, Rampell adds, Shelton has "questioned whether the Fed should even exist."
shelton's nomination, Rampell argues, is based on political considerations — not real economic policy.
"Another pending Fed nominee, Christopher Waller, is qualified for the job and still hasn't gotten a vote," Rampell observes. "Yet somehow, Shelton is getting jammed through ahead of him. One possible explanation: a desire to salt the earth for incoming President-elect Joe Biden."
Rampell concludes her column by arguing that perhaps Republicans want Shelton on the Federal Reserve board in order to hurt the incoming Biden Administration on economic policy.
The Post columnist warns, "Shelton's confirmation could represent a point of no return for corrupting the mission and functionality of the Fed, and destroying whatever bipartisan resolve remained to not tank the economy for political gain…. I hope I'm wrong — both that Shelton is about to be approved and that her confirmation would escalate efforts to sabotage the job market or price stability while the other party is in power. But if I'm right, a dark new economic era looms."
FROM YOUR SITE ARTICLES
- Trump sent the stock market careening right after the Fed chair gave ... ›
- Trump's pick for the Fed admits he doesn't know how the Fed works ... ›
- Trump-appointed Fed chair just completely undercut the GOP's ... ›
https://www.alternet.org/2020/10/billionaires-rich/
igor salon
Billionaire wealth increased to $10.2 trillion through the end of July, setting a new record amid the coronavirus pandemic even as millions of unemployed people fall into poverty.
Wealth held by billionaires around the world rose to $10.2 trillion in July, up from the previous record of $8.9 trillion in 2017, according to an analysis by Swiss bank UBS and consulting firm PwC.
The number of billionaires also rose from 2,158 in 2017 to 2,189 this summer, according to the report.
Not all billionaires saw their wealth increase, though some saw their wealth rise by close to 50%. Health care billionaires, for example, saw their wealth increase by 50%. Technology billionaires saw their wealth rise by 42.5%. Billionaires in the entertainment, financial services, materials, and real estate sectors saw increases of 10% or less.
While the UBS analysis looked at billionaires around the world, a separate analysis by the Institute for Policy Studies and Americans for Tax Fairness found that billionaire wealth in the United States has grown by $792 billion, or 27%, since the beginning of coronavirus lockdowns in March. The combined wealth of American billionaires now tops $3.7 trillion.
Some prominent billionaires have done particularly well. Amazon CEO Jeff Bezos has seen his wealth rise more than 60% during the pandemic to $195 billion through late August, according to the analysis. Tesla CEO Elon Musk saw his wealth more than triple to $85 billion over that time frame.
The study pointed to President Donald Trump's 2017 tax cuts, which helped billionaires keep more of their earnings. The UBS study noted that Trump's desired capital gains tax cut, billed as a pandemic-related stimulus, would overwhelmingly favor the richest Americans.
"For billionaires, this is a heads-we win, tails-you-lose economy, boosted by Trump policies to funnel wealth to the top," Chuck Collins, the head of the Institute for Policy Studies' Program on Inequality, said in a news release.
"The pandemic profiteering of America's billionaires shows taxes on the wealthy must go up substantially to narrow the wealth gap and raise revenue vital for our big climb back from disaster," added Frank Clemente, executive director of Americans for Tax Fairness. "By demanding even more tax cuts for the rich at this crucial moment President Trump shows he is as out of touch with our nation's needs as America's billionaires are disconnected from our nation's misery."
Some executives, like Zoom CEO Eric Yuan and Bezos, have profited from a boom in business caused by the lockdowns. Others have profited directly from government aid distributed to their companies. But most billionaires saw their wealth increase due to rising investments, buoyed by a stock market surge propped up by government assistance.
The rising wealth amid an economically devastating pandemic threatens to deepen longstanding inequalities.
"Extreme wealth concentration is an ugly phenomenon from a moral perspective, but it's also economically and socially destructive," Luke Hilyard, the executive director of the High Pay Center, a think tank that focuses on excessive executive pay, told The Guardian.guk "Anyone accumulating riches on this scale could easily afford to raise the pay of the employees who generate their wealth, or contribute a great deal more in taxes to support vital public services, while remaining very well rewarded for whatever successes they've achieved. The findings from the UBS report showing that the super-rich are getting even richer are a sign that capitalism isn't working as it should."
UBS executive Josef Stadler also acknowledged that billionaires could face societal backlash over their growing wealth as many people face months if not years of struggles.
"We're at an inflection point," he told the outlet. "Wealth concentration is as high as in 1905, this is something billionaires are concerned about. The problem is the power of interest on interest – that makes big money bigger and, the question is to what extent is that sustainable and at what point will society intervene and strike back?"
But it's far from the first time that billionaires profited while millions suffered. The Institute for Policy Studies found that the wealthiest 400 billionaires in the US not only recovered from the 2008 recession within three years but increased their wealth by 80% over the following decade. By comparison, the bottom 80% of earners have still not recovered.
While government intervention has helped billionaires accumulate even more wealth, the lack of government action since the spring has resulted in an estimated 8 million Americans falling into poverty since May, according to a study from researchers at Columbia University. The lack of additional stimulus payments and the expiration of enhanced federal unemployment benefits has resulted in 6 million Americans falling into poverty over just the last three months, according to a study from researchers at the University of Chicago and Notre Dame.
The problem has been even worse globally. Between 88 million and 114 million people around the world have fallen into extreme poverty, defined as living on less than $1.90 per day, since the pandemic hit, according to the World Bank. There are now more than 700 million people living in extreme poverty and researchers expected that number to keep rising.
"This is the worst setback that we've witnessed in a generation," Carolina Sánchez-Páramo, the global director of the World Bank's Poverty and Equity Global Practice, told The Wall Street Journal.
World Bank Group President David Malpass argued in a speech this month that the problem is worse in developing economies because "rich countries" have the resources to expand sweeping "government spending programs" while poorer economies have few tools to mitigate the economic damage.
The US, by contrast, should be doing better if not for Republican reluctance to increased government relief.Federal Reserve Chairman Jerome Powellwarned Congress last month that inaction in the face of growing inequality would be highly damaging to the economic recovery.
"Those are things that hold back our economy," he said at a news conference. "If we want to have the highest potential output and the best output for our economy, we need that prosperity to be very broadly spread."
Many analysts have also faulted Powell and the Fed for contributing to the growing inequality with policies "disproportionately benefiting stockholders," according to the Associated Press.
Just as the coronavirus has exposed longstanding health disparities between the richest and poorest Americans, the growing inequality is largely the result of a "catastrophic failure to tackle inequality" well before the pandemic struck, according to a report from Oxfam International.
"Governments' catastrophic failure to tackle inequality meant the majority of the world's countries were critically ill-equipped to weather the pandemic," said Oxfam interim executive director Chema Vera. "No country on earth was trying hard enough to reduce inequality and ordinary people are bearing the brunt of this crisis as a result. Millions of people have been pushed into poverty and hunger and there have been countless unnecessary deaths."
FROM YOUR SITE ARTICLES
- Economist Thomas Piketty: Coronavirus pandemic has exposed the ... ›
- No, we're not all in this together — the super-rich are cheating America ›
- Trump is overseeing a historic transfer of wealth to the super-rich as ... ›
RELATED ARTICLES AROUND THE WEB
- Wealth of US billionaires rises by nearly a third during pandemic ... ›
- American billionaires got $434 billion richer during the pandemic ›
- Billionaires are getting even richer from the pandemic. Enough is ... ›
220
aha: recessions are periodic, fed no suffic buffer? trump keeps money free to goose stock mkt so can boast 401k; blew up fed deficit, houshold debt and student debt high; authoritaian growing everywhere, what effect of worldwide reecession again? Greece?
==
Jerome Powell - Wikipedia
en.wikipedia.org › wiki › Jerome_Powell
1.
**Net worth**: $19-55 million
**Political party**: Republican
Education: Princeton University (BA); Georget...
Children: 3
What happens to Fed Chairman Jerome Powell if Trump gets ...
www.nbcnews.com › business › economy › what-happens-fed-chair-j...
1.
Does Trump Have the Legal Authority to Demote the Federal ...
www.nytimes.com › 2019/06/20 › politics › trump-fed-chairman-powell
Jun 20, 2019 - President Trump has been attacking the Federal Reserve and its chairman, Jerome H. Powell, because he is angry that the central bank's ...
Trump expresses fresh regret about his Fed chief: 'Oh well ...
www.politico.com › story › 2019/09/06 › donald-trump-jerome-powe...
1.
why conpiracy theory, creature jekyll island, gold nuts
or several years, Fox figures have been clamoring for Michael Flynn to drop his guilty plea for lying to the FBI and stop cooperating with the government, in the hopes that he receives a presidential pardon. They may now be one step closer to that wish. This week, Michael Flynn fired his legal team andreplaced them with Sidney Powell.
A former federal prosecutor, Powell has become a Fox News pundit who regularly dabbles in conspiracy theories. She has helped Fox News push thealternate narrative that the Mueller investigation was the result of an illegal anti-Trump conspiracy by the "deep state." Powell has made more than two dozen appearances on Lou Dobbs' Fox Business show, and at least nine additional weekday appearances on Fox News since January 2018.
In addition to promoting conspiracy theories about government investigations on Fox, Powell has also promoted a number of conspiracy theories on Twitter. Powell has tweeted posts from Infowars and also retweeted major accounts that promote the QAnon conspiracy theory. She accused the Federal Reserve of deliberately trying to "#crash the market" in a ploy to destroy Trump "and enrich #Soros & themselves. #Soros has done it before."
Powell's own website sells T-shirts describing Mueller and six other key law enforcement figures in the case as “Creeps on a Mission.” The shirt is billed as “a great gift for those who know the Mueller investigation of the President is its own crime.” Naturally, Trump enthusiastically applauded Flynn's decision to hire the Fox commentator.
==
https://www.alternet.org/wall-streets-corruption-runs-deeper-you-can-fathom
[quite long]
Of the myriad policy decisions that have brought us to our current precipice, from the signing of the North Atlantic Free Trade Agreement (NAFTA) to the invasion of Iraq and the gerrymandering of House districts across the country, few have proven as consequential as the demise of Glass-Steagall. Signed into law as the U.S.A. Banking Act of 1933, the legislation had been crucial to safeguarding the financial industry in the wake of the Great Depression. But with its repeal in 1999, the barriers separating commercial and investment banking collapsed, creating the preconditions for an economic crisis from whose shadow we have yet to emerge.
Carmen Segarra might have predicted as much. As an employee at the Federal Reserve in 2011, three years after the dissolution of Lehman Brothers, she witnessed the results of this deregulation firsthand. In her new book, “Noncompliant: A Lone Whistleblower Exposes the Giants of Wall Street,” she chronicles the recklessness of institutions like Goldman Sachs and the stunning lengths the United States government went to to accommodate them, even as they authored one of the worst crashes in our nation’s history.
“They didn’t want to hear what I had to say,” she tells Robert Scheer in the latest installment of “Scheer Intelligence.” “And so I think what we have in terms of this story is really not just a failure of the banks and the regulators, but also a failure of our prosecutors. I mean, a lot of the statutes that could be used—criminal statutes, even, that could be used to hold these executives accountable are not being used, and they have not expired; we could have prosecutors holding these people accountable.”
Segarra also explains why she decided to blow the whistle on the Fed, and what she ultimately hopes to accomplish by telling her story. “I don’t like to let the bad guys win,” she says. “I’d rather go down swinging. So for me, I saw it as an opportunity to do my civic duty and rebuild my life. … I was very lucky to be blessed by so many people who I shared the story to, especially lawyers who were so concerned about what I was reporting, who thought that the Federal Reserve was above this, who thought that the government would not fail us after the financial crisis, and who were livid.”
“Noncompliant” explores one of the darkest chapters in modern American history, but with a crook and unabashed narcissist occupying the Oval Office, its lessons are proving remarkably timely. “We live in a culture where we reward bad behavior, we worship bad behavior, and it’s something that needs to stop,” she cautions. “Changing the regulatory culture on [a] U.S. governmental level is something that’s going to take a decade, maybe two. And we need to start now, before things get worse.”
Listen to Segarra’s interview with Scheer or read a transcript of their conversation below:
Robert Scheer:Hi, I’m Robert Scheer, and this is another edition of “Scheer Intelligence,” where the intelligence comes from my guests. Today, Carmen Segarra. She’s written a book, just came out, called “Noncompliant: A Lone Whistleblower Exposes the Giants of Wall Street.” And boy, did she ever. Perhaps you remember this case; it was in 2011, two, three years into the Great Recession. There was a lot of pressure from Congress that these banks be regulated in a more serious way. As a result, Carmen Segarra, someone of considerable education, was brought in. And she was assigned to do a survey of Goldman Sachs, to go over to Goldman Sachs. And I just want to preface this, people have to understand that not only is the Federal Reserve an incredibly—the most important economic institution in the United States, but the New York Federal Reserve plays a special role being in New York. And they are basically entrusted with regulating the banks, and they are the institution that most definitely failed in that task, and helped bring about the Great Recession. Would you agree with that assessment?
Carmen Segarra:Yes, I would agree with that assessment. When I joined the Federal Reserve, as you pointed out, I was hired from outside the regulatory world, but within the legal and compliance banking world, to help fix its problems. And I was well aware of the problems that existed. And scoping the problems itself was relatively easy; I mean, within days of arriving, I had participated in meetings where you had Goldman Sachs executives, you know, lying, doublespeaking, and misrepresenting to regulatory agencies without fear of repercussions. And where I saw Federal Reserve regulators actively working to suppress and expunge from the record evidence of wrongdoing that could be used by regulatory agencies, prosecutors, and even the Federal Reserve itself to hold Goldman Sachs accountable. The question was, when I arrived, you know, are these problems fixable? And, spoiler alert: I don’t think so.
RS:Well, your book really is a compelling read on, really, what one could consider the dark culture of finance capital. Most of us know very little about it; we think it’s boring, it’s detailed and so forth. And I was thinking of another woman observer of great education and experience, who first tipped me off as a journalist when I was trying to cover the stuff about banking deregulation and so forth, and when Clinton was president and they did the basic financial deregulation. A woman named Brooksley Born, who was head of the Commodity Futures Trading Commission, and she had your kind of background, you know; a leading lawyer with the banks, and so forth. Understood this a lot better than most of the men who were powerful, including Treasury Secretary Robert Rubin; Lawrence Summers, who took over from him and went on to be the head of Harvard; Alan Greenspan–none of them really understood these collateralized debt obligations, credit default swaps; she did. She blew the whistle on it, and they basically destroyed her. She was forced out of the Clinton administration, and what have you. Did you know about Brooksley Born’s work when you got into this? Do you have any sense? I mean, this was really sort of the first major whistleblower, and she was, as you have been, basically pushed aside.
CS:Yes. I definitely knew about her. And you know, I have to say that I was, you know, just taking that historical perspective, which I think is an important point of view through which we should approach this topic. I mean, I remember when I was in law school, I was one of the very first graduating classes to graduate into a post-Glass-Steagall world. From a 50,000-foot level, I think people have a better understanding of what that means, in the sense, you know, you have all of a sudden the securities and the banking products can get together. But from a practical standpoint, from a ground-zero level, where I was at, that essentially meant two things. From a professional standpoint, we studied and were aware of the fact that there were a bunch of people on one side of the aisle, the investment products side–you know, the collateralized debt obligations that you mentioned. And then there were people who were on the banking side; we’re talking, you know, for purposes of argument, credit cards and debit cards. And that these people, they may have known about their products, but they were highly specialized; they only knew about the one or two things that they touched, and they certainly didn’t know about them and how they interacted together. And one of the things that I remember studying were not just the cases of whistleblowers, but also discussing amongst our classmates, you know, what the impact would be of all of a sudden having a class or a series of classes, graduating from law school, with people who are focusing on banking and compliance, like I was, and who are having to understand both of these products and sort of how they interact together. And what, sort of visualizing what our work life would be like, in terms of reporting to people that had an incomplete understanding of how the banking world worked. So, yes, I was definitely aware; I understood perfectly where she was coming from. And she was very much a cautionary tale for the rest of us who are lawyers. In terms of, if you find yourself in these difficult situations, you sort of game out what potentially can happen. And I certainly took it into consideration when I was gaming out whether or not to whistleblow.
RS:Well, before you get to the whistleblowing stage, I think you’re being too kind to what I personally think are people who should be considered as, or at least charged and examined often with what is criminal behavior. Because ignorance is really not a good defense; when they were called before congressional committees, these knowledgeable people admitted they really didn’t understand collateralized debt obligations and credit default swaps. And for people who are not that familiar, you mentioned Glass-Steagall. And what Glass-Steagall was, was one of the, really maybe the most important response of Franklin Delano Roosevelt’s democratic administration to the Great Depression. And how did this terrible depression happen, how were the banks so irresponsible. And they decided the key thing was to separate investment banks from commercial bank; investment banks could be high-rollers, private money, you know what you’re doing, you have knowledge; and commercial banks where you’re basically protecting the assets of ordinary people, they’re not knowledgeable, they’re trusting your expertise. And eliminating Glass-Steagall eliminated this wall between the two kinds of banking. And the company that you went to observe, Goldman Sachs, was an investment bank. And by the working of that law, they should have been allowed to go belly-up when it turned out they had a lot of these dubious credit default swaps and collateralized debt obligations. To people who don’t know, a credit default swap was a phony insurance policy pretending to cover these things, but really there’s nothing backing it up. And somehow, in order to save them, they were allowed to announce they could do commercial banking. One could argue, in some ways, the barrier was lifted to help–Citigroup was of course the other one–Citibank. And these are two banks that the government stepped in to help and create this monster. Is it not the case?
CS:Yeah, that’s absolutely the case. But there’s a couple of things that we need to keep in mind. I mean, I think that we’re all sort of educated enough to know that, you know, where there’s a will, there’s a way. And so if a system can be corrupted, people that are allowed to grab hold of power will corrupt it–insofar and only for so long as we allow those people to have the ability and the power to corrupt it. So ultimately, talking about more or less rules, or different rules, is productive only to a point. Because ultimately what we’re talking about here is the haphazard, slap on the wrist, failure to truly enforce the rules and regulations equitably across the system. And that creates the imbalances that you see, for example, in Goldman Sachs, and that you see in the system in general. One of the things that happened as a result of Glass-Steagall coming down was that a lot of the investment bankers were allowed to take over the commercial banks. And those investment bankers knew nothing about banking, and Goldman is a great example of that. I mean, when I arrived three years in after the financial crisis, what was one of the things that was very shocking to me was going into meeting after meeting with Goldman senior management and hearing them lie, doublespeak, and most shockingly of all, insist that they didn’t have to comply with the law. And that is a problem. Because a bank that doesn’t believe, or management at a bank that doesn’t believe they have to comply with the law–you bet they are not supervising their employees correctly, and they’re not incentivizing employees correctly in terms of how to do their job. So their behavior is injecting enormous risk into the system.
RS:Why should they think they should comply with the law when they got the law written and they could get it rewritten? I mean, after all, the treasury secretary, who pushed in the Clinton administration, right, to get rid of this restraint of Glass-Steagall and allow companies like Goldman Sachs to cross that line, was Robert Rubin. And he had been a top executive at Goldman Sachs. In fact, people used to refer to it as Government Sachs, that they had people all over the government, and it was a revolving door. And I want to point out that what you did, which was really unique–you had the guts to record these conversations. When you finally got to have your say before Congress, you could be backed up because you had the record. And tell us about that record. The conversations you recorded are absolutely chilling in describing an atmosphere of cynicism; you know, corruption; contempt, actually, for the political process and for restraint and regulation.
CS:Yeah. And I would sort of add that part of what the book sort of points out is that I didn’t really get my say. I mean, Congress did hold a hearing, but they did not invite me to testify. They didn’t want to hear what I had to say. And so I think what we have in terms of this story is really not just a failure of the banks and the regulators, but also a failure of our prosecutors. I mean, a lot of the statutes that could be used–criminal statutes, even, that could be used to hold these executives accountable are not being used, and they have not expired; we could have prosecutors holding these people accountable. We could have trial lawyers filing cases and holding these people accountable. Yet we can’t count on them to do it; we can’t count on the judiciary to do anything about it. I mean, when you read about what happened in my case in the book, it’s tragic, you know? It’s unbelievable.
RS:Tell us about that. Because you had a judge who was actually deep into this system who threw your case out.
...
Wall Street's corruption runs deeper than you can fathom
As an employee at the Federal Reserve in 2011, three years after the dissolution of Lehman Brothers, Carmen Segarra witnessed the results of this deregulation firsthand
By Robert Scheer / TruthdigDecember 8, 2018, 4:38 AM GMT
139
14 COMMENTS
Of the myriad policy decisions that have brought us to our current precipice, from the signing of the North Atlantic Free Trade Agreement (NAFTA) to the invasion of Iraq and the gerrymandering of House districts across the country, few have proven as consequential as the demise of Glass-Steagall. Signed into law as the U.S.A. Banking Act of 1933, the legislation had been crucial to safeguarding the financial industry in the wake of the Great Depression. But with its repeal in 1999, the barriers separating commercial and investment banking collapsed, creating the preconditions for an economic crisis from whose shadow we have yet to emerge.
Carmen Segarra might have predicted as much. As an employee at the Federal Reserve in 2011, three years after the dissolution of Lehman Brothers, she witnessed the results of this deregulation firsthand. In her new book, “Noncompliant: A Lone Whistleblower Exposes the Giants of Wall Street,” she chronicles the recklessness of institutions like Goldman Sachs and the stunning lengths the United States government went to to accommodate them, even as they authored one of the worst crashes in our nation’s history.
“They didn’t want to hear what I had to say,” she tells Robert Scheer in the latest installment of “Scheer Intelligence.” “And so I think what we have in terms of this story is really not just a failure of the banks and the regulators, but also a failure of our prosecutors. I mean, a lot of the statutes that could be used—criminal statutes, even, that could be used to hold these executives accountable are not being used, and they have not expired; we could have prosecutors holding these people accountable.”
Segarra also explains why she decided to blow the whistle on the Fed, and what she ultimately hopes to accomplish by telling her story. “I don’t like to let the bad guys win,” she says. “I’d rather go down swinging. So for me, I saw it as an opportunity to do my civic duty and rebuild my life. … I was very lucky to be blessed by so many people who I shared the story to, especially lawyers who were so concerned about what I was reporting, who thought that the Federal Reserve was above this, who thought that the government would not fail us after the financial crisis, and who were livid.”
“Noncompliant” explores one of the darkest chapters in modern American history, but with a crook and unabashed narcissist occupying the Oval Office, its lessons are proving remarkably timely. “We live in a culture where we reward bad behavior, we worship bad behavior, and it’s something that needs to stop,” she cautions. “Changing the regulatory culture on [a] U.S. governmental level is something that’s going to take a decade, maybe two. And we need to start now, before things get worse.”
Listen to Segarra’s interview with Scheer or read a transcript of their conversation below:
Robert Scheer:Hi, I’m Robert Scheer, and this is another edition of “Scheer Intelligence,” where the intelligence comes from my guests. Today, Carmen Segarra. She’s written a book, just came out, called “Noncompliant: A Lone Whistleblower Exposes the Giants of Wall Street.” And boy, did she ever. Perhaps you remember this case; it was in 2011, two, three years into the Great Recession. There was a lot of pressure from Congress that these banks be regulated in a more serious way. As a result, Carmen Segarra, someone of considerable education, was brought in. And she was assigned to do a survey of Goldman Sachs, to go over to Goldman Sachs. And I just want to preface this, people have to understand that not only is the Federal Reserve an incredibly—the most important economic institution in the United States, but the New York Federal Reserve plays a special role being in New York. And they are basically entrusted with regulating the banks, and they are the institution that most definitely failed in that task, and helped bring about the Great Recession. Would you agree with that assessment?
Carmen Segarra:Yes, I would agree with that assessment. When I joined the Federal Reserve, as you pointed out, I was hired from outside the regulatory world, but within the legal and compliance banking world, to help fix its problems. And I was well aware of the problems that existed. And scoping the problems itself was relatively easy; I mean, within days of arriving, I had participated in meetings where you had Goldman Sachs executives, you know, lying, doublespeaking, and misrepresenting to regulatory agencies without fear of repercussions. And where I saw Federal Reserve regulators actively working to suppress and expunge from the record evidence of wrongdoing that could be used by regulatory agencies, prosecutors, and even the Federal Reserve itself to hold Goldman Sachs accountable. The question was, when I arrived, you know, are these problems fixable? And, spoiler alert: I don’t think so.
RS:Well, your book really is a compelling read on, really, what one could consider the dark culture of finance capital. Most of us know very little about it; we think it’s boring, it’s detailed and so forth. And I was thinking of another woman observer of great education and experience, who first tipped me off as a journalist when I was trying to cover the stuff about banking deregulation and so forth, and when Clinton was president and they did the basic financial deregulation. A woman named Brooksley Born, who was head of the Commodity Futures Trading Commission, and she had your kind of background, you know; a leading lawyer with the banks, and so forth. Understood this a lot better than most of the men who were powerful, including Treasury Secretary Robert Rubin; Lawrence Summers, who took over from him and went on to be the head of Harvard; Alan Greenspan–none of them really understood these collateralized debt obligations, credit default swaps; she did. She blew the whistle on it, and they basically destroyed her. She was forced out of the Clinton administration, and what have you. Did you know about Brooksley Born’s work when you got into this? Do you have any sense? I mean, this was really sort of the first major whistleblower, and she was, as you have been, basically pushed aside.
CS:Yes. I definitely knew about her. And you know, I have to say that I was, you know, just taking that historical perspective, which I think is an important point of view through which we should approach this topic. I mean, I remember when I was in law school, I was one of the very first graduating classes to graduate into a post-Glass-Steagall world. From a 50,000-foot level, I think people have a better understanding of what that means, in the sense, you know, you have all of a sudden the securities and the banking products can get together. But from a practical standpoint, from a ground-zero level, where I was at, that essentially meant two things. From a professional standpoint, we studied and were aware of the fact that there were a bunch of people on one side of the aisle, the investment products side–you know, the collateralized debt obligations that you mentioned. And then there were people who were on the banking side; we’re talking, you know, for purposes of argument, credit cards and debit cards. And that these people, they may have known about their products, but they were highly specialized; they only knew about the one or two things that they touched, and they certainly didn’t know about them and how they interacted together. And one of the things that I remember studying were not just the cases of whistleblowers, but also discussing amongst our classmates, you know, what the impact would be of all of a sudden having a class or a series of classes, graduating from law school, with people who are focusing on banking and compliance, like I was, and who are having to understand both of these products and sort of how they interact together. And what, sort of visualizing what our work life would be like, in terms of reporting to people that had an incomplete understanding of how the banking world worked. So, yes, I was definitely aware; I understood perfectly where she was coming from. And she was very much a cautionary tale for the rest of us who are lawyers. In terms of, if you find yourself in these difficult situations, you sort of game out what potentially can happen. And I certainly took it into consideration when I was gaming out whether or not to whistleblow.
RS:Well, before you get to the whistleblowing stage, I think you’re being too kind to what I personally think are people who should be considered as, or at least charged and examined often with what is criminal behavior. Because ignorance is really not a good defense; when they were called before congressional committees, these knowledgeable people admitted they really didn’t understand collateralized debt obligations and credit default swaps. And for people who are not that familiar, you mentioned Glass-Steagall. And what Glass-Steagall was, was one of the, really maybe the most important response of Franklin Delano Roosevelt’s democratic administration to the Great Depression. And how did this terrible depression happen, how were the banks so irresponsible. And they decided the key thing was to separate investment banks from commercial bank; investment banks could be high-rollers, private money, you know what you’re doing, you have knowledge; and commercial banks where you’re basically protecting the assets of ordinary people, they’re not knowledgeable, they’re trusting your expertise. And eliminating Glass-Steagall eliminated this wall between the two kinds of banking. And the company that you went to observe, Goldman Sachs, was an investment bank. And by the working of that law, they should have been allowed to go belly-up when it turned out they had a lot of these dubious credit default swaps and collateralized debt obligations. To people who don’t know, a credit default swap was a phony insurance policy pretending to cover these things, but really there’s nothing backing it up. And somehow, in order to save them, they were allowed to announce they could do commercial banking. One could argue, in some ways, the barrier was lifted to help–Citigroup was of course the other one–Citibank. And these are two banks that the government stepped in to help and create this monster. Is it not the case?
CS:Yeah, that’s absolutely the case. But there’s a couple of things that we need to keep in mind. I mean, I think that we’re all sort of educated enough to know that, you know, where there’s a will, there’s a way. And so if a system can be corrupted, people that are allowed to grab hold of power will corrupt it–insofar and only for so long as we allow those people to have the ability and the power to corrupt it. So ultimately, talking about more or less rules, or different rules, is productive only to a point. Because ultimately what we’re talking about here is the haphazard, slap on the wrist, failure to truly enforce the rules and regulations equitably across the system. And that creates the imbalances that you see, for example, in Goldman Sachs, and that you see in the system in general. One of the things that happened as a result of Glass-Steagall coming down was that a lot of the investment bankers were allowed to take over the commercial banks. And those investment bankers knew nothing about banking, and Goldman is a great example of that. I mean, when I arrived three years in after the financial crisis, what was one of the things that was very shocking to me was going into meeting after meeting with Goldman senior management and hearing them lie, doublespeak, and most shockingly of all, insist that they didn’t have to comply with the law. And that is a problem. Because a bank that doesn’t believe, or management at a bank that doesn’t believe they have to comply with the law–you bet they are not supervising their employees correctly, and they’re not incentivizing employees correctly in terms of how to do their job. So their behavior is injecting enormous risk into the system.
RS:Why should they think they should comply with the law when they got the law written and they could get it rewritten? I mean, after all, the treasury secretary, who pushed in the Clinton administration, right, to get rid of this restraint of Glass-Steagall and allow companies like Goldman Sachs to cross that line, was Robert Rubin. And he had been a top executive at Goldman Sachs. In fact, people used to refer to it as Government Sachs, that they had people all over the government, and it was a revolving door. And I want to point out that what you did, which was really unique–you had the guts to record these conversations. When you finally got to have your say before Congress, you could be backed up because you had the record. And tell us about that record. The conversations you recorded are absolutely chilling in describing an atmosphere of cynicism; you know, corruption; contempt, actually, for the political process and for restraint and regulation.
CS:Yeah. And I would sort of add that part of what the book sort of points out is that I didn’t really get my say. I mean, Congress did hold a hearing, but they did not invite me to testify. They didn’t want to hear what I had to say. And so I think what we have in terms of this story is really not just a failure of the banks and the regulators, but also a failure of our prosecutors. I mean, a lot of the statutes that could be used–criminal statutes, even, that could be used to hold these executives accountable are not being used, and they have not expired; we could have prosecutors holding these people accountable. We could have trial lawyers filing cases and holding these people accountable. Yet we can’t count on them to do it; we can’t count on the judiciary to do anything about it. I mean, when you read about what happened in my case in the book, it’s tragic, you know? It’s unbelievable.
RS:Tell us about that. Because you had a judge who was actually deep into this system who threw your case out.
CS:The case was assigned to a judge who was friends with the attorney, I had worked with the attorney that represented the Fed. And then two days before dismissing the case, she revealed that she was married to someone who represented Goldman Sachs for a living. So, yeah, there you go. [Laughs] I mean, it’s almost impossible in terms of successfully blowing the whistle. But going back to your question with respect to the recordings and having a say, I think the question that we need to be asking ourselves is this: the Federal Reserve Bank of New York, and the Federal Reserve in general, is tasked with supervising the banks. They have recorders. They have the law on their side. New York is a one person consent state. Banks, private banks, habitually record everything that goes on inside the bank, and they do it for good reason. Because they do it to stop and prevent fraud, among employees and by anybody that walks in the door. Why is the Federal Reserve not recording these executives? Why are they not preserving evidence? I think that is the question that we need to be asking ourselves. You know, what I did was not special. What I did is what the Fed should have been doing.
RS:Well, it was special in that [Laughs]–come on! There have been a lot of witnesses to these crimes, really, and you’re the lone voice from within that system that dared to speak up. And as I said, had you not been able to document it with these tapes, you would have been just dismissed as some kind of kook. The book is called Noncompliant: A Lone Whistleblower Exposes the Giants of Wall Street.You know, what is so important is nuance and language and attitude. And the people on Wall Street can affect the protection of manners and complexity. I remember Lawrence Summers testifying in Congress on why you had to get rid of Glass-Steagall, and he said “this is very complicated.” And he said the same thing Alan Greenspan said: “These people know what they’re doing,” and so forth. It wasn’t complicated. If the Mafia did it, you’d see right through it in five minutes. Right? You were bundling a bunch of lousy deals together with some good deals, and you didn’t even know what was in there, and you sold them, and you got a phony insurance contract to back it up. And yet none of these people have been, gone to jail; very few, one or two have been prosecuted as kind of a scapegoat. But the book is a great story of an American heroine–but this is what everybody should do! [Laughs] I mean, the real issue about whistleblowers like yourself is why did it take you? Where were the other folks? How many people–yeah, go ahead.
CS:Yeah, agreed. I think that’s exactly right. You know, there’s a number of reasons why I wrote the book. First of all, because I think it’s an important contribution to the historical record. As to what is the systemic culture of corruption that exists in these regulatory agencies that are taking our taxpayer dollars and paying themselves handsome salaries to work against the American taxpayers. And then the second reason I wrote it is to incentivize people to come forward with their stories. I wasn’t the only person who wanted to blow the whistle in terms of what was going on there. My circumstances were unique, and I sort of go through it in the book, in the sense that I was very lucky, for example, that the Fed refused to even negotiate the mandated settlement that they were supposed to negotiate with me. But they refused, and that allowed me to sue. There’s a number of people who have gone through the process and have been silenced by, you know, getting a monetary offer and signing a settlement agreement. And we don’t hear about them because they are forced not to talk. What I sort of thought about was, you know, this is just a unique–you know, I didn’t ask to be in this situation, but I felt it was my civic duty. Because I do think that we need more people to really think about how in their daily lives, they can stop rewarding bad behavior. We live in a culture where we reward bad behavior, we worship bad behavior, and it’s something that needs to stop, you know. Changing the culture, the regulatory culture on the U.S. governmental level is something that’s going to take a decade, maybe two. And we need to start now, before things get worse. We are not in the best-off of situations as a country; you know, we have what seems like an economic boom, but it’s really just a debt-fueled economic boom that is going to be temporary. And it’s very tough to fix these types of cultural issues, system issues, when the hurricane of the next financial crisis hits. We need to fix it now, while we still have a semblance of peace, while we still have the sun shining. And we don’t know how much longer that’s going to be. I hope it’s long enough to fix it. I hope that people are inspired to come forward and to think about how to make a difference in their daily lives. You know, because we need to start thinking of raising children and raising adults that are incentivized in their daily lives to reward good behavior. I think that until we create a critical mass of Americans that in their daily lives refuse to reward bad behavior, we’re not going to see real systemic change.
RS:Well, we’ll see change. It might not be good change. I mean, you have Donald Trump–and I want to put some oomph behind this, that it’s bipartisan. Because one of the–you know, everybody, a lot of people I know are very upset about Donald Trump. He’s speaking to what Hillary Clinton calls the “deplorables”; but there’s a lot of people hurting out there. And if you read a study done by the Federal Reserve of St. Louis about the consequence of this economic meltdown that was engineered from places like Goldman Sachs, the human cost was incredible. I mean, people lost everything. They weren’t bailed out. There was no mortgage relief. They were not helped. The banks were bailed out. And yet no one has been held accountable, and the politicians, democrats and republicans, who supported it, have gotten off scot-free.
CS:Yeah, I think you’re absolutely right. This is not a democratic problem, this is not a republican problem. This is an American problem with worldwide impact. The U.S. dollar is a reserve currency. The world depends in large part on the American banking system to work. And for it to work, there are these rules, and these rules are there to create trust in the system and to create smooth processes in the system, so that money can be moved and the economy can continue to grow. If the world can no longer trust the American banking system because Americans cannot be trusted to regulate it, they are going to move away from the American banking system. They are going to move away from the U.S. dollar as a reserve currency. And then we are going to find ourselves in the situation that a lot of countries that are not governed by reserve currencies find themselves occasionally, from time to time, whenever they have a crisis. You know, we’re talking about countries in Latin America; we’re talking about countries in Africa; we’re talking about countries in Asia. I hope the book will inspire people to really take a look around and realize, you know, the American consumer, the American worker, is incredibly powerful. You know, these banks cannot survive without our money. We don’t have to wait for the government to keep failing us; we don’t have to wait for the judiciary to keep failing us; we don’t have to wait for lawyers to keep failing us. We choose who we work for. We choose where we keep our money. We can choose to protest. We can choose to call our pension funds and tell them, I want you to stop doing business with Goldman Sachs. It’s what we do on a daily basis. When we stand up and we say, I am not going to be banking with these people–they will listen. It’s like, they control all of these other checks and balances that were put in place in terms of the government to stop them. So now it’s up to us as a people to actually do something about this.
RS:Let me take a break. And I’ve been talking to Carmen Segarra, who is actually the lone honest person from within the banking system that I know of who really took the story of what these people were doing, and swindling the American people, and fortunately documented it with tape recording–as they document everything; if you call the bank for information, “your conversation will be recorded to make it more efficient”–well, she turned the table on that, had the record. The book is called Noncompliant: A Lone Whistleblower Exposes the Giants of Wall Street.[omission for station break] I’m not going to be able, in the time that I have here, to do justice to this book, because the devil is in the details. I want to talk about some people who did speak up. I mentioned Brooksley Born, who was this brilliant member of the Clinton administration who got pushed out for speaking up. But when the pressure came down after the Great Recession, and the banks had to be questioned, they at Goldman Sachs turned to a Columbia University finance professor, David Beim. And he did a report. He had access to everything, he did this incredible report. We only know about it because it showed up in some footnote somewhere. And by the way, I haven’t given enough credit here to the people who have helped break this story. ProPublica, who did a really terrific job on it, and the NPR show This American Life, which really did a great job. So there has been really good reporting. As you pointed out, it was absolutely shameful that Congress did not really take testimony from you; you were there as an observer–I think in a red dress, to be noticed. [Laughs]
CS:Yes. Well, you know, red is the color of martyrs.
RS:And so I want to ask you about that. Before you even went there, this guy David Beim had done a study. And William Dudley, the president of the bank, didn’t even respond. He said thank you, they looked at the–and they never responded to the criticisms in that study, which were devastating. Of how the bank was operating.
CS:Yeah, but that’s how the Federal Reserve Bank of New York operates. And that’s, curiously enough, also how Goldman Sachs operates. They say one thing and do another. If you want to know what they’re doing, just flip it, right? I mean, if they’re asking for a report, that means that they plan to do nothing about it. And you know, the book sort of walks you through the story of how they played at this game of pretending to clean up the regulatory issues. I mean, the joke really was on us, the new regulators that were brought in from the industry to actually clean up the problems that were there. None of us are there at the Fed anymore. Every single one of those people that I talk about that validated my story, they’re gone. And they are gone under different circumstances, some in good standing, some in less good standing, but the point is they’re all gone. Because the purpose of bringing us in was not really to change things, it was to ensure that they had a smoke screen and a story to feed the press, that they would print, saying that they had indeed fixed this. And there was nothing else there to see.
RS:We’re going to run out of time here, but I want to nail down one–this chain of responsibility. And I had just mentioned New York Fed president William Dudley, who I believe ran into some difficulty; he had ownership in something that they were trading with. But leaving that aside, he replaced Timothy Geithner. And when Goldman Sachs, when this whole banking thing happened, there was no more important individual in this country, in a position to observe it, than Timothy Geithner. He had been in the Clinton administration; he had worked for Robert Rubin and Lawrence Summers in the Clinton administration when they deregulated Wall Street. And he was rewarded for that deregulation, right, by being named to the most important regulatory position, to be head of the New York Fed. And Barack Obama in 2008, as the banking meltdown was happening, gave a speech at Cooper Union, April of 2008, blasting Wall Street. And then, when Hillary Clinton lost the primary, Barack Obama turned to Lawrence Summers and Timothy Geithner, and these people for advice, and he named Timothy Geithner to be his treasury secretary. The guy who at the New York Fed, where you went there to work and to try to supervise Goldman Sachs–he knew everything about this, and told us nothing, and he was rewarded by being made treasury secretary.
CS:When I’m saying, you know, we have to stop rewarding bad behavior, that’s an example of what I’m talking about. It’s like, we have a culture where we reward people for their bad behavior. And in the Fed it is a systemic problem. And it is a problem that comes from the top down. And when I was at the Fed, Ben Bernanke was head of the Fed; Bill Dudley, as you pointed out, was the head of the New York Fed; and Sarah Dahlgren was his head of supervision. This is a very small world. We’re not talking about a lot of people; the culture is top-down, and everybody there just does what these people say, because if they don’t they’re afraid they’re going to lose their jobs. So from their perspective, they have nothing to lose, because they have a bunch of workers that are going to do as they say. And they will do what is in their best corporate interests. I mean, you have Bill Dudley, who was allowed to hold on to a lot of his investments that predated his arrival at the Fed and were held at Goldman Sachs. And you know, when you have somebody who’s not forced to really work for the government–as in divesting themselves of their own conflicts and truly taking taxpayer money and doing their job–then you can’t expect a good result to come from that. Again, we rewarded bad behavior. And that’s why I think, you know, the key here is really about taking a really good look at our daily lives and seeing, who are we rewarding on a regular basis? And we need to stop rewarding that bad behavior.
RS:But I want to challenge what I think is your optimism. And in fact, you are living proof that doing the right thing can be a career-ender. I haven’t asked you, I mean, I assume you still have a good career; you’re highly talented and competent, and you were, you know, extremely well educated. But you’re not being considered to be treasury secretary or something, right? The consequences for you were quite dire, weren’t they?
...
==
https://www.alternet.org/economy/one-global-finances-biggest-doctors-warns-world-economy-about-get-very-sick
When Claudio Borio speaks, the big bankers and investors, the economics profession, and senior policymakers listen quite carefully—even if his sentiments don’t reach the shores of the popular media. Borio, the chief economist for the Bank for International Settlements (BIS), the central bankers’ central bank, recently remarked on the fragility of the global economy, and suggested that we were on the verge of a significant relapse similar to the global crash experienced 10 years ago. Among the parallels he perceives: the proliferation of “collateralized loan obligations (CLOs), which are ‘close cousins’ of the infamous instruments known as collateralized debt obligations, or CDOs, and securities backed by residential mortgages,” the prevalence of which helped to crater the credit system in 2008.
Mindful as central bankers have been about the ready availability of liquidity, they have (as I have written before) omitted to “proactively... [charging] private market participants variable risk premiums commensurate with the risk of the underlying activity they are undertaking when providing credit.” Furthermore, Borio implies that the monetary and fiscal authorities expended excessive efforts toward restoring the status quo ante, instead of directing policy toward broader job creation and income generation, which would place the economy on sounder footing when the next downturn inevitably comes. Finally, the BIS’s chief economist also publicly mooted whether additional “medicine” of the kind that we used last time will be in sufficient supply to respond adequately when the next crisis emerges.
So is Dr. Borio correct in both his diagnosis and concomitant concern about the lack of readily available cures for the prevailing illness? And are there any key omissions in his analysis that could help to mitigate the inevitable relapse that he forecasts?
Borio has a good track record in terms of forecasting economic crises. As early as 2006, he was presciently warning about the risks to the economic upturn posed “by the unwinding of financial imbalances that occasionally build up over the longer expansion phases of the economy,” in marked contrast to most experts at that time, who often sounded Pollyannaish in comparison.
To be sure, there are ample grounds for Borio’s caution. He correctly observes the revival of many of the speculative instruments that created so many problems back in 2008, even as policy officials continued to “administer... ‘powerful medicine’ to counter the effects of the crisis, with ‘unusually and persistently low interest rates.’” Paradoxically, the cure was almost as bad as the disease, given how aggressive monetary ease helped bring these instruments back from near death.
There is no question that in a world dominated by high and persistent levels of debt (particularly private debt), low interest rates helped to reduce the crushing burden for borrowers. But to extend the medical analogy, using interest rates to cure a global debt deflation is akin to using a sledgehammer during surgery, rather than a scalpel. There are diffuse outcomes for the cure. For every borrower aided by lower rates, there are savers (pensioners, et al) who have been adversely impacted by the prevailing low interest rate structure. Savers secure less income from minimal interest rates on their assets. Recall that when the government runs deficits, it is a large net payer of interest on its outstanding debt.
There are also supply-side issues: Low interest rates actually exacerbate prevailing deflationary trends, because the corresponding reduction in the cost of capital reduces the threshold to turn a profit, which in turn can induce greater supply and production. In addition, under a low interest rate environment, the cost of holding inventory is very low, which may mitigate the possibility of supply bottlenecks, but also potentially creates oversupply.
Raising or lowering interest rates to affect demand is therefore less effective than fiscal spending. Government spending directly targets demand deficiencies, and net injections of government stimulus into an economy can override the impact of interest rate manipulation.
No less an authority than former Federal Reserve Chairman Ben Bernanke has indirectly confirmed this claim. In a paper dated from 2000, then-Professor Bernanke made the claim that, in a deflationary environment (which he was discussing at that time in the context of Japan), monetary policy could be effective to the degree that it retained “fiscal components.” He fretted that as interest rates plunged close to zero in the face of rising deflationary pressures, any income derived via the interest rate channel would be dissipated. That is why he advocated having the monetary and fiscal authorities working closely in harness to ensure that deflation was beaten.
Which raises the question that Borio doesn’t really answer directly: If central banks continue to wean their respective economies off low interest rates, is it inevitable that the economy will suffer a relapse? Surely, government spending and taxation decisions (which are among the first policy levers used to deal with recessions) could offset this impact, because they more directly affect demand and, if deployed aggressively enough, can offset any negative impact derived as central banks raise rates. This would imply that Claudio Borio’s implicit concerns about the withdrawal of the “low interest rate medicine” would in and of themselves overstate the problem with said interest rates rise (as they are today).
The more germane consideration that goes to the heart of Borio’s concerns (i.e., that we have run out of policy space) is how best to address a future economic relapse. Being a central banker, it is understandable that Borio places emphasis on monetary policy. But is fiscal policy subject to the same kinds of limits? Have governments have run out of fiscal policy options as a result of the measures undertaken in 2008 and the corresponding rise in public debt levels (as much private debt was “socialized”—i.e., taken on the balance sheets of governments to pay for bailouts and the like)?
Again, let us refer back to Ben Bernanke. In a now famous 2002 speech before the National Economists Club, he argued the following:
“Under a fiat (that is, paper) money system, a government (in practice, the central bank in cooperation with other agencies) should always be able to generate increased nominal spending and inflation, even when the short-term nominal interest rate is at zero. ... The U.S. government has a technology, called a printing press (or, today, its electronic equivalent), that allows it to produce as many U.S. dollars as it wishes at essentially no cost.”
This statement has often been misinterpreted as implying that deficits don’t matter, and Bernanke himself was often savaged for his advocacy of “helicopter money.” But his NEC speech simply states the obvious: namely that in the absence of some sort of external constraint (whether a gold standard, or borrowing in a foreign currency), a government with a free-floating fiat currency always has the financial capacity to spend. However, it does face real resource constraints, which can render its activities inflationary—for example, if, as Professor Randy Wray has argued, “the economy runs up against a full employment constraint, but government stubbornly keeps spending more.” Although, as Wray notes, “The last time the US approached such a situation was in the over-full employment economy of WWII. Rather than bidding for resources against the private sector, the government adopted price controls, rationing, and patriotic savings. In that way, it kept inflation low, ran the budget deficit up to 25% of GDP, and stuffed banks and households full of safe sovereign debt.”
The point is that any policy limits that would impede our ability to respond to Borio’s feared economic relapse are largely political in nature. A necessary foundation of economic stabilization policy means that policymakers must be ready, willing and able to employ policy buffers that are large enough to do the job, and not simply operate with some preconceived notion of “financial sustainability.” At the same time, can policymakers undertake aggressive fiscal measures without re-igniting yet another bubble in the most puffed-up dimension of the economy— the figure-eight of CLOs/CDOs issued, sold and traded and the corresponding insurance products sold against them? And can they find a way to slowly let that air out of the bag without creating a full-blown discontinuity?
Beyond that, a genuinely effective policy is one that not only boosts spending if and when the economy collapses, but also expediently improves the income and employment condition of those at the very bottom of the income distribution. Historically, this hasn’t been done well. As Professor Pavlina Tcherneva has illustrated, “Only during the 1950-53 expansion did the bottom 90% capture all of the average income growth in the economy. Since then, the top 10% of households have been capturing greater and greater share of the income growth and, in the first two expansions of the 21st century, they have captured all of the income growth.”
Tcherneva’s analysis explains why the fiscal initiatives undertaken by Bush, Obama and Trump administrations, respectively, have been comparatively muted in terms of impacting the broadest swaths of the U.S. economy. Aside from the obvious morality question, growing inequality generally causes an economy to work at less than optimal efficiency, which makes sense intuitively in that it becomes increasingly difficult to grow an economy rapidly if the bulk of the gains are increasingly funneled to a smaller and smaller number of people (especially if they have the highest savings propensities).
In addition to the inefficiencies brought about by growing inequality, fiscal policy has tended to be biased toward “trickle-down economics” in which the benefits of government spending/taxation decisions “trickle down” to the population as a means of stimulating employment and income gains, as opposed to focusing directly on programs that cover “labor gaps” through direct employment programs such as the Job Guarantee (JG). The virtue of the JG, as the economist Hyman Minsky argued, is that “instead of the demand for low wage workers trickling down from the demand for the high wage workers, [policy orientation] should result in increments of demand for present high wage workers ‘bubbling up’ from the demand for low wage workers.” This can be better achieved via the JG, than, say, tax cuts.
Above all else, we need to avoid monetary machinations and central bank overreach, which simply move to restore the economy to an unsustainable status quo ante. Policymakers must also embrace fiscal initiatives that reorient policy away from demand-side trickle-down measures and toward a bottom-up approach that is based on employment and reducing inequality. Absent these considerations, Claudio Borio’s concerns will be validated: The economy’s recovery will be uneven, and the convalescence, such that it is, will be lengthy, intermittent, and maintaining many of the same pathologies that our economy displays today.
This article was produced by the Independent Media Institute.
https://www.alternet.org/theres-uncovered-beltway-story-hiding-plain-sight-trillions-dollars-play
Nomi Prins is one of the most regular of TomDispatchregulars, so I have no doubt that you’ve come to know her work well. As it happens, her striking new book, Collusion: How Central Bankers Rigged the World, a piercing look at the 2007-2008 global economic meltdown and the responses to it in the years since, has just been published. As Jeremy Scahill writes, “Prins has emerged as one of the fiercest critics of crony capitalism and its sustained attacks against poor and working people. This is the book that the financial elites don’t want you to read.” Ralph Nader adds, “Taxpayers, workers, and consumers who will suffer from another bailout, all better read this clear, concise compelling book.” And Greg Palast comments, “Scarier than Stephen King horror fiction.” For just a few days -- the offer ends this Sunday night -- you can get a signed, personalized copy of Collusion for a $100 donation to this site ($125 if you live outside the U.S.A.). Check out the details at our donation page and, while you’re at it, offer a helping hand to this website, which works hard to make Prins and so many other writers with unique perspectives on this topsy-turvy planet of ours available to you regularly. Tom]
In her new book, Collusion: How Central Bankers Rigged the World, Nomi Prins remembers how the 9/11 attacks affected her. She was, at the time, working for Goldman Sachs (which has been sending key former employees directly into top government posts ever since, most recently, of course, Steven Mnuchin as Donald Trump’s Treasury secretary). Before that, she had been working for the investment bank Lehman Brothers, which crashed and burned so dramatically, helping trigger the great financial crisis of 2007-2008. Here’s what she writes:
“We each have our stories from those days, where we were, what went through our minds, how it changed us as people, as a nation. For me, those tense moments walking up Broadway away from Wall Street, with the acrid, debris-filled smoke of the Twin Towers in the air, was a last straw. I left Goldman Sachs. Partly because life was too short. Partly out of disgust at how citizens everywhere had become collateral damage, and later hostages, to the banking system. Since then, I’ve dedicated my work to exposing the intersections of money and power and deciphering the impact of the relationships between governments and central and private bankers on the citizens of the world.”
Because 9/11 did something similar to me, and this website, TomDispatch, resulted from my own urge to decipher a puzzling post-9/11 world, I couldn’t be more sympathetic. Now, almost 17 years later, as the U.S. military pursues its unending wars across the planet, the central bankers of the same planet pursue... well, let Nomi Prins explain it to you. Tom
...
Trump and the Next Crash
Making the Fed an Instrument for Disaster
By Nomi Prins
Warning: What you are about to read is not about Russia, the 2016 election, or the latest person to depart from the White House in a storm of tweets. It’s the Beltway story hiding in plain sight with trillions of dollars in play and an economy to commandeer.
While we’ve been bombarded with a litany of scandals from the Oval Office and the Trump family, there’s a crucial institution in Washington that few in the media seem to be paying attention to, even as President Trump quietly makes it his own. More obscure than the chambers of the Supreme Court, it’s a place where he has already made substantial changes. I’m talking about the Federal Reserve.
As the central bank of the United States, the “Fed” sets the financial tone for the global economy by manipulating interest rate levels. This impacts everyone, yet very few grasp the scope of its influence.
During times of relative economic calm, the Fed is regularly forgotten. But what history shows us is that having leaders who are primed to neglect Wall Street’s misdoings often sets the scene for economic dangers to come. That’s why nominees to the Fed are so crucial.
We have entered a landmark moment: no president since Woodrow Wilson (during whose administration the Federal Reserve was established) will have appointed as many board members to the Fed as Donald Trump. His fingerprints will, in other words, not just be on Supreme Court decisions, but no less significantly Fed policy-making for years to come -- even though, like that court, it occupies a mandated position of political independence.
The president’s latest two nominees to that institution’s Board of Governors exemplify this. He has nominated Richard Clarida, a former Treasury Department official from the days of President George W. Bush who later became a strategic adviser to investment goliath Pimco, to the Fed’s second most important slot, while giving the nod to Michelle Bowman, a Kansas bank commissioner, to represent community banks on that same board.
Like many other entities in Washington, the Fed’s Board of Governors has been operating with less than a full staff. If Clarida is approved, he will join Trump-appointed Fed Chairman Jerome Powell and incoming New York Federal Reserve Bank head John C. Williams -- the New York Fed generally exists in a mind meld with Wall Street -- as part of the most powerful trio at that institution.
Not surprisingly, Wall Street has embraced Trump’s new Fed line-up because its members are so favorably disposed to loosening restrictions on financial institutions of every sort. Initially, the financial markets reflected concern that Chairman Powell might turn out to be a hawk on interest rates, meaning he’d raise them too quickly, but he’s proved to be anything but.Williams served as president of the San Francisco Fed. Under his watch, the third largest U.S. bank, Wells Fargo, created about 3.5 million fake accounts, gave its CEO a whopping raise, and copped to a $1 billion fine for bilking its customers on auto and mortgage insurance contracts.
As Trump stacks the deck in his favor, count on an economic impact that will be felt for years to come and could leave the world devastated. But rest assured, if the Fed can help Trump keep the stock market buoyant for a while by letting money stay cheap for Wall Street speculation and the dollar competitive for a trade war, it will.
History Warns Us
At a time when inequality, economic hardship, and household and personal debt levels are escalating and wages are not, why should any of this matter to the rest of us? The answer is simple enough: because the Fed sets the level of interest rates and so the cost of money. This, in turn, indirectly impacts the value of the dollar, which means everything you buy.
Since the financial crisis, the Fed has kept the cost of borrowing money for banks at near zero percent interest. That allowed those banks to borrow money to buy their own stock (as did many corporations) to inflate their value but not, of course, the value of their service to Main Street.
When money is cheap because interest rates are low or near zero, the beneficiaries are those with the most direct access to it. That means, of course, that the biggest banks, members of the Fed since its inception, get the largest chunks of fabricated money and pay the least amount of interest for it.
Although during the election campaign of 2016 Trump chastised the Fed for its cheap-money policies, he’s since evidently changed his mind (which is, of course, very Trumpian of him). That’s because he knows that the lower the cost of money is, the easier it is for major companies to borrow it. Easy money means easy speculation for Wall Street and its main corporate clients, which sooner or later will be a threat to the rest of us.
The era of trade wars, soaring stock markets, and Trump gaffes may feel like it’s gone on forever. Don’t forget, though, that there was a moment not so long ago when the same banking policies still reigning caused turmoil, ripping through the country and devouring the finances of so many. It’s worth recalling for a moment what happened during the Great Meltdown of 2008, when unrestrained mega-banks ravaged the economy before being bailed out. In the midst of the current market ecstasy, it’s an easy past to ignore. That’s why Trump’s takeover of the Fed and its impact on the financial system matters so much.
Let's recall that, on September 15, 2008, Lehman Brothers crashed. That bank, like Goldman Sachs a former employer of mine, had been around for more than 150 years. Its collapse was a key catalyst in a spiral of disaster that nearly decimated the world financial system. It wasn’t the bankruptcy that did it, however, but the massive amount of money the surviving banks had already lent Lehman to buy the toxic assets they created.
Around the same time, Merrill Lynch, a competitor of Lehman's, was sold to Bank of America for $50 billion and American International Group (AIG) received $182 billion in government assistance. JPMorgan Chase had already bought Bear Stearns, which had crashed six months earlier, utilizing a $29 billion government and Federal Reserve security blanket in the process.
In the wake of Lehman’s bankruptcy, $16 trillion in bailouts and other subsidies from the Federal Reserve and Congress were offered mostly to Wall Street’s biggest banks. That flow of money allowed them to return from the edge of financial disaster. At the same time, it fueled the stock and bond markets, as untethered from economic realities as the hot air balloon in The Wizard of Oz.
After nearly tripling since the post-financial crisis spring of 2009, last year the Dow Jones Industrial Average rose magically again by nearly 24%. Why? Because despite all of his swamp-draining campaign talk, Trump embraced the exact same bank-coddling behavior as President Obama. He advocated the Fed’s cheap-money policy and hired Steve Mnuchin, an ex-Goldman Sachs partner and Wall Street’s special friend, as his Treasury secretary. He doubled down on rewarding ongoing malfeasance and fraud by promoting the deregulation of the banks, as if Wall Street’s greed and high appetite for risk had vanished.
Impending Signs of Crisis
A quarter of the way into 2018, shadows of 2008 are already emerging. Only two months ago, the Dow logged its worst single-day point decline in history before bouncing back with vigor. In the meantime, the country whose banks caused the last crisis faces record consumer and corporate debt levels and a vulnerable geopolitical global landscape.
True, the unemployment rate is significantly lower than it was at the height of the financial crisis, but for Main Street, growth hasn’t been quite so apparent. About one in five U.S. jobs still pays a median income below the federal poverty line. Median household income is only up 5.3% since 2008 and remains well below where it was in 1998, if you adjust for inflation. Workforce participation remains nearly as low as it's ever been. Meanwhile, the top 1% of American earners saw their incomes go up by leaps and bounds since the Fed started manufacturing money -- to more than 40 times that of the bottom 90%.
Just as before the 2007-2008 financial crisis, there’s a scary level of confidence among politicians and regulators that neither the economy nor the banking sector could possibly go bust. Even the new Federal Reserve chair views the possible need for bailouts as a relic of a bygone time. As he said at his confirmation hearing, “Generally speaking I think the financial system is quite strong.” When asked if there are any U.S. banks that are still too big to fail, he responded, “I would say no to that.”
That’s a pretty decisive statement, and not strikingly different from oneoutgoing Fed Chair Janet Yellen made last year. By extension, it means that Trump’s new chairman supports laxer structures for the big banks and more cheap money, if needed, to help them. So watch out.
When a crisis hits, liquidity dies, and banks close their doors to the public. Ultimately, the same formula for crisis will surely send Wall Street executives crawling back to the government for aid and then Donald Trump will find out what financial negligence truly is.
A Time of Crisis and Financial Collusion
As signs of crisis emerge, few in Washington have delved into how we can ensure that a systemic crash does not happen again. That’s why I’ll never forget the strange message I got one day. It was in the middle of May 2015, about a year after my book, All the Presidents' Bankers, had been published, when I received an email from the Federal Reserve. Every year, the Fed, the International Monetary Fund, and the World Bank hold an annual conference where the most elite central bankers from around the globe assemble. To my shock, since I hadn't exactly written in a kindly fashion about the Fed, I was being invited to speak at the opening session about why Wall Street wasn’t helping Main Street.
Two months later, I found myself sitting in front of a room filled with central bankers from around the world, listening to Fed Chair Janet Yellen proclaim that the worst of the crisis and its causes were behind us. In response, the first thing I asked that distinguished crowd was this: “Do you want to know why big Wall Street banks aren’t helping Main Street as much as they could?” The room was silent. I paused before answering, “Because you never required them to.”
I added, “The biggest six U.S. banks have been rewarded with an endless supply of cheap money in bailouts and loans for their dangerous behavior. They have been given open access to these funds with no major consequences, and no rules on how they should utilize the Fed’s largess to them to help the real economy. Why should you expect their benevolence?”
After I returned home, I became obsessed with uncovering just how the bailouts and loans of that moment were only the tip of an iceberg, the sort of berg that had once taken down the Titanic -- how that cheap money fabricated for Wall Street had been no isolated American incident.
What my research for my new book, Collusion: How Central Bankers Rigged the World, revealed was how central bankers and massive financial institutions have worked together to manipulate global markets for the past decade. Major central banks gave themselves a blank check with which to resurrect problematic banks; purchase government, mortgage, and corporate bonds; and in some cases -- as in Japan and Switzerland -- stocks, too. They have not had to explain to the public where those funds were going or why. Instead, their policies have inflated asset bubbles, while coddling private banks and corporations under the guise of helping the real economy.
The zero-interest-rate and bond-buying central bank policies prevailing in the U.S., Europe, and Japan have been part of a coordinated effort that has plastered over potential financial instability in the largest countries and in private banks. It has, in turn, created asset bubbles that could explode into an even greater crisis the next time around.
So, today, we stand near -- how near we don’t yet know -- the edge of a dangerous financial precipice. The risks posed by the largest of the private banks still exist, only now they’re even bigger than they were in 2007-2008 and operating in an arena of even more debt. In Donald Trump’s America, what this means is that the same dangerous policies are still being promoted today. The difference now is that the president is appointing members to the Fed who will only increase the danger of those risks for years to come.
A crash could prove to be President Trump’s worst legacy. Not only is he -- and the Fed he’s helping to create -- not paying attention to the alarm bells (ignored by the last iteration of the Fed as well), but he’s ensured that none of his appointees will either. After campaigning hard against the ills of global finance in the 2016 election campaign and promising a modern era Glass-Steagall Act to separate bank deposits from the more speculative activities on Wall Street, Trump's policy reversals and appointees leave our economy more exposed than ever.
When politicians and regulators are asleep at the wheel, it’s the rest of us who will suffer sooner or later. Because of the collusion that’s gone on and continues to go on among the world’s main central banks, that problem is now an international one.
http://www.tomdispatch.com/blog/176348/tomgram%3A_nomi_prins%2C_you%2C_sir%2C_are_no_alexander_hamilton
https://www.alternet.org/economy/next-financial-crisis-will-be-worse-last-one
We’ve made it through 2017. The first-season installment of presidential Tweetville is ending where it began, on the Palm Beach, Fla., golf course of Mar-a-Lago. Though we are no longer privy to all the footage behind the big white truck, we do know that, given the doubling of its membership fees, others on the course will have higher stakes in the 2018 influence game.
The billionaire who ran on an anti-establishment platform went on a swamp-filling, deregulatory and inequality-producing tear, in the process creating the wealthiest Cabinet in modern United States history and expanding his own empire along the way. His offspring, Russia-related investigations aside, didn’t do too shabbily either. White House policy adviser Ivanka Trump’s brand opened a splashy new storein the lobby of Trump Tower in Manhattan, just in time for Christmas.
If you look at the stock and asset markets, as Donald Trump tends to do (and as Barack Obama did, too), you’d think all is fine with the world. The Dow Jones Industrial Average rose about 24 percent this year. The Dow Jones U.S. Real Estate Index rose 6.20 percent. The price of one Bitcoin rose about 1,646 percent.
On the flip side of that euphoria however, is the fact that the median wage rose just 2.4 percent and has remained effectively stagnant relative to inflation. And although the unemployment rate fell to a 17-year low of 4.1 percent, the labor force participation rate dropped to 62.7 percent, its lowest level in nearly four decades—particularly difficult for new entrants to the workforce, such as students graduating under a $1.3 trillion pile of unrepayable or very challenging student loan debt. (Not to worry though:Goldman Sachs is on that, promoting a way to profit from this debt by stuffing it into other assets and selling those off to investors, a la shades of the subprime mortgage crisis.)
Those of us living in the actual world without billionaire family pedigrees possess a healthy dose of skepticism over the “Make America Great Again” sect that believes Trump has transformed America “hugely,” for record-setting markets don’t imply economic stability, nor do 40 percent corporate tax cuts translate into 40 percent wage growth. We can march forward into 2018 carrying that knowledge with us.
But first, a recap. For the U.S. financial system, 2017 was marked by five main themes: The GOP’s “You All Just Got a Lot Richer” Corporate Tax Reduction Plan; Big Banks Still Bad; The Fed’s Minor Policy Shift; Debt; and Deregulators Appointed to Positions of Regulatory Authority.
Banks Are Still Big and Bad
The Big Six banks have paid billions of dollars in settlements for a variety of frauds committed before and since the 2007-2008 financial crisis, but that didn’t keep them from tallying up new fines in 2017. The nation’s largest bank, JPMorgan Chase, agreed to pay $53 million in fines for scamming African-American and Latino mortgage borrowers with disproportionately higher rates than for white borrowers. The Consumer Financial Protection Bureau fined Citigroup $28.8 million for not disclosing foreclosure-avoiding actions. Bank of America got fined $45 million for its foul treatment of a California couple trying to save their home.
But the Big Six bank that received the most attention in 2017, as it did in 2016, was Wells Fargo. The number of people affected by its fake-account creation scandal grew from 2 million reported in 2016 to about 3.5 million. That increase resulted in Wells Fargo expanding its associated class-action settlement to $142 million.
Wells Fargo was mired in smaller scandals, too. For instance, it charged 800,000 customers for auto insurance they didn’t need, raised mortgage rates for certain customers without properly disclosing it was going to, and made a bunch of unauthorized adjustments to people’s mortgages.
No Glass-Steagall Reinstatement, More Deregulation
The idea of reinstating the Glass-Steagall Act of 1933 featured in both the Democratic and the Republican National Committees’ platforms during the campaign season. But Trump’s treasury secretary, Steven Mnuchin, made it clear multiple times there would be no such push from the administration, arguing against doing so before senators including Elizabeth Warren and Bernie Sanders.
To emphasize his disdain for regulation and oversight, Mnuchin also pushed the Financial Stability Oversight Council, over which he presides, to vote 6 to 3 to rescindAmerican International Group’s designation as posing a potential threat to the U.S. financial system. Thus, AIG will no longer be paying penance for its role at the epicenter of the last financial crisis by filing regular risk reports anymore. Federal Reserve Chair Janet Yellen also supported the move.
In a major blow to citizen security, Richard Cordray, the Obama-appointed regulator, resigned as director of the Consumer Financial Protection Bureau in November.
Consumer Financial Protection Bureau Bashing
During his six years at the helm of the CFPB, which the Dodd-Frank Act formed in 2011, the 1,600-person regulatory entity accomplished a lot. It has provided $11.9 billion in relief to consumers for enforcement actions affecting more than 29.1 million people, handled 1.2 million consumer complaints and garnered timely responses on concerns for 97 percent of consumers.
Still, Trump appointed White House budget director Mick Mulvaney to the post that Cordray vacated. Remember: Mulvaney as a congressman wasn’t a fan of protecting consumers. “I don’t like the fact that [the] CFPB exists,” he said. “I will be perfectly honest with you.”
Over at the Office of the Comptroller of the Currency (OCC), Joseph Otting, Mnuchin’s former partner in the takeover of IndyMac and subsequent flurry of foreclosures, was confirmed to the top position. In that spot, Otting will be able to help the Trump administration dial back more post-crisis bank regulations.
The Fed and Debt Bubbles
The Federal Reserve raised rates three times this year. With trepidation that more or larger hikes would cause a market meltdown (because cheap money has lifted banks and markets over the past decade), each time the Fed acted, it did so by the smallest sliver it could—25 basis points. All told, this brings the total rate hikes of 2017 to 75 basis points. The short-term interest rate now sits in a 1.25 percent to 1.5 percent range.
As part of its rate-hike-into-strength message, the Fed forecast that the job market and economy will further improve in 2018. Trump’s appointed Fed leader, Janet Yellen’s No. 2 man, Jerome Powell, will take stewardship of the Fed in February 2018. Policywise, he will do exactly what Yellen and Ben Bernanke did before him, given that’s how all his votes went—albeit while advocating less oversight of the big banks. That’s because cheap money turbo-boosts the stock market, and quick rate hikes can harm the bond markets.
The reality is that the Fed and the administration are scared that selling too many bonds back into the capital markets will result in broader sell-offs, which could lead to another credit squeeze and possible recession, not to mention losses for the big banks exposed to those corporations.
Zombie Companies
Fueled by cheap Fed money and low rates, the amount of outstanding corporate debt has nearly doubled from pre-crisis levels of $3.4 trillion to record levels of $6.4 trillion
...
koch 1980? VP cand wanted to abolish Fed
==
Answers to All the Presidents’ Bankers Quiz #1 (of 3):
March 1, 2014
As promised, here are the answers and some background explanations to the All the Presidents' Bankers Quiz #1 with lots of factoids about the men and families in political and financial power over the past century. Test your knowledge of the past century of blood, intermarriage, protégé-mentorship and other ties connecting the White House and Wall Street, that form America's political-financial genealogy and elite power circle. You can also do Quiz #1 at: https://www.examtime.com/en-US/quizzes/553957/.
All the Presidents' Bankers by Nomi Prins is available for pre-order online now, and out April 8, 2014. For more , see: http://www.nomiprins.com/presidents-bankers
Questions: 1) d, 2) d, 3) b, 4) d, 5) d, 6) d, 7) d, 8) b, 9) a, 10) b
- Which president's father worked with which elite banker to form the prestigious Metropolitan Club in New York City?
a) Teddy Roosevelt's father and Junius Morgan
b) Calvin Coolidge's father and James Stillman
c) John F. Kennedy's father and John D. Rockefeller
d) Franklin Delano Roosevelt's father and John Pierpont Morgan
FDR's father, James A. Roosevelt and J.P. Morgan were two of the founding fathers of the Metropolitan Club in New York City, where many elite family patriarchs gathered together.
- Which banker who would later chair a Big Six bank rented one of FDR's New York City townhouses during WWI?
a) Winthrop Aldrich from the Chase Bank (now part of JPM Chase)
b) James Stillman from the National City Bank (now part of Citigroup)
c) George Baker, Sr. from the First National Bank (now part of Citigroup)
d) Thomas Lamont from the Morgan Bank (now part of JPM Chase)
While FDR served as Assistant Secretary of the Navy in Woodrow Wilson's administration during WWI, his fellow Harvard alum, Thomas Lamont rented out his NYC townhouse at 49 East 65th street from 1916-1920. The annual rental price was $8000, or about $112,000 in today's dollars. Lamont was a partner at the Morgan bank at the time and became Chairman during FDR"s last term as president.
- Which former Chase chairman shared a fascination of puddle jumper planes with which president?
a) David Rockefeller and John F. Kennedy
b) John McCloy and Dwight D. Eisenhower
c) David Rockefeller and Harry Truman
d) John McCloy and Harry Truman
John McCloy spoke of their shared love of puddle jumper planes in his Oral History. During WWII, while General Eisenhower led the Allied troops in Europe, McCloy served as the Assistant Secretary of War under Henry Stimson in the FDR administration. Brought into the Rockefeller-Chase fold by Nelson Rockefeller, he became Chairman of Chase in 1953 and steered its 1955 $7.5 million merger with Bank of Manhattan (run by J. Stewart Baker) to form Chase Manhattan.
- Which major banker from which bank worked most closely with FDR behind the scenes in Washington to pass the Glass- Steagall Act?
a) Jack Morgan (J.P. Morgan's son) from the Morgan Bank
b) James Perkins from National City Bank
c) Thomas Lamont from the Morgan Bank
d) Winthrop Aldrich from Chase
Though both Perkins and Aldrich met with FDR at the White House to discuss their support for passage of the Glass-Steagall Act, it was Winthrop Aldrich that took the most active role in supporting the strongest possible version of the Act, at the request of FDR.
- The father of which president was appointed as the first head of the Securities and Exchange Commission (the SEC) by FDR in 1934 to police the banking industry?
a) Harry Truman
b) Gerald Ford
c) Lyndon B. Johnson
d) John F. Kennedy
Joseph P. Kennedy, John F. Kennedy's father helped FDR secure the state of California which proved a cornerstone of FDR's presidential campaigns. In 1934, FDR appointed him the first president of the new securities regulatory body, the SEC. He later was appointed US Ambassador to the UK by FDR.
- Who was the first president to select a major Wall Street bank CEO as his Treasury Secretary?
a) Bill Clinton
b) George W. Bush
c) George H.W. Bush
d) Ronald Reagan
Ronald Reagan chose Donald Regan, CEO of Merrill Lynch as his first Treasury Secretary. Today, Merrill Lynch by virtue of its 2008 acquisition by Bank of America is part of the Big Six banks.
- Which president appointed his son-in-law Treasury Secretary, and which banker that would later chair a Big Six bank, was appointed Assistant Treasury Secretary as a result?
a) Warren Harding and Albert Wiggin
b) Calvin Coolidge and Charles Mitchell
c) Teddy Roosevelt and William Potter
d) Woodrow Wilson and Russell Leffingwell
Woodrow Wilson appointed his son-in-law William McAdoo as Treasury Secretary, who in turn selected his Yonkers friend and neighbor, Russell Leffingwell to be his assistant Treasury Secretary. Leffingwell later became partner and then Chairman of the Morgan Bank.
- Which President's grandfather ran a bank that ultimately became one of the Big Six banks that helped finance his campaign?
a) George W. Bush
b) George H.W. Bush
c) Ronald Reagan
d) John F. Kennedy
George Herbert Walker founded an investment bank, G.W. Walker & Co in 1900 that later employed many Bush family members and friends. It was taken over by Merill Lynch, which was subsequently taken over by Bank of America.
- Which banker briefly dated the sister of which president?
a) David Rockefeller and John F. Kennedy
b) John McCloy and John F. Kennedy
c) Gabriel Hauge and Harry Truman
d) David Rockefeller and Harry Truman
David Rockefeller met John F. Kennedy's sister, Kathleen, at her coming out party in London in 1938, while their father, Joseph Kennedy was serving as FDR's UK Ambassador. According to his memoirs, David 'enjoyed the company of' Kathleen for a brief period after that.
- The Treasury Secretary of which president recently joined a financial firm founded by a banker whose uncle was appointed one of the first Fed governors by Woodrow Wilson in 1914?
a) Ronald Reagan
b) Barack Obama
c) Bill Clinton
d) George W. Bush
Barack Obama's Treasury Secretary, Timothy Geithner, joined the private equity firm of Warburg, Pinkus after leaving his Washington post. The firm was founded by Eric Warburg, nephew of Paul Warburg, one of the original Fed architects at Jekyll Island and personally selected by Woodrow Wilson as one of its first governors. Wilson's campaign financing came from firms and families connected to Warburg.
==
http://www.truth-out.org/news/item/22953
n All the Presidents' Bankers: The Hidden Alliances That Drive American Power, Wall Street journalist (and former Goldman Sachs executive) Nomi Prins writes a painstakingly researched history of the financial industry's collusion with the White House to create a self-serving United States financial policy. Get the book directly from Truthout by clicking here.
Through thorough research and incisive writing, Nomi Prins has revealed how tightly Wall Street and White House policy have been aligned for more than a century. This is a difficult relationship to nail down, but Prins - as one reviewer noted - "followed the money." As a result, All the Presidents' Bankers is a must-read blockbuster of a book that names names and nails down the reality that US domestic and foreign policy is largely driven by the interests of economic hegemony and consolidated wealth.
Prins, a former executive on Wall Street and now an author and journalist, knew where to find the evidence - and it is startling to read the details.
In an extensive interview with Truthout, Prins discusses "the hidden alliances that drive Amercan power."
Mark Karlin: Could your book have been called Wall Street Financiers Are America's Co-Presidents?
Nomi Prins: Yes, that's a great way to describe the symbiotic relationship between the men that run the White House and those that run Wall Street. But equally, the title could have been American Presidents are Wall Street's Co-Bankers. When I set out to research this book, I specifically did not want to write another book about how bankers rule the world. Many people, myself included, have written books along that "dog wags the tail" theme. But I wanted to explore the relationships between the men that reside at the two poles of power over America, those who are elected to the White House and those that govern over its finances, and about how long, and to what extent, they operate on the same page.
What I found, is that that for the past century, mutually reinforcing relationships amongst the most powerful men in the past century were drivers of American domestic, national and foreign policy than just the government was, no matter who the president, or what the party in the Oval. I found that every president had connections of various degrees of closeness with the most influential bankers during his term. I knew these associations existed throughout the decades, but I was surprised to discover just how prevalent they were.
In addition, beyond the prevalent collaborations through the years, many of the key players, or 'operators,' as John Galbraith referred to them in his book about the 1929 crash, are related in some way. As I examined this genealogy of power in America, I found an elite "family tree," with branches of blood, intermarriage and protégé-mentorship connections that has shaped America on behalf or from the perspective of its members, and not necessarily the population as a whole.
Reading your new book, I get the feeling that the privileged few in the private sector who control most of America's money, de facto, don't really give a whit about democracy. What they are focused on is free markets for the plutocracy like a laser. Is that your perspective?
The notion of free markets, mechanisms where buyers and sellers can meet to exchange securities or various kinds of goods, in which each participant has access to the same information, is a fallacy. Transparency in trading across global financial markets is a fallacy. Not only are markets rigged by, and for, the biggest players, so is the entire political-financial system.
The connection between democracy and free markets is interesting though. Democracy is predicated on the idea that every vote counts equally, and in the utopian perspective, the government adopts policies that benefit or adhere to the majority of those votes. In fact, it's the minority of elite families and private individuals that exercise the most control over America's policies and actions.
The myth of a free market is that every trader or participant is equal, when in fact the biggest players with access to the most information and technology are the ones that have a disproportionate advantage over the smaller players. What we have is a plutocracy of government and markets. The privileged few don't care, or need to care, about democracy any more than they would ever want to have truly "free" markets, though what they do want are markets liberated from as many regulations as possible. In practice, that leads to huge inherent risk.
All the President's Bankers begins in early 1900s. You detail the attempts to rein in Wall Street, which the financial industry inevitably reverse. Change only appears to occur temporarily after a huge economic setback. But in 2008, Wall Street nearly destroyed the economy and got a taxpayer bailout. Is the hidden alliance that drives American power, as you call it, becoming even more solidified?
The alliance between leaders in Washington and on Wall Street has undergone a series of character changes over the past century. In the early 1900s, when President Teddy Roosevelt - widely perceived as a "trustbuster" - was breaking up the monopolies in certain industries, he didn't 'bust' the banking industry because he was facing a great financial panic in 1907 and decided he needed J.P. Morgan's help to thwart it. In the 1910s, Taft and Wilson aligned with the bankers in establishing the Federal Reserve, and then Wilson and the bankers aligned in war-financing efforts during WWI. In the 1920s, Hoover, Coolidge and Harding and the bankers aligned to endorse a spirit of political isolationism at home, laissez-faire banking policy, and financial internationalism as US bankers pushed into Europe again to take advantage of their ailing former competitors' post-war weakness, with transactions that ultimately combusted during the 1929 crash and Great Depression. In the 1930s to the 1970s though, something changed. Between the Great Depression, World War II, the Cold War and into the early 1970s, bankers were more content to be careful, to support general American expansion abroad and national interest at home, and their practices were more subdued and less speculative.
By the 1970s, things changed again; bankers found that Middle-East oil was a good source of financial independence from the US government's domestic initiatives. With Chase and Citibank leading the charge, US bankers recycled "petrodollars" into Latin American loans, got into trouble and needed the Reagan-Bush government to bail them out. It did, and from that moment on and through the major 1994 and 1999 deregulation under the Clinton administration, they increased their risk-taking and divergent path from the public interest, and though associations between bankers and presidents continued, and general national and financial policy goals were the same, bankers became more globally predatorial and had less interest in helping to sustain the general good at home. The recent 2008 crisis and time since then is the culmination of that attitude, coupled with the enabling and support by presidents of both parties, of their practices and power concentration, without requiring anything from them in return to benefit the population.
You point out that most of our presidents and bankers are pretty interchangeable in terms of pedigree. How is that?
Going back a hundred years, the Roosevelt family was very wealthy. President Taft was a blue-blood New Englander whose ancestors came to America in its infancy. James Roosevelt, FDR's father, was one of the founders of the elite Metropolitan Club in Manhattan. One of its cofounders was the most powerful banker - from a combined financial, political and legacy impact - America has ever known: J.P. Morgan. FDR attended Harvard, as did Jack Morgan, J.P. Morgan's son, as well as Thomas Lamont, senior partner at Morgan, who became chairman after Jack's death. Lamont lived in FDR's home during WWI, paying an obscene amount of rent for those days, that mere mortals could not.
Take that a step further. One of FDR's 1932 election supporters was Joseph P. Kennedy, who was responsible for garnering critical votes in California by rallying the support of media mogul, William Hearst. For his help, FDR appointed Kennedy the first head of the SEC and then gave him a UK Ambassadorship post. Kennedy's son, John F., attended Harvard as did David Rockefeller, himself the product of the marriage of Winthrop Aldrich's (the Chairman of Chase from 1933-1953 and son of Nelson Aldrich, father of the Federal Reserve) daughter with John D. Rockefeller's son. JFK and David Rockefeller first met while both were studying in London in 1938, at a society coming-out party thrown for JFK's sister, Kathleen, by Joseph Kennedy. By the 1960s, JFK was president of the country and David Rockefeller, president of Chase, its most politically connected bank.
All the Presidents' Bankers is full of examples of such pedigreed-infusion through families; by blood, via intermarriages, as well as mentorships extended to a chosen few outsiders. Here, I've recounted a few of them. The point is that the fabric that has been woven from the turn of the 20th century through today, is one wound very tightly through men who comprise this "upper caste" of American society and political-financial power.
Of course, an inevitable question is this: As much as progressives admire FDR as a shining light of liberalism - while publicly chastising Wall Street - didn't he actually work with them to prevent the United States from becoming communist, which is what they feared could happen in the depression?
FDR was no exception in the field of presidential-banking relationships; indeed he was born into them. During his terms in office, he had frequent correspondence and personal contact with Jack Morgan, Thomas Lamont and Russell Leffingwell, all of whom were senior partners at, and ran, the Morgan Bank (now part of JPM Chase) at various times, Winthrop Aldrich who ran Chase, and W. Randolph Burgess who was a former NY Fed official and vice chairman of National City Bank (now Citigroup). FDR was very strong-willed and politically savvy enough to use these friends to help promote his agenda, and unafraid to piss them off and even played them against each other when it suited his purpose.
When it came to fighting communism, or promoting and pushing American-style capitalism through the globe, FDR's goals aligned with those of these elite bankers. Bankers wanted capitalism because it made them rich. FDR and the government wanted capitalism because it was intrinsic to America's political and financial identity, as both the bankers and FDR were pushing America toward greater heights as a global superpower. All these players were on the same page and supported each other during FDR's presidency.
I was reading a book by Stephen Kinzer recently in which he argued that the Dulles brothers (during the Eisenhower era) believed that the consolidation of capital in the hands of a few individuals was ideal for free-market expansion, led of course globally by the US. Hasn't their goal (as secretary of state and head of the CIA at the time) been achieved?
Kinzer's book, The Brothers, is excellent. I highly recommend it. And absolutely, their goal, and the general goal of the men that preside over politics and finance remains the same - to retain and extend power. American presidents and their cabinet members do that on a personal, national and international basis, and so do bankers. During the time that the Dulles brothers were so influential, bankers were also close with Eisenhower, personally and functionally. Eisenhower's files in this regard are fascinating and discussed in more detail in my book.
The Eisenhower Doctrine that protected US allies (read: noncommunist countries that adopted, or were pushed into, US policies) was about the notion that the government and US military would stand ready to protect capitalism, (it was called "trade") in countries that adopted capitalism and liberalized their economies, against communism. At the time, this suited the bankers, because they utilized the power of the US military to open up branches all over the world in countries that fit this criteria. Equally, bank branches, like military bases, gave the US government a financial dimension that fortified their plans for global hegemony. Bankers and presidents needed each other and had the personal and professional connections to support that need. Confining these connections to a few players made it easier to get things done. It's not different from any major corporation; the real decision-making authority is concentrated within the heads of a few head honchos at the top of the firm, and everyone else sort of does their job with mild hopes and little chance of ascending to those top spots.
What role do the IMF and the Word Bank have in holding a stranglehold over democracy in the US and around the world?
The World Bank, in particular, was run as a joint operation between bankers and the US government since shortly after its inception. Following on from the previous question, the World Bank was not an equal opportunity lender by any means, especially during its formative years. Instead, it gave preference to noncommunist countries and better loan terms to nations that enjoyed more substantive trade relationships with the US. In 1947, President Truman chose John J. McCloy to run the World Bank. McCloy was working at a law firm connected to the Rockefeller family at the time, having just finished serving as assistant secretary of war under FDR's appointed war secretary, Henry Stimson. McCloy was the quintessential public-private office "establishment" man and later immortalized in Kai Bird's classic work, The Chairman.
McCloy had two conditions for taking the job. First, that all World Bank bonds be sold through Wall Street Banks and second, that two of his friends from Wall Street who had experience in selling bonds, be appointed his lieutenants. He got his wish. And with that, the World Bank became a pawn of the private banks, funded by the US government (and its friends).
What that means in practice, is that Wall Street can dictate where funds are raised in the private markets for World Bank initiatives, in addition to aligning with the US government regarding what countries should get aid and what is required from them in terms of privatization, austerity and other measures in return. This suited the major bankers that wanted to expand into "aid-worthy" countries - with open markets and raw natural resources. If the World Bank wants to raise funds for a country and needs private money from the capital markets as well, Wall Street has to be on board with the choice, otherwise bonds wouldn't be sold, and money wouldn't be raised. That's why, for example, during the 1980s Third World Debt Crisis, bankers pressed Reagan to provide greater federal assistance to the World Bank - they were losing money in Latin America, and if the US government and its friends could fund the World Bank to fund those countries from the public till, these nations would have more money with which to repay their private loans from the big banks. The IMF works in the same vein. There are more examples of this in the book.
How did Bill Clinton, who campaigned on a platform of lifting up the middle class, become an acolyte of Robert Rubin?
Every Democratic presidential hopeful campaigns on a platform to help the greater population, or more recently the middle class. Woodrow Wilson campaigned against the concentrated power of Wall Street, though never named names. Yet, it was Jack Morgan he called to the White House before WWI to talk war-financing strategy, and it was Paul Warburg, one of the Federal Reserve architects, that Wilson appointed as one of the Fed's first board members. FDR campaigned against the bankers but worked with them to restructure the banking system to sustain capitalism and supported their open international trade desires because it suited his own. LBJ talked of the Great Society once he was in office, but traded favors behind the scenes with the big bankers to get his policies passed and helped them in return.
So Clinton had historical company. His treasury secretary, Robert Rubin, was a link to substantive funding and the new Eastern establishment elite. Clinton correctly calculated that he needed money and Wall Street legitimacy to get elected. Without Rubin and his friends presenting Clinton through Wall Street, like a debutante, to score funding and support, all the middle-class promises in the world might not have gotten him elected.
Separately, and this is where the like-minded alliance holds, Clinton truly believed in everything Rubin believed in. As Clinton wrote in his memoirs, he got "early invaluable support" from Goldman Sachs executive Ken Brody, who introduced him to various "high-powered business people," including Rubin, whose "tightly reasoned arguments for a new economic policy," Clinton later wrote, "made a lasting impression on me." It's no accident that the swipes at Glass Steagall that George H.W. Bush and his team set in motion, became reality under Clinton. The wheels were in motion already, and Clinton and Rubin sealed the deal. I found records in the Clinton Library of full-scale jubilation in the White House at the way Rubin navigated the repeal of Glass Steagall that are documented in my book. Rubin used the same exact argument and words as Bush's treasury secretary, Nicholas Brady, to fight that deregulation battle – and they hinged on the need for America to "remain competitive", and if its banks couldn't do what European banks could in mixing financial services, then it would be a blight on the nation as a whole. Parties don't' matter. Power alliances do.
It's also no accident that Hillary Clinton has received hundreds of thousands of dollars to speak at Goldman Sachs gatherings and let them know that Wall Street was treated too harshly in the wake of the 2008 crisis.
Then you had Barack Obama campaigning on a platform of change and throwing the K Street lobbyists and bankers out of the White House. Instead, he gives them the keys to 1600 Pennsylvania Avenue. Exactly, how does a transformation like that happen?
After Washington, Clinton's treasury secretary Robert Rubin went to make millions as a vice chairman at Citigroup. Obama's treasury secretary, Tim Geithner (who had worked as assistant treasury secretary to Rubin under Clinton), went to work for a private equity fund, an enterprise whose now-deceased founder was related to Paul Warburg, one of the architects of the Federal Reserve System and donor to Woodrow Wilson's campaigns, a century ago.
Obama's response in the aftermath of this crisis has been one of coddling the big banks as they've grown bigger. His "sweeping reform," the 2010 Dodd-Frank Act, is a joke. It does nothing to constrain the power of the financial elite, because the true political-financial alliance that has allowed the big banks to become bigger, is more powerful than the actions of Congress, even if Congress had been set on doing something real, which it hasn't been. Now, America's largest banks enjoy extensive government backing, not just for deposits, but for their bad bets. The Federal Reserve is carrying a more than $4 trillion book of debt that was never raised to help the population, while it maintains near zero percent interest rates to provide the big banks cheap money.
A transformation certainly doesn't begin with a president who populates his administration with the same people whose philosophy of less rules for their friends brought us to our current situation. It won't change with Hillary Clinton for the same reasons. It wouldn't' change with Jeb Bush. Honestly, I think we're "stuck on awful" for the next decade.
You end on a pessimistic note. You again point out that the US sees the banks too-big-to-fail as essential for preserving US dominance over global financing. The Ukraine aside, in an era when armed conflict among the major financial powers appears unlikely, the federal government aids and abets Wall Street as a way of asserting American hegemony. Frederick Douglas notably said, "power concedes nothing without a demand." Yet, the paradox is that those without power appear to have little negotiating leverage in making a demand for change. Do you see anyway out of this paradox?
Author Elaine Partnow, who wrote The Quotable Woman, now in its sixth edition, 35 years ago, recently emailed me a quote from eight years ago - something I wrote in Mother Jones: "Wall Street will continue to battle for fewer restrictions under the political guise of American global competition, while Americans bear the brunt of the consequences." We know that's still true.
The other side of that coin, in light of the recent work I've done for All the Presidents' Bankers, is that this isn't just about the bankers. The presidents, Democrat or Republican, it doesn't matter, support the nation's most powerful banks and politically connected bank leaders because the most elite players in Washington truly believe that a small set of uber powerful banks and bankers, and not wide-spread financial stability or prosperity, is what gives America its global superpower edge. That's the only way to explain the deference that Congress gave JPM Chase Chairman, Jamie Dimon, when he was called to Congress to explain the Whale Trade, a huge bad bet backed by FDIC insured deposits. They asked him for economic advice.
This deference was born of social connections and partnerships and has grown into something less personal and more functional, but nonetheless ever-present all along the Washington-Wall Street Tunnel of Joint Power. Certain banks are not just too big to fail from an economic perspective, though I personally believe that had we not subsidized them, but instead subsidized individuals with failing mortgages in 2008, as opposed to providing them cheap money and other aid to use on new speculative plays, we'd all be better off right now.
Power is a shared commodity, it's shared by the most elite members of the this political-financial club who use the idea of remaining globally competitive to maintain that power. How do we get out of it? I'm afraid things have to get A LOT worse before that's even a remote possibility.
As long as America remains an ultra-capitalist construct at its top levels, we're talking a more dire crash or economic crisis after which and someone like FDR to come along, a man that could speak the language of the bankers, use them or cross them and do what was right for the population at large. We need the perspective that a stronger America is established on a strong foundation - from the ground up, not when a few at the top are strong. Aldrich touted Glass-Steagall in the front page of The New York Times and helped FDR pass it through numerous meetings in the halls of Washington because he believed that confidence in the economy was necessary at all levels of the population and this was a way to get that. Jaime Dimon would never do anything like that. But, nor would Obama or any one in the Obama administration, ever even try to push for it. They perpetuate the myth that concentrated power in the hands of a few is somehow broadly stabilizing.
A hundred years ago, Teddy Roosevelt felt the same way on the matter of banking, which is why he turned to J.P. Morgan. Bush's TS Hank Paulson, and Obama's TS Tim Geithner and Fed chairman Ben Bernanke, warned of a mega catastrophe if banks weren't bailed out in 2008. To use Naomi Klein's term, it was the financial shock doctrine, which directed even more funds to the big banks, than to the people of this country. We haven't changed much in a century. But we had a period from the 1930s to the 1960s where there was more alignment with public interest, due to regulatory rules or individual humility, than we've had since.
Now, the system is especially broken and skewed. That said, I believe that knowledge and anger is the first step towards a revolutionary-type of change. There are hundreds of millions of Americas who aren't thinking about the issues we've discussed here; millions are devouring details of what outfit Kim Kardashian wore yesterday and how her butt looked in it.
Michael Lewis' latest book on high frequency trading seems to have struck some sort of a national chord. Yet what he writes about is the mere tip of the iceberg covered in my book. He's talking about rigged markets - which have been a problem since small investors began investing with the big boys, believing they had an equal shot. I'm talking about an entirely rigged political-financial system. To that end, I hope I've been able to illuminate some dark corners of that system, as well as some with a little light in All the Presidents' Bankers.
The Panic of 1907 – also known as the 1907 Bankers' Panic or Knickerbocker Crisis[1] – was a United States financial crisis that took place when the New York Stock Exchange fell almost 50% from its peak the previous year. Panic occurred, as this was during a time of economic recession, and there were numerous runs on banks and trust companies. The 1907 panic eventually spread throughout the nation when many state and local banks and businesses entered bankruptcy. Primary causes of the run included a retraction of market liquidity by a number of New York City banks and a loss of confidence among depositors, exacerbated by unregulated side bets at bucket shops.[2] The panic was triggered by the failed attempt in October 1907 to corner the market on stock of the United Copper Company. When this bid failed, banks that had lent money to the cornering scheme suffered runs that later spread to affiliated banks and trusts, leading a week later to the downfall of the Knickerbocker Trust Company—New York City's third-largest trust. The collapse of the Knickerbocker spread fear throughout the city's trusts as regional banks withdrew reserves from New York City banks. Panic extended across the nation as vast numbers of people withdrew deposits from their regional banks.
The panic might have deepened if not for the intervention of financier J. P. Morgan,[3] who pledged large sums of his own money, and convinced other New York bankers to do the same, to shore up the banking system. At the time, the United States did not have a central bank to inject liquidity back into the market. By November, the financial contagion had largely ended, only to be replaced by a further crisis. This was due to the heavy borrowing of a large brokerage firm that used the stock of Tennessee Coal, Iron and Railroad Company (TC&I) as collateral. Collapse of TC&I's stock price was averted by an emergency takeover by Morgan'sU.S. Steel Corporation—a move approved by anti-monopolist president Theodore Roosevelt. The following year,Senator Nelson W. Aldrich, father-in-law of John D. Rockefeller, Jr., established and chaired a commission to investigate the crisis and propose future solutions, leading to the creation of the Federal Reserve System.[4][5]
Contents [hide]
1 Economic conditions
2 Panic
2.1 Cornering copper
2.2 Contagion spreads
2.3 Panic hits the trusts
2.4 J.P. Morgan
2.5 Stock exchange nears collapse
2.6 Crisis of confidence
2.7 Drama at the library
3 Aftermath
3.1 Central bank
3.2 Pujo Committee
4 In fiction
5 Timeline
6 See also
7 Notes
8 References
9 Bibliography
10 External links
==
==
http://www.booktv.org/Program/11085/After+Words+Nomi+Prins+author+of+It+Takes+a+Pillage+interviewed+by+Sen+Bernie+Sanders.aspx
http://www.booktv.org/Program/15543/After+Words+Nomi+Prins+All+the+Presidents+Bankers+The+Hidden+Alliances+that+Drive+American+Power+hosted+by+Larry+Doyle+author+of+In+Bed+with+Wall+Street.aspx
see yellow notes:
http://www.democracynow.org/2014/4/8/all_the_presidents_bankers_nomi_prins
With U.S. inequality at its highest point since 1928 and Wall Street bonuses hitting pre-2008 levels, we look at the 100-year history of secret collusion between Washington and the financial industry. In her new book, "All the Presidents’ Bankers: The Hidden Alliances that Drive American Power," financial journalist Nomi Prins explores how a small number of bankers have played critical roles in shaping a century’s worth of financial, foreign and domestic policy in the United States. Prins examines how these relationships have influenced events from the creation of the Federal Reserve, the response to the Great Depression, and the founding of the International Monetary Fund and the World Bank. Now a senior fellow at Demos, Prins is a former managing director at Bear Stearns and Goldman Sachs, and previously an analyst at Lehman Brothers and Chase Manhattan Bank.
...
NOMI PRINS: Well, actually, we were on the show a few years ago; I was talking about a novel I had written, a historical novel on the 1929 crash called Black Tuesday. And what had happened as one of the segments in that book was that six bankers had gotten together at the behest of the acting chairman of the Morgan bank, who was Thomas Lamont at the time, and they had so been afraid of losing all of the money and all of their reputations and their institutions at the time that they got together and decided to pool their own money to save the markets—stark difference from what happened more recently, which was that the Federal Reserve, Treasury Department and everyone else from the government decided to work with them to save themselves. But the impetus for the book really came from those big six bankers. We still have big six bankers today. And I looked into the relationships that they had with all of the presidents going forward and backward from that time to come up with this All the Presidents’ Bankers analysis.
AMY GOODMAN: Talk about that. Talk about who they were and the companies they represented, and go back.
NOMI PRINS: Yeah, so, in 1929, the men that sat in the room at Morgan was Tom Lamont, who was the acting chair of Morgan, as I mentioned; Charles Mitchell, who was the chairman of National City Bank, which has now grown into Citigroup; Al Wiggin, who was the head of the Chase Bank, which is now part of the Chase—JPMorgan Chase constellation; and a couple of other bankers. And they basically have morphed into some of the six banks we have today. The ones that were absent were Goldman Sachs and Bank of America, but they came in through other avenues and personal connections to bankers, from FDR and forward since that time.
And what I did was I went backwards from the crash in 1929 and noticed that J.P. Morgan, who is arguably—not even arguably, who is the most powerful banker this country has ever known and the most powerful political, financial actor—he died a hundred years ago, but his legacy, his family and what he created and the constellation of relationships between him and, at the time, Teddy Roosevelt, as far back as 1907, through Jamie Dimon’s relationship with Obama more recently, has been a very apparent apparatus in the connection of politics and finance, which I believe has no separation line.
AARON MATÉ: Well, on that absent separation line, talk about the creation of the Federal Reserve.
NOMI PRINS: So, this panic in 1907 happened. Teddy Roosevelt, who historically we know as the great trust buster, didn’t bust banks—busted a lot of other companies, a lot of other industries, not banks. And the reason for that was he truly believed—and he says this in documents and memoirs that I looked through—he truly believed that J.P. Morgan, the man, and his bank and his friends could save New York and the country from a greater catastrophe after the panic of 1907. And J.P. Morgan got together with a bunch of people at the Hotel Manhattan at midnight, didn’t have the president there, didn’t have the treasury secretary there, told them later what they would do. And what they would do is save their friends. And that’s what they did, with some of their own money, little bit of Treasury money, saved their friends, saved the Trust Company of America, because they had interests in that. They decided they didn’t want to really have that kind of scare again, so they continued to push for this idea of a central bank, which was the Federal Reserve.
They had help with a senator, Nelson Aldrich, who was head of the Senate Finance Committee at the time, after—a year or so after that under President Taft. Nelson Aldrich took a group of bankers in 1910 to Jeckyll Island. He almost didn’t make that meeting. He got hit by a trolley car up on Madison Avenue, was convalescing with his son, Winthrop Aldrich, who became the head of Chase later, and took a bunch of representatives from J.P. Morgan’s bank—J.P. Morgan was not there, and that’s power: you don’t go, you send your lieutenants—to Jeckyll Island for 10 days. They hunted. They shot pheasants. They did all sorts of things. But they came out also with the impetus for the Federal Reserve. On the way back, the train back to Washington, Nelson Aldrich had to present this plan. He was still convalescing. Two bankers that came from that meeting went in his place to Washington to put up the plans. Now, it wasn’t passed under Taft; it was passed under the Democratic president, Woodrow Wilson. But a lot of those same individuals were friends with Woodrow Wilson, as well, into his presidency, and in fact helped campaign and raise money for his presidency.
AMY GOODMAN: Go—
NOMI PRINS: And it was—sorry—and the Federal Reserve Act was ultimately passed in the end of 1913 under Wilson.
AMY GOODMAN: What were the most famous—or not as well known, but you uncovered them—bromances between top bankers and presidents?
NOMI PRINS: Right, so this—one of them was Tom Lamont, who, I mentioned, was around in 1929. But he started his life moving up the chain of Morgan after the panic in 1907 in things called the Pujo trials, which were in 1912, which, at the time, looked at what bankers had done to cause the panic of 1907. He was a young lawyer at the time. He had gone to Harvard with FDR. But as a young man, he was also hanging out—living in the house of FDR up on 65th Street, renting it for several years while FDR was the assistant Navy secretary under Woodrow Wilson. They chose Tom Lamont to go with Wilson to France for six weeks. Wilson was in France. It was the longest time a U.S. president was outside of U.S. soil and the first time a U.S. president was outside of U.S. soil. But the banker that was by his side was Tom Lamont. He was a Republican. He went across his party lines to come back with Woodrow Wilson to fight for the League of Nations to try to preserve peace after World War I, which was defeated.
But Tom Lamont and Woodrow Wilson developed this relationship. And their letters are crazy. They’re like—they’re like so full of gratuity and love and just, you know, "thank you for being there by my side, and I couldn’t have done it without you," because when Woodrow Wilson then got a stroke and it was difficult for him to go around the country to, after the war, fight for the League of Nations, which the Senate didn’t want to pass and ultimately did not pass, Tom Lamont took it up in his newspapers that he owned, the Saturday Review, went before—you know, backdoors in terms of the senators that he knew, and really tried to push it. And the two of them really worked very closely together and had this bromance. And, of course, Woodrow Wilson ultimately did die from complications of those strokes.
AARON MATÉ: If we look back on the Great Depression, it’s understood that Wall Street was hostile in many ways to the New Deal, but how did Wall Street work with Roosevelt, and why?
NOMI PRINS: So, one of the men, Winthrop Aldrich, who I mentioned before was the son of the founder of the Fed, one of the founders of the Fed, Senator Nelson Aldrich, was also friends with the Roosevelts. He was friends with FDR. And he also knew, from a business perspective, he wanted to outdo the Morgans. So he said, you know, Chase has some trading, some speculation, that went miles wrong in the crash of 1929, and he believed that for the stability of the economy and for his bank going forward, so he could sort of walk and chew gum at the same time—see the public interest as well as his bank’s interest—worked with FDR to pass the Glass-Steagall Act, which separated the speculative activities from the depositors that had their money entrusted to banks at the time, including at Chase. And, actually, Carter Glass, whose name is on that act, wanted a slightly weaker version of the act than Winthrop Aldrich pushed inside of Washington with the alliance of FDR. So that was a very, very different time. You cannot imagine today Jamie Dimon pushing with President Obama to separate his bank in such a way that it decreases its risk to depositors and taxpayers. It’s just unimaginable.
AMY GOODMAN: Well, talk about the relationship today. You have said that the relationships between bankers and presidents, those in power, is more dangerous today. And maybe you can use the example of JPMorgan Chase, Jamie Dimon’s relationship. I mean, it’s hard to forget him going before a Senate committee when there are so many questions, even the question of would he be criminally prosecuted, and they are on bended knee to him. And you’re just looking at senators, one by one, and though the TV corporate networks weren’t showing it, you know, the ch-ching, how many millions his bank and him were responsible for giving to these senators, Republican and Democrat.
NOMI PRINS: Well, yeah, and I actually remember being up that 4:30 or so in the morning and all night talking about Jamie Dimon bold-faced lying to those committees and then—yeah, and then turning over and saying, "Well, can you give us advice about the economy?" It was kind of ridiculous. This was after the London Whale trade, after they had lost billions in dollars, in money that should have been separated from speculation, to begin with.
So, the relationship is much more dangerous also because those big six banks today—again, slight derivations of the big six banks in 1929, but today—own 85 percent of deposits of all the commercial banks, 84 percent of assets of all the commercial banks, and control 96 percent of all of the derivatives that financial institutions that are backed by the government utilize today, and 45 percent of the world’s derivatives. Six banks control so much capital and have so much power as to the laws around that capital. And the administration—and this started in Reagan, through Bush, through Clinton, into Obama—this is not new—but the reaction of the administrations has been to allow this to happen, to allow the concentration of this capital, of this power, to do nothing in the face of the financial crisis of 2008, which I believe is still ongoing, just in a different manifestation, because this risk still exists and because these numbers are worse than they were before the crisis of 2008.
AMY GOODMAN: JFK, his relationship with the bankers?
NOMI PRINS: JFK was interesting. Of course, he wasn’t, you know, president for a long time.
AMY GOODMAN: You say he could have been president of a bank.
NOMI PRINS: I think—one of the things I look at in the book is sort of the pedigree and the social stature of a lot of the bankers and presidents, and also their connections. In the case of JFK, for example, he was in London in 1938 because his father, Joe Kennedy, who was the first appointed SEC head under FDR, because they were friends, because he helped with that campaign—met David Rockefeller in London at this gala coming-out party for JFK’s sister Kathleen. And David Rockefeller even briefly dated his sister Kathleen. So there were just so many social ties, as well.
But the other side of JFK is that his personal relationship, despite the social background, was a little more stilted. He just came off as a little more trying to do his own thing. So, even when—and because he had this long-standing relationship with David Rockefeller, they started to really diffuse. Rockefeller started saying disparaging things in public, in particular in this really interesting Life magazine article that came out in 1962, that were going against what JFK was trying to do. JFK, for example, in Latin America was trying to allow those countries to be more independent, to not have more private debt imposed upon them, which is what Rockefeller and the other bankers wanted to do at the time as a new source of making money. And this really disturbed Rockefeller, in particular, who was trying to expand the bank into those areas.
So, on the one side, they had a very strong social connection, and on the other side,JFK really tried to go about in a way to make external countries a little bit more independent financially from the United States, whereas that was a point where things started going in separate directions, and Rockefeller and Walter Wriston, who ran National City Bank at the time, really wanted to dump them with debt and to privatize and do all sorts of things that have gotten worse since then.
AARON MATÉ: So what happens since the 1970s? You have, at least for the bulk of the 20th century, banks and the government working together. Since the ’70s, though, Wall Street kind of goes rogue. So, what accounts for this shift, and how do we fix it now?
NOMI PRINS: Yeah, so, it’s a little bit—started when they found they could do a foreign policy that was separate from U.S. policy, that was an expansion of banks in a foreign capacity. And then LBJ tried to rein some of that back. He had some friends that he basically said, "You know, you guys, I know you want to do your own thing, but I have a Great Society vision coming on board, so you need to back me." So there was a little, still, quid pro quo there.
By the time the ’70s came along, with Nixon, who had less personal relationships and also ultimately took the country off the gold standard, which he did because the bankers pushed him to do it, because at this point they wanted two things. They saw that there was Middle East oil, and they could go in there and start to forge relationships and branches in the Middle East and utilize those petrodollars to recycle—it was a huge thing in the early ’70s—into Latin America and other countries. So they started operating more internationally and independently of their connections to the president.
And the minute they discovered all that money and they dumped all of that debt into the Third World, that manifested in a huge Third World debt crisis in the 1980s. And that was the first very large instance of a bailout. There was a small bailout for Penn Central, which was a railroad constellation in the '70s. But in the ’80s, under Reagan and under Bush, the idea of bailing out the banks, who had now refunneled all of this debt into Latin America, was a very epic decision, and it was one in which the bankers gave nothing back to the government. They were like, "We're going to use your money to bail us out." They were in Washington talking about the catastrophe that would happen to America if that didn’t happen. They got the government to basically push the World Bank and the IMF to work on the areas where they had the most risk and they had the most interest in retrieving it, and then in the ’90s just compiled that with the Mexican peso crisis, where Clinton also worked with Robert Rubin to save Mexican interests for Goldman and other U.S. banks, and then the repeal of Glass-Steagall in 1999. And then all of this idea of consolidation of risk and power just exponentially grew from there.
AMY GOODMAN: Nomi Prins, you talk about Goldman Sachs and that it wasn’t always as powerful as it is today.
NOMI PRINS: Yeah, Goldman Sachs almost died in 1928. Or, well, basically between 1928 and 1929, they had a trading partnership, "partnership," in which investors invested money, and the stock of that trust went up to $320-something, and then it subsequently went down to $1. And there were a lot of angry investors around the street and so forth. But a man named Sidney Weinberg, who was the chairman of Goldman at the time, who actually joined Goldman in the panic of 1907 as sort of an underling, decided that if he could befriend FDR in such a manner as to help him run his 1932 campaign, he would kind of have a seat at the table. And so, the legitimacy of Goldman with respect to FDR also allowed FDR to create the first Business Council, that Sidney Weinberg pushed in Washington to forge relationships between the business financial community and Washington and so on. Sidney Weinberg also was behind LBJ’s choice of Henry Fowler as a treasury secretary, who then joined Goldman Sachs after being a treasury secretary. And, of course, we had Henry Paulson, who did the other way—Bush picked him to be the treasury secretary, George W. Bush. And then, of course, Clinton picked Robert Rubin, coming from Goldman Sachs, to be the treasury secretary in his administration. So, but it started with Sidney Weinberg and FDR.
AMY GOODMAN: We’re going to break and then come back to this discussion. Then we’re going to be speaking with the Vermont congressman, Peter Welch. He wants to expose the budgets of the 16 intelligence agencies. When we come back, though, Nomi Prins will talk about her favorite story in the book. She’s the author of the new book, All the Presidents’ Bankers: The Hidden Alliances that Drive American Power. Stay with us.
[break]
AMY GOODMAN: In a moment, we’ll be speaking with Vermont Congressmember Peter Welch, but right now we’re continuing with Nomi Prins, the author of All the Presidents’ Bankers. She’s a former managing director at Bear Stearns and Goldman Sachs and previously an analyst at Lehman Brothers and other places. But we want to go to a clip right now of President Obama in 2009, 60 Minutes. He lashes out at what he calls the "fat cat bankers" of Wall Street.
PRESIDENT BARACK OBAMA: I did not run for office to be helping out a bunch of, you know, fat cat bankers on Wall Street. The only ones that are going to be paying out these fat bonuses are the ones that have now paid back that TARP money and aren’t using taxpayer loans.
STEVE KROFT: Do you think that’s why they paid it back so quickly?
PRESIDENT BARACK OBAMA: I think, in some cases, that was a motivation, which I think tells me that the people on Wall Street still don’t get it. They don’t get it. They’re still puzzled: Why is it that people are mad at the banks? Well, let’s see. You know, you guys are drawing down $10-20 million bonuses after America went through the worst economic year that it’s gone through in decades, and you guys caused the problem, and we’ve got 10 percent unemployment—why do you think people might be a little frustrated?
AARON MATÉ: That’s President Obama speaking in 2009. I’m wondering if there’s been any break in the symbiotic relationship between Wall Street and Washington that you document. Certainly with Obama’s second term, when he ran against Romney, his donations from Wall Street dropped. It was something like $16 million, went down to $6 million. So, do you see any change of course in this pattern of symbiosis that you trace in your book?
NOMI PRINS: Well, of course, Wall Street was very primary in getting him elected, to begin with. And I think also Wall Street doesn’t really particularly care who is in office, so there was a time during that campaign period where they just believed Romney had a better shot. It wasn’t so much necessarily a negative on Obama. I think they were just playing their bet, and they happened to have lost, which they usually haven’t over the many of elections. Who Wall Street backs tends to be who wins. But sometimes that backing gets a little bit split.
But in that clip, and in a lot of what Obama has said, you know, what is said publicly and what actually happens inside the private office and with respect to what’s going on with bankers, you know, shows up in the reforms. It shows up in the structures. It shows up in the minions of lobbyists and lawyers that continue to funnel money, and little chips away at even very weak but existing rules. And Obama has allowed that to happen. He’s never come out and named a name against a banker. He talks about Wall Street "fat cats" as some sort of like big, broad category. He has not named names. He has not said what Wall Street needs to done. It’s just sort of fluffy rhetoric.
AMY GOODMAN: Would he even say what he said in 2009, talking about the fat cat bankers, today?
NOMI PRINS: No. You know why? Because he believes—or he says—I shouldn’t say "believes," I don’t know—but that the 2010 Dodd-Frank Act was somehow sweeping reform, and he characterizes it as being relative to FDR’s reform when he did the Glass-Steagall Act and the New Deal and created the SEC and all sorts of things. And it simply wasn’t. As I mentioned before, banks got bigger. Their concentration of our deposits and assets and risk got bigger. Nothing was fixed by that, quote, "reform" act. And so, he would—he doesn’t need to say that now. He said it kind of in the beginning to consolidate his base, to get elected, whatever it was. But many presidents—and, actually, Democrats are a little bit more guilty of this than Republicans, because I think they feel they need to do this—from Wilson on, have always bashed the bankers in their campaign speeches, and then when it comes right down to it, most of them have been very helpful and very symbiotic with them after they have been in office. So it tends to get said to the public, and then when you look at what actually occurred, it’s a completely different matter, because they are connected.
AMY GOODMAN: Well, Nomi Prins, we want to thank you for being with us. All the Presidents’ Bankers is her book, The Hidden Alliances that Drive American Power. You can read an excerpt of that book on our website at democracynow.org. This is Democracy Now!, democracynow.org, The War and Peace Report. I’m Amy Goodman, with Aaron Maté.
bloomberg
Although it may seem shocking to watch the 112th Congress, there was a time when national leaders were swift and decisive in getting things done. In November 1910, in the space of less than two weeks, a group of government and business leaders fashioned a powerful new financial system that has survived a century, two world wars, a Great Depression and many recessions.
Of course, the Jekyll Island conference, which met that month, was dodgy even by the standards of the Gilded Age: a self-selected handful of plutocrats secretly meeting at a private resort island to draw up a new framework for the nation’s banking system. Add in the gnarly live oaks and dripping Spanish moss of coastal Georgia, and the baronial becomes baroque.
The group's original plan wasn't ratified by Congress, but one very much like it was adopted and became the basis of the Federal Reserve system that remains in place today.
At the time, the Panic of 1907 was still fresh in everyone’s mind. J.P. Morgan had resolved that panic by locking the heads of major banks in his library overnight, and strong-arming them into a deal to provide sufficient liquidity to end the runs on banks and brokerages.
No one was happy with that expediency, and in 1908 Congress passed the Aldrich-Vreeland Act, which formed the National Monetary Commission. Senator Nelson Aldrich, a Rhode Island Republican and sponsor of the act, embarked on a fact-finding mission to Europe, where he met with government ministers and bankers.
The panic had shown that the existing financial system, founded on government bonds, was brittle and ponderous. But, although voters were eager for a more robust and responsive system, there was no support at the time for a central bank either from the public or from industrialists. Both were suspicious of such government interference.
The Jekyll Island collaborators knew that public reports of their meeting would scupper their plans. The idea of senior officials from the Treasury, Congress, major banks and brokerages (along with one foreign national) slipping off to design a new world order has struck generations of Americans as distasteful at best and undemocratic at worst -- and would have been similarly received at the time. So the meeting of the minds was planned under the ruse of a gentlemen’s duck-hunting expedition.
Aldrich, an archetype of his age, was a personal friend of Morgan, and Aldrich's daughter was married to John D. Rockefeller Jr. He found in the European central banks a useful model. Although the financial system in the U.S. was functional enough to stoke the engines of a growing industrial economy, it was a classic example of the persistence of interim solutions. The models Aldrich found in Europe were more efficient and effective.
What he lacked was a way to graft those characteristics onto the American economy without retarding it. Hence the duck hunt.
Aldrich invited men he knew and trusted, or at least men of influence who he felt could work together. They included Abram Piatt Andrew, assistant secretary of the Treasury; Henry P. Davison, a business partner of Morgan's; Charles D. Norton, president of the First National Bank of New York; Benjamin Strong, another Morgan friend and the head of Bankers Trust; Frank A. Vanderlip, president of the National City Bank; and Paul M. Warburg, a partner in Kuhn, Loeb & Co. and a German citizen.
The men made their way to the island by private railway car and ferry.
In Vanderlip, Aldrich had found the tactician to design a functional American central bank. Vanderlip was born a farm boy in Aurora, Illinois, put himself through college, and worked his way up the Chicago financial ladder. He became personal assistant to Treasury Secretary Lyman Gage, and in 1898 made his mark managing loans to the government to finance the Spanish-American War.
As Bertie Charles Forbes related in his 1916 book, "Men Who Are Making America":
Vanderlip knew more about government bonds than any other man living. He knew other banks would like to be relieved of all the red tape incidental to buying and putting up bonds to cover circulation, depositing reserves to cover note issues &c. He began to dictate a circular letter to be sent broadcast to the country’s 4,000 national banks.
That was exactly the kind of perspicacity Aldrich was seeking. The collaborators spent 10 days on Jekyll Island. What emerged was an idea for something called the National Reserve Association, which would act as a central bank, issuing currency and holding member banks’ reserves. While it would handle government debt, it would be a private institution. The U.S. Treasury would have a seat on the board, but would exercise no further oversight.
The reserve association was brought to Congress as the "Aldrich plan," and it got nowhere. There was opposition in both parties, from populist William Jennings Bryan, a Nebraska Democrat, to progressive Robert La Follette, a Wisconsin Republican.
Woodrow Wilson ran for president opposed to the bankers’ club but committed to financial reform. There followed a blizzard of proposals from every part of the political spectrum. Eventually, Carter Glass, a Virginia Democrat and the chairman of the House banking committee, drafted what would become the Federal Reserve Act with the help of Robert Latham Owen, an Oklahoma Democrat. The act became law at the end of 1913.
Although the Glass-Owen bill was a compromise, the core of the Aldrich plan remained. There were many minor detail changes from the Jekyll Island accords, but the major one was a more prominent role given to the Treasury. (To this day the debate continues as to whether the Fed is truly independent, or should be.) Benjamin Strong, one of the Jekyll Island cohorts, became the first president of the New York Federal Reserve in 1914.
Today, a central bank is the global standard. All 187 members of the International Monetary Fund have them. In November 2010, Fed Chairman Ben S. Bernanke held a press conference on Jekyll Island to celebrate the centennial of the meeting. Aldrich and his colleagues would have been proud of their accomplishment -- but mortified by the publicity.
(Gregory DL Morris is a member of the editorial board of the Museum of American Finance, a Smithsonian affiliate, and a contributor to the Echoes blog. The opinions expressed are his own.)