debt collector repo
---
NO MERRI
see extraction
SEE PVTIZATION
:{:{SEE MILLER 4 MASS DEPORT TRUMP XO}:
SEE BIG DATA AI}:
SEE STUDENT DEBT
SEE DARK MONEY DONOR FUNDER
SEE HMO ~ SINGLE PAYER
SEE CFBP
SEE PAYDAY LOAN PREDATORY
PRUITT?
---
---
---
---
5 26 lever Trump’s Private Repo Men Are Hunting Immigrants
theTrump administration has quietly hired a team of scandal-plagued private debt collectors to hound immigrants slapped with new multimillion-dollar civil penalties for not leaving the country, according to documents reviewed by The Lever. All of the companies previously worked on a federal student loan debt-collection program shut down for widespread abuses.
One private collection notice obtained by The Lever assessed a $1.8 million fine on its recipient, the maximum penalty allowed under immigration law, plus another half a million in fees and interest charges, bringing the total to $2.3 million.
IFrame ContentA collection notice sent by a private debt-collection agency regarding a $1.8 million Homeland Security fine, plus another half a million in fees and interest charges.
That notice is not a one-off. According to immigration lawyers, there’s been a recent uptick in collection letters from private firms demanding immigrants pay multimillion-dollar fines, which the Department of Homeland Security began imposing last year.
As directed by a White House executive order from January, the Trump administration is using these massive new financial penalties to pressure immigrants to self-deport as part of its immigration crackdown. And to ensure immigrants ship out or pay up, the White House is enriching private contractors with a history of dubious practices, just like it has outsourced oversight of its detention centers to embattled for-profit companies like GeoGroup and CoreCivic.
“This is part and parcel with the administration’s desire to partner with the private sector to make immigration enforcement as punitive and painful as possible,” said Charles Moore, an attorney at Public Justice, a legal advocacy and defense group. “It’s very telling that they view the private market as the best way to accomplish that.”
As of last year, the administration had slapped hefty fines totaling an estimated $6 billion on over 20,000 immigrants for various infractions. The bulk of those penalties relate to overstaying a deportation removal order, for which immigrants are now being fined nearly $1,000 a day for up to five years.
Now, Homeland Security is outsourcing the management of that debt to the private collection industry, which has faced mountains of lawsuits and consumer complaints over exploitative practices such as harassing consumers who are late on credit card bills, medical payments, or auto loans.
At least four private companies inked debt-collection deals with Homeland Security as the agency began ramping up civil penalties on immigrants, according to procurement records. That included Continental Services, one of the largest collection agencies nationwide, which signed three purchasing agreements with Homeland Security last September worth a combined $1 million. A fifth company is doing debt-collection work for Homeland Security through a contract with the Treasury Department, which manages the account where payments for these fines are deposited.
Recipient
CONTINENTAL SERVICE GROUP, LLC
200 CROSS KEYS OFFICE PARK
FAIRPORT, NY 14450-3510
UNITED STATES
Congressional District: NY-25
All of these private agencies were previously part of a federal student loan debt-collection program plagued by alleged misconduct. That program was eventually shut down by the Biden administration due to widespread operational problems, massive fees on borrowers, and cost overruns for taxpayers.
Now, that same group of debt collectors has been rewarded with new Homeland Security contracts — which have fewer guardrails in place to protect debtors.
“If you’re [Homeland Security Adviser] Stephen Miller, you want the worst debt collector in America to be as aggressive and harassing as possible, because the goal is to make people miserable to get them out of the country,” said Mike Pierce, the executive director of Protect Borrowers, a legal advocacy group for consumer rights, who previously worked on student-borrowing issues at the Consumer Financial Protection Bureau.
Homeland Security and the debt collection agencies did not respond to a request for comment.
“A Total Sham”
Around March 2025, the Trump administration began levying large penalties on immigrants by relying on an obscure provision from a 1996 immigration law signed by President Bill Clinton. The statute allows the government to fine undocumented immigrants for willfully failing to depart the country — but it had never been enforced until President Donald Trump first took office.
Around 2018, after Congress blocked the total funding requested by the Trump administration to build a wall along the country’s southern border, then-White House advisor Stephen Miller devised an alternative strategy. The administration would finance the wall by leveraging its civil penalty authority to raise funds on the backs of immigrants, according to leaked emails obtained by the government watchdog group American Oversight.
:{
Once collected, those fines would be held in an “immigration enforcement account” administered by the U.S. Treasury that could then be tapped by Homeland Security as a de facto slush fund for enforcement initiatives of its choosing.
While the penalty program remained fairly limited during Trump’s first administration, it has ramped up considerably under his second term. By August of last year, over 20,000 people had been slapped with new fines.
Homeland Security recently expanded the scope of these penalties, including instituting a new $5,000 fine for illegal border crossings, as authorized by the One Big Beautiful Bill. But the most common fines target immigrants for overstaying deportation removal orders issued by immigration judges.
The government is now fining immigrants nearly $1,000 for every day they overstay a deportation order, even if those court orders were issued years ago.
The statute of limitations for such a penalty is five years, meaning the maximum fine Homeland Security can levy is $1.8 million. For many immigrants, that’s an insurmountable amount of debt, and it can’t be waived unless they leave the country.
The department also instituted new rules “streamlin[ing] the process for fining illegal aliens,” which entailed gutting the administrative hearings where they could previously protest a fine. Now, immigrants are merely entitled to written notice from the government in response to their petitions.
The rules also reduce the number of days’ notice Homeland Security must give immigrants before beginning to collect such fines, so they can contest the matter. That number is now 15 days, down from 30.
According to a lawsuit filed by a collection of immigration lawyers last year, Homeland Security may be enforcing this new penalty program illegally by targeting immigrants who have other legal avenues to remain in the country. The suit argues that the government has failed to demonstrate that many of these fines’ recipients were willfully defying deportation removal orders, per the statute.
According to the suit, in some instances, immigrants have secured permission from immigration authorities to temporarily remain in the country, but they still faced heavy fines. In other cases, immigrants received fines despite being in the process of contesting their deportation orders and pursuing other legal avenues to remain in the country, such as applying for temporary visas that may still be available to them.
“The entire process is a total sham,” said Moore, the attorney at Public Justice.
These ongoing legal challenges haven’t discouraged Homeland Security, which is now working with the Justice Department to file lawsuits against immigrants who haven’t paid their million-dollar fines. With a court order, the government can begin garnishing wages and seizing assets if payments aren’t made.
“We’ve heard of people who weren’t even notified of the fine before getting served a lawsuit by the government,” said Nicollete Glazer, an immigration lawyer based in Los Angeles. “There’s a lot of bad practices taking place.”
Weaponizing Financial Distress
In addition to bringing legal action against immigrants who haven’t paid their fines, Homeland Security is also using its massive new $190 billion immigration enforcement budget to award lucrative contracts to private contractors to collect this debt on the agency’s behalf.
Immigration lawyers say they used to only see debt notices coming directly from the government; now they’ve noticed an increase in notices sent by a host of private debt collectors. From June to September of last year, the Department inked procurement deals with Continental Services and four other debt agencies. That included a major collector, FH Cann Associates, which was awarded a contract valued at nearly $700,000. Coast Professional Inc., Central Portfolio Control Inc., and Pioneer Credit Recovery were also tapped by Homeland Security.
According to immigration lawyers, most of the collection papers they’ve seen from private contractors are for fines in the millions of dollars, accompanied by sky-high fees.
In itemized payment sheets sent by private collectors and reviewed by The Lever, such “administrative fees” make up the bulk of the financial markups, sometimes totaling $500,000 in charges for an $1.8 million fine. Language from the notices inform its recipients that authorized private collectors may collect fees as well as charge interest at an unspecified rate.
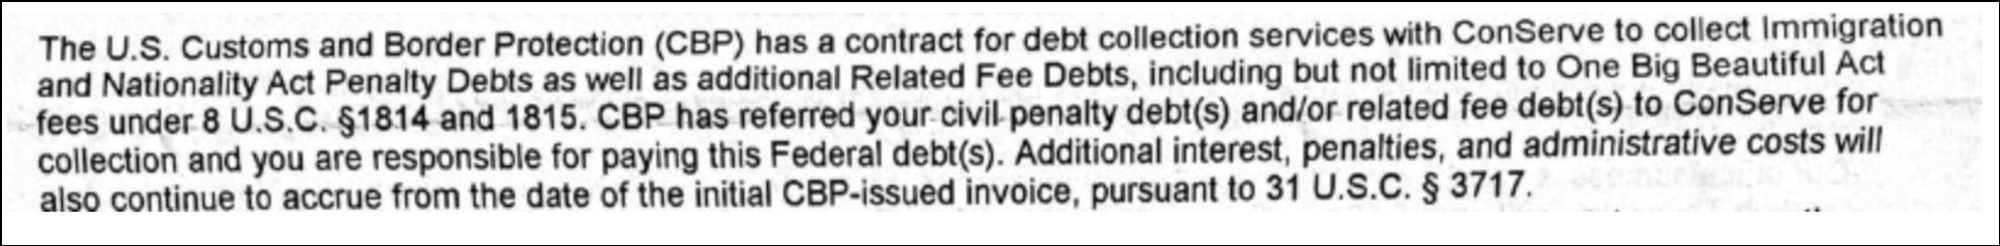 A Customs and Border Protection notice informing people that authorized private debt collectors may collect fees and charge interest on the Homeland Security fines.
“Additional interest, penalties, and administrative costs will also continue to accrue from the date of the initial CBP-issued invoice,” reads one notice sent by Customs and Border Protection, the division of Homeland Security that administers these fines.
It’s unclear whether these fees and interest charges line the contractors’ pockets or are transferred back to the government’s immigration enforcement account.
Based on the procurement records reviewed by The Lever, the private debt contractors are paid for their debt-collection services, regardless of whether they recover the fine.
A History Of Abuse
All of the debt collection firms now working under contract for Homeland Security formerly held contracts with the Department of Education to collect money from students who defaulted on government-guaranteed loans to pay for college.
The 2010 Federal Direct Loan Program created government-backed student loans, whose debt servicing was then outsourced to private firms. That public-private partnership was eventually expanded under the Obama administration to include 30 contractors. But the program quickly became a political and legal debacle, one that didn’t fade even after the Obama administration tried implementing reforms to cap exorbitantly high fees charged by student debt collectors.
In 2017, a Consumer Financial Protection Bureau issued a scathing report finding endemic problems with the Education Department’s debt-collection privatization effort, including that contractors were profiting immensely from the program despite not delivering results.
For example, investigators found that the companies’ collection cost fees totaled as much as 25 percent of students’ loan balances, even though those fees didn’t reflect the firms’ actual costs of collecting such payments. In total, the Consumer Financial Protection Bureau found that the government was reimbursing these firms $40 for every $1 they recovered from students.
The report led to a Senate inquiry that concluded the program was fueling a punitive, wasteful, and self-defeating debt cycle.
In a _{letter}_ to the Education Department, a group of senators wrote that the “Departmental process provides perverse financial incentives for private collection agencies to aggressively pursue borrowers… and encourages distressed borrowers to use less successful tools to help them deal with default.”
In 2021, the Biden administration shut down the private-sector student debt collection effort entirely. But now, some of the same contractors involved in the Education Department program have been reemployed to collect debts for Homeland Security.
:{
Most prominently, in 2017, the Obama administration sued Navient, then an Education Department loan-servicing contractor, and its subsidiary, Pioneer Credit Recovery, for failing to inform students about debt-relief options before demanding payments, among other questionable practices.
In 2024, the Consumer Financial Protection Bureau finalized a $120 million settlement in the matter banning Navient from all federal student loan servicing and putting Pioneer under the supervision of the chief consumer regulatory agency.
Now, Pioneer, which was spun off from Navient in 2025, appears to have been tapped to work on behalf of Homeland Security’s new financial-penalty effort. The firm has sent collection letters for Homeland Security fines, according to immigration lawyers, as part of an ongoing contract it has with the Treasury Department.
Alongside Pioneer, Continental Services, FH Cann Associates, Coast Professional Inc., and Central Portfolio Control Inc. were all part of the Education Department’s debt-collection privatization effort before being recently tapped directly by Homeland Security. Central Portfolio Control was a subcontractor of another debt agency, Professional Bureau of Collections of Maryland, which had secured a $13 million contract from the Education Department.
According to immigration lawyers and debt protection lawyers, the overlap may be by design.
“This kind of operation is going to be a perfect fit for [Homeland Security], which will tell [private contractors] there’s no rules or accountability,” said Glazer, the Los Angeles immigration lawyer. “And with the government guaranteeing pay, it’s a major revenue source for these collectors, even if they don’t end up collecting debt.”
According to Glazer, private collectors’ automated technology systems can churn out text messages, emails, letters, and phone calls at a vast scale to hound debtors for payments. That could be a major boon for Homeland Security, given the massive number of fines it has levied.
And now, the rapacious practices once deployed on student borrowers may be unleashed on immigrants who have even fewer legal protections.
“We’re seeing financial distress weaponized all across this administration to manipulate people’s behavior, especially now with immigration,” said Pierce at Protect Borrowers.
---
---}:
SKIP TRACER “DEPUTY” BLKWATER ERIK
MMA 4 26
A group of Trump allies have formed the Mass Deportation Coalition to encourage the administration not to back away from its deportation push. The coalition — which includes the Oversight Project’s Mike Howell, former Blackwater CEO Erik Prince, former Customs and Border Protection Acting Commissioner Mark Morgan, and conservative groups including The Heritage Foundation — released a playbook urging the White House to continue raiding work sites and deporting migrant workers despite pushback from voters. Politico, [4/1/26]
---
JACOBIN LEVER NOV?
IN February, at the start of the Trump administration’s immigration crackdown, news broke that a group of military contractors was circulating a blueprint for mass deportations, to be carried out by private contractors.
Led by Erik Prince, Donald Trump ally and founder of the notorious mercenary firm Blackwater, the group proposed (among other ideas) that Immigration and Customs Enforcement (ICE) create a “skip tracing team” that would send out private contractors to hunt down immigrants targeted for deportation, per reporting at the time by Politico.
Now, there are indications ICE is carrying out those plans.
Last month, the Lever revealed that ICE had signed a $7 million contract with defense contractor SOS International for “skip tracing services.” SOS International, also known as SOSi, has long done business with the federal government, including working with the US military in Afghanistan — and has business ties to one of the military contractors whose name was listed alongside Prince’s in the proposal.
It was the first time, per online federal procurement databases, that an ICE contract description contained the phrase “skip tracing,” a term usually associated with debt collection and bounty hunting. There was little further detail about the services SOSi would provide to Trump’s immigration enforcers.
The contract — with its eerie callback to the Prince deportation blueprint — appears not to be a fluke. Several days later, ICE signed another “skip tracing” contract, this time worth up to $33.5 million, with international debt collector Global Recovery Group LLC.
Then, on Friday, October 31, as the Intercept first reported, ICE’s Enforcement and Removal Operations bureau, the agency’s primary deportation arm, released procurement documents that mapped out new plans to create a bounty-hunting program that would deploy skip tracing methods. Though the documents are preliminary, ICE’s proposed program hews closely to the blueprint drawn up in February by Prince and his cadre of military contractors.
Under the program, private contractors will deploy “all technology systems available” to locate ICE’s targets, the documents say. Contractors would be given a list of ten thousand names at a time and be allowed to ultimately locate “up to 1,000,000” individuals, per the records.
ICE already has plenty of technology at its disposal to identify and track down immigrants, an arsenal that the agency is furtherbuilding out now that it is flush with cash. But the “skip tracing team” appears distinct in that its mandate would include sending out privately contracted bounty hunters to systematically identify immigrants’ residences and workplaces.
The bounty hunting program would include “performance-based incentives” — cash bonuses for vendors who successfully hunt down immigrants for ICE. This cash payout idea appears to be pulled directly from the Prince memo, which suggested that ICE build out a “bounty program which provides a cash reward for each illegal alien held by a state or local law enforcement officer.”
To judge from ICE’s first skip tracing contracts with SOSi and Global Recovery Group LLC, which are together worth over $40 million, the program will prove yet another gold mine for the military contractors clamoring for their cut of the Trump administration’s multibillion-dollar immigration spending blitz. And that makes sense: it was drafted by those same vendors.
From Blackwater to Bounty Hunting
The core message of Prince’s deportation plan was this: If President Donald Trump wanted to carry out his stated goals of mass deportations, he couldn’t do so alone. “The government,” the plan said, “should enlist outside assistance.”
Although Politico did not publish the complete text of the proposal, what has been made public from the document indicates that Prince was making the suggestion as part of the “special entity” 2USV, a group of defense contractors. (An LLC with the same name has been registered in Wyoming, but many details about the project remain unclear.)
The contractors include former Blackwater employees like Bill Mathews, the company’s former vice president, who pleaded guilty to violating firearms records law related to his work at the mercenary firm, as well as Richard Pere, former head of a Blackwater aviation subsidiary. Most of the Blackwater alumni have not been formally associated with the company in years. Blackwater has gone through a series of acquisitions and name changes since Prince sold the firm in 2010; its latest form is the private security conglomerate Constellis, which still operates the flagship Blackwater training center in North Carolina and is now trying to “drive strategic growth” in its border-operations work.
So far, there are no clear ties between Prince’s current business ventures — including Vectus Global, a murky security firm that is sending drones and mercenaries to the Haitian government — and the vendors now inking deals to carry out ICE’s new bounty-hunting program. But at least one other contractor involved in the initial proposal has business ties to the companies that have been tapped to carry out the plans.
Louis Gobern, one of the names listed in the initial Prince memo, is currently the president of Resilient Logistics Services & Solutions, a defense contractor that advertises its work with the Department of Homeland Security and the Department of Defense. The company names SOS International, ICE’s new skip tracing contractor, as an “industry partner,” and both companies have previously worked as subcontractors on the same Customs and Border Protection contract.
SOS International has been vying for Department of Homeland Security contracts in recent months, poaching one of ICE’s top intelligence chiefs, Andre Watson, in August. The company boasted that Watson, who helped run the ICE program targeting students for political speech, would help the contractor “expand its business and deliver capabilities to the federal and state law enforcement agencies.”
When Politico contacted Mathews, one of the former Blackwater executives, about the proposal in February, he claimed he had heard nothing from the Trump administration about moving forward with the bounty hunter program.
“There has been zero show of interest or engagement from the government, and we have no reason to believe there will be,” he said.
If ICE’s recent multimillion-dollar spending spree is any indication, that is changing.
This article was first published by the Lever, an award-winning independent investigative newsroom.
---
msnbc maddow ripped him a new one, details long hist
pretend flowers pizza delivery
268% interest on harlem restaurant?fined for screwing military
poor ppl need cars b/c gop kills mass transit
===
it remains to be seen how successful Donald Trump will ultimately be in appealing Justice Arthur Engoron's sanctions in New York State Attorney General Letitia James' civil fraud case. But for now, he has a financial lifeline while making the appeal: the $175 million bond posted by billionaire Don Hankey, who chairs Knight Specialty Insurance Company.
Since the 80-year-old Hankey posted the bond, his history in the business world has drawn a great deal of scrutiny. The New Republic's Ellie Quinlan Houghtaling, in a biting article published on April 3, stresses that Hankey — who has been called "the king of subprime loans" — has a history of "shady business practices."
The Daily Beast has reported that one of Hankey's companies, Westlake Services, was sued by the U.S. Department of Justice (DOJ) when Trump was president for illegally repossessing 70 cars. And Houghtaling points out that the Westlake debacle wasn't the first time he was "penalized by the feds."
READ MORE:**Trump lawyer threatens Alvin Bragg with 'serious' consequences if Michael Cohen testifies**
"That's all a part of the game to Hankey, who carved out his $7.4 billion fortune through those kinds of predatory practices, targeting low-income customers with high-interest auto loans," Houghtaling explains. "Hankey's Knight Specialty Insurance Company is the group that underwrote Trump's bond for his civil fraud trial, but it’s not Hankey's only investment in Trump's financial situation.
Hankey is also believed to be the largest shareholder in Axos Financial, according to MSNBC’s Lisa Rubin — a financial institution that, in 2022, refinanced more than $50 million of Trump's loans on Trump Tower and Trump National Doral Miami, according to documents filed with the Office of Government Ethics."
Houghtaling points out that Hankey discussed Trump with Forbes during an early April interview.
The billionaire told Forbes, "I'd never met Donald Trump. I'd never talked to him on the phone. I heard that he needed a loan or a bond, and this is what we do. So, we reached out, and he responded."
READ MORE:[Here's what federal law says about Trump 'threatening a sitting president': ex-federal prosecutor
*Read The New Republic's full article at this link.
===}}
an 12 23
earlier this year, Sen. Kyrsten Sinema (I-Arizona) voted with Senate Republicans for legislation to kill President Joe Biden's student debt forgiveness proposal. In the months following that vote, she was a major recipient of the student loan industry's largesse.
The bill itself, H.J. Res 45, would have blocked Biden's plan to forgive up to $20,000 in federal student loan debt per borrower, though the president promised to veto it if it reached his desk, and the Supreme Court ultimately struck down the proposal at the end of its 2023 session. The bill narrowly passed the Senatein June, with 52 votes in favor and 46 in opposition. Sinema joined forces with all Senate Republicans to give the bill the narrow majority it needed for passage. Sens. Mark Kelly (D-Arizona) and Jon Tester (D-Montana) also voted with the GOP to pass the measure.
According to the Phoenix New Times, Sinema proceeded to rake in thousands of dollars in contributions from various donors connected to student loan servicers, for-profit colleges, banks and debt collectors after her vote.
The New Times combed through Sinema's campaign finance disclosure forms on the Federal Election Commission database and learned that the Arizona senator received approximately $27,000 in PAC donations between June and September of 2023. That includes a $5,000 contribution from NelNet PAC, which is a political action committee representing the interests of the second-largest provider of federally backed loans given by private lenders. Sinema also received $5,000 from a PAC connected to private lender Sallie Mae and $5,000 from a PAC run by the board chair of a for-profit Arizona college.
Smaller donations from the industry during that time period include a $2,500 donation from debt collector Portfolio Recovery Associates, $2,500 from a Washington, DC-based trade association representing the interests of for-profit colleges, and a combined $7,000 in donations from three PACs run by banks.
Despite her fundraising activity, Arizona's senior US senator has not yet indicated if she plans to run for reelection in 2024. She currently faces opposition from Rep. Ruben Gallego (D-Arizona) and failed 2022 Arizona gubernatorial candidate Kari Lake, who campaigned as a vociferous supporter of former President Donald Trump.
:{Current polls show a virtual dead heat between the three candidates, with Gallego having a slight edge over his two opponents. :{Gallego brought in more than $3 million in donationsduring the third quarter of 2023, with an average donation amount of $28}:
https://www.alternet.org/2020/10/debt-collectors-have-made-a-fortune-this-year-now-theyre-coming-for-more/
Earlier this year, the pandemic swept across the country, killing 100,000 Americans by the spring, shuttering businesses and schools, and forcing people into their homes. It was a great time to be a debt collector.
In August, Encore Capital, the largest debt buyer in the country, announced that it had doubled its previous record for earnings in a quarter. It primarily had the CARES Act to thank: The bill delivered hundreds of billions of dollars worth of stimulus checks and bulked-up unemployment benefits to Americans, while easing pressures on them by halting foreclosures, evictions and student loan payments. There was no ban on collections of old credit card bills, Encore's specialty.
At the same time, the pandemic compelled households to cut spending. Finding themselves with enough money to settle old debts, people responded to collectors' calls and letters. Debt-buying executives couldn't help marveling at their good fortune. All this created “a perfect storm from a cash perspective," the CEO of Portfolio Recovery Associates, Encore's main competitor, told Wall Street analysts.
After its record second quarter, analysts expect Encore to blow past $200 million in profit this year and reward stockholders with 40% earnings growth compared with last year. Portfolio Recovery is set for similar growth. The share prices of both have soared off their early April lows.
Investors didn't even show much concern when, in early September, the Consumer Financial Protection Bureau sued Encore, saying that it had broken the terms of a consent agreement struck in 2015. The agency had previously charged the company with “pressuring consumers with false statements and churning out lawsuits using robo-signed court documents," as it said at the time. (In a statement, Encore said the CFPB's recent suit was unnecessary because it had fixed the alleged problems “years ago.")
In recent months, the only real bad news for debt buyers was that local courts across the country temporarily shut down. Debt collection lawsuits provide a key source of revenue for the companies, a way to extract payment from consumers, typically low-income, who don't offer it up.
But now even that hiccup is over. After a bit of a lull in the spring, Encore and other debt buyers are back at it, filing suits by the thousands every week, according to ProPublica's analysis of state court filings.
In August alone, Encore filed about 1,000 suits in Indiana and over 2,000 suits in the metro Atlanta area. Other debt buyers jumped back in as well. In Chicago, Portfolio Recovery filed over 3,000 suits in July, while LVNV, a major debt buyer privately owned by Sherman Financial Group, filed over 2,700 suits in Maryland in August. For all these companies, ProPublica found, thevolume was well above the number they'd filed before the coronavirus arrived, in January or February of this year. No national numbers on suits exist.
In statements, the companies said they have been actively working with consumers during the COVID-19 pandemic and only sue as a last resort on a small portion of accounts.
Elizabeth A. Kersey, a spokesperson for Portfolio Recovery, said the company's hardship program “allows for the suspension of collection efforts for ninety (90) days upon notification of a hardship event." The company is currently not seeking new orders to seize debtors' wages or bank account funds, she said.
Ryan Bell, an Encore executive, said, “We have consistently and proactively communicated to consumers the various relief options we've put in place in response to COVID-19, including temporarily stopping collections." The company said it had stopped seeking orders to garnish bank accounts. It is, however, seizing wages.
Sherman Financial did not respond to requests for comment.
If Congress is unable to pass any further stimulus , unemployment is likely to remain high. In that scenario, debt buying companies and the banks that sell defaulted accounts to them expect more Americans to fall behind on their credit card bills over the coming months.
Even that scenario turns out to be rosy for the debt buyers. While good times can mean that Encore collects on more debt than it expected, bad times typically bring a glut of people suffering under loans they cannot repay. The result is that Encore can scoop up the raw materials for its profit machine — defaulted accounts — more cheaply. Or as Encore CEO Ashish Masih put it to Wall Street: The company is “particularly excited about the prospects for increased supply in the future."
“The same giant debt buyers known for fighting consumer protection laws at every turn have been raking in cash during this pandemic," Sen. Elizabeth Warren, D-Mass, told ProPublica. “They are now licking their chops in anticipation of profiting even more off families who have their hours further cut or can't find a job, and can't keep up with their bills or their mortgage. This is disgraceful and reinforces the need for Congress to protect consumers and small businesses from this predatory behavior."
In recent years, Encore has bought around 2 million to 3 million U.S. accounts per year, according to public filings. Last year, on average, the company paid 8.6 cents on the dollar for each account. For a typical debt of $3,142, Encore paid $271.
To earn a profit on that investment, Encore and other debt buyers pursue debtors in near perpetuity. Encore is still collecting tens of millions of dollars each year from debts it bought in 2009 or earlier. The key to that persistence is the courts.
Since the early 2000s, debt buyers have flooded local courts nationwide with suits. The companies regularly account for more than a quarter of all debt collection cases in a given jurisdiction, according to ProPublica's review of collection filings over several states.
That disproportionate presence has been particularly apparent in recent months, as the banks themselves have mostly opted to suspend filing new suits. In normal times, Capital One files far more lawsuits than other banks, in numbers similar to those filed by Encore and Portfolio Recovery. But since March, although Capital One continued to seize pay via garnishments secured before COVID-19 struck, it has largely stopped filing new suits.
ProPublica did find one exception among the major banks that commonly file a significant number of suits: Citigroup, which resumed filing suits at its normal levels in July. The bank, for instance, filed over 200 suits in Oklahoma in August, more than it had filed there in January and February combined.
In a statement, Citi spokesperson Jennifer Bombardier said the bank has a special assistance program for customers impacted by COVID-19 and that it is not seeking to garnish the bank accounts of customers it has sued. The bank also did not sell charged-off accounts to debt buyers “for up to 120 days" in the states “most impacted by COVID-19," she said.
Encore sued Nicole Campbell of Brooklyn, New York, in July. Her first task was to figure out what to do. The suit was over $3,023.76 in debt she incurred years ago with CareCredit, a card offered by Synchrony Bank to people who need to cover medical costs, such as dentistry and eyecare. She knew she should answer the complaint by going to the courthouse, but she was wary of going there during the pandemic and wasn't even sure whether it was open.
Even attorneys have difficulty finding their way.“Courts have been returning to full operation, but there's so much confusion as to what's happening," said Susan Shin, legal director of the New Economy Project in New York City. “It's hard to know what to advise people on what to do with their case."
With help from an attorney with the New Economy Project, Campbell responded to the suit by mail. She's not sure what to expect next but said she doesn't have much time to worry about it. She cares for three boys, 5, 11 and 14, on her own and has to figure out how to get them to school on the city's part-time schedule while helping them with online lessons when they're home. She juggles this with her own job as a customer service rep: That also has a rotating, part-time schedule in order to minimize the number of people in the office.
“It's crazy to me they're filing all this during this time when there's so much going on," she said.
Such collection suits are most common among workers with income under $40,000 per year and particularly common in mostly Black neighborhoods. The suits routinely result in judgments, which in turn usually result in attempts at garnishment,according to a ProPublica analysis of Missouri court filings. Past studies have put the number of workers who have their wages garnished each year at around 4 million. In most states, plaintiffs can seize up to a quarter of a worker's take-home pay or clean out their bank account.
In recent years, when state legislatures have moved to protect more funds from garnishment, Encore has been there to oppose the measures. In 2018, a Connecticut bill proposed to automatically protect up to $1,000 in a bank account. An Encore executive, Sonia Gibson, argued against it, writing in a letter, “Since the average amount we collect through bank garnishments is typically around $700, an automatic exemption of $1,000 would leave us unable to use bank garnishments." The bill died.
Last year in California, Encore joined with other debt buyers to combat a similar bill that aimed to protect around $1,700.
“It was a really huge fight," said Ted Mermin, head of the California Low-Income Consumer Coalition and a professor at the University of California, Berkeley, School of Law. “And you've got to think, 'Why?' Who on earth thinks it's a good idea to take someone's last dollar? The only people who would do this are debt collectors who have no ongoing relationship with someone." The bill narrowly passed and became law.
In Washington state, lawmakers last year sought to protect more workers from wage garnishment. Under federal law, earnings above $217.50 in a week are eligible to be seized, a level that has remained the same since 2009 because it's tied to the $7.25 federal minimum wage. The Washington bill, which ultimately passed, aimed to tie the exemption to the state's much higher minimum wage, which this year is $13.50 an hour. In 2020, about $472.50 in weekly take-home pay would be protected. That was much too high for Encore. Gibson argued in a letter that people earning that much shouldn't be “completely exempt from garnishment."
As an alternative to automatic protections, Encore generally argues that consumers should have to file exemptions in court to demonstrate they really can't afford to have their money taken.Consumer advocates say that such exemptions, which often exist in state laws, are rarely invoked by debtors because they either don't know about them or don't understand the process.
On paper, Randall Ward would seem to be well-insulated from garnishment. He lives in the small town of Marianna, Florida, and state law protects the wages of anyone deemed the “head of household," which is defined as someone who earns more than half the household's income and has dependents. Since Ward helps care for his 20-year-old son with Down syndrome and a granddaughter, his pay from his job as a manager at a Waffle House is eligible for protection.
But when Encore, after having won a judgment against Ward the previous year, sought to garnish his wages this past February, Ward didn't understand that he qualified for the “head of household" exemption. So, starting in March, Encore began taking a quarter of Ward's take-home pay. The size of the debt, a Citibank card that had ballooned to $5,220 with interest and court costs, meant that Ward, even with what he's proud to call a “good job," was in for many lean months.
The only way to make ends meet, he said, was to cancel health insurance for himself, his son and his wife, “because I could not pay the bills if I didn't do it."
Then the virus forced his restaurant to close for several weeks and his pay stopped altogether. The family was without income as he waited for his unemployment claim to go through. When, finally, he could go back to work, the garnishments returned. Encore has said in public statements that it looks to work with consumers, especially those who've been impacted by COVID-19. Ward said that was not his experience.
“They're just ruthless about it," he said. “I would hate to see that happen to anybody."
Encore declined to comment on individual accounts.
Collection suits can have a lasting negative effect on consumers. A recent study by economists from Dartmouth's Tuck School of Business and the University of California, San Diego, focused on debtors who, after being sued, agreed to pay in order to avoid garnishment. The settlements left consumers worse off: They were more likely to fall behind on other debts or end up in foreclosure or bankruptcy, the study found. The main reason was that paying up on one debt had drained those consumers' cash buffer and that left them vulnerable to falling behind on others.
Even in good economic times, low-income consumers live on the edge, so the CARES Act aid was particularly helpful to them. According to a Federal Reserve survey, the temporary $600 boost to weekly unemployment insurance benefits actually resulted in higher pay for about 40% of those who received them. On top of that came the $1,200 stimulus checks ($2,400 for married couples) with an additional $500 for each child.
In July, the Fed found households with income under $40,000 a year had significantly more savings than normal: Whereas last year just 39% said they would have covered an unexpected $400 expense with cash, this summer, 48% said they would.
Debt collectors were a clear beneficiary of those extra funds. According to a survey by the Bureau of Labor Statistics, while most people used the stimulus payments to buy food and other essentials, about 25% used at least some of the money to pay down debts.
But Felipe Severino, a Tuck School of Business professor and one of the authors of the paper on debt collection settlements, said there may be negative long-term consequences for households who used the extra money to settle older debts. The companies say they do not charge interest on the old, charged-off debts they collect so the debts are not growing.
“I would argue it's not a very good use of their money," he said. With less of a safety net, those households are more likely to find themselves behind on their bills again.
Furthermore, he said, stimulative government aid like the CARES Act is meant to be “spent and magnify across the economy" in the near term by, for instance, leading to increased purchases at local businesses. That doesn't happen when the money goes to debt collectors.
The flood of government aid, along with the sudden contraction in spending due to COVID-19, has led to an unpredictable economy, one where unemployment has shot up without the usual tide of delinquencies, bankruptcies and foreclosures. But now, banks are predicting that tide to finally arrive in the coming months.
In July, Capital One reported a loss for the quarter despite delinquencies actually going down. The reason was the bank set aside $2.9 billion as a provision for future credit losses, a kind of safety net for the future.
Encore did not appear to need such precautions. “Our liquidity puts us in a strong position to capture the substantial purchasing opportunity, which we believe is sure to follow," Masih, the CEO, told analysts.
https://www.alternet.org/2020/10/what-happens-after-a-debt-collection-machine-grinds-to-a-halt/
Methodist hosp?
420 pro publ
One Thing the Pandemic Hasn’t Stopped: Aggressive Medical-Debt Collection
U.S. hospitals are in the spotlight for being on the frontline of fighting the pandemic. But in the shadows, debt collection operations continue, often by the same institutions treating coronavirus patients, all while unemployment and uncertainty soar.
by Alec MacGillis
| VIEW STORY |
==
no lnx
Vulture capitalists are picking us dry: Why consumer debt buyers are on the rise
The great recession laid waste to the U.S. economy. Now debt collectors are feasting on the carrion
JIM HIGHTOWER
MARCH 22, 2015
Good news, people: The "boom" is back! Yes, good times are here again, thanks to an economic boom that's being generated by (of all things) bad times.
As you might know from your own experiences, tens of millions of Americans have been hit hard, knocked down and held down in recent years by the collapse of jobs and wages. This calamity has led to a second blow for millions of the same families, who find themselves suddenly buried in piles of overdue bills for credit card charges, student loans and other consumer debt.
But the good news is that there's a bright silver lining in that dark financial cloud. Only, it's not for the indebted families, but for a booming breed of finance hucksters known as consumer debt buyers. Believe it or not, in the warped world of high finance,"There's gold in them thar hills" of bad debt, and where there's gold, there are diggers.
Whenever a corporation issues a statement declaring that it's committed to "treating consumers fairly and with respect," chances are, it's not.
After all, why say such a thing, when actually practicing it would make a statement unnecessary? Indeed, with names like Encore Capital Group and Sherman Financial, these miners of human misery buy bales of these unpaid bills from banks and other lenders, paying pennies on the dollar. Then they unleash packs of their hard-nosed, aggressive collectors on the families. If they still can't extract payment, the corporate debt profiteers turn to their meanest dog: The courts.
Debt firms routinely file thousands of lawsuits a day against financially devastated Americans. They know that most debtors can't understand the legal gibberish filed against them, can't afford a lawyer, can't take time off to go to a court hearing and can't mount an effective defense against the corporate lawyers. So, some 95 percent of these lawsuits produce default judgments against hapless borrowers -- meaning debt buyers can then confiscate the wages of borrowers or freeze their bank accounts.
This boom in vulture capitalism is disgusting -- but, worse, it's subsidized by us taxpayers! We pay for the judicial system -- the judges, courtrooms and endless rounds of hearings. Predatory debt corporations have perverted our so-called justice system into their own subsidiary for squeezing profits out of destitute debtors.
This is why New York Attorney General Eric Schneiderman has started going after these for-profit corporate debt collectors. He found that Encore, based in San Diego, filed nearly 240,000 lawsuits against debtors in a recent four-year period, using the courts as its private collection arm. Problem is, Encore's bulk filing of lawsuits against the hard-pressed borrowers are rife with errors, out-of-date payment data, fabricated credit card statements, etc. With debt buyers scooping up millions of overdue bills each year from lenders, tons of them are missing original loan documents, payment histories and other proof of debt.
Debt predators, however, scoot around this lack of facts by simply having their employees sign affidavits asserting that the level of money owed is accurate. Judges, overwhelmed by the unending flood of lawsuits filed by Encore et al, have accepted those affidavits as true, thus ruling in favor of the corporations. But Schneiderman found that -- Surprise! --affidavits were simply being rubber-stamped by company employees, with no effort to ensure the truth of the information. An employee of one large debt-buyer testified that his corporation ran an assembly-line scheme in which he signed about 2,000 affidavits a day.
This is no minor scam -- 1 in 7 adults in the U.S. is under pursuit by debt collectors. It's hard enough for struggling families to claw their way out from under the economic crash without having lying, cheating predator corporations twist the court system to pick their pockets and shut off their hope of recovery.
JIM HIGHTOWER
Jim Hightower's most recent book is "Let's Stop Beating Around the Bush." He produces a monthly newsletter, The Hightower Lowdown, and a syndicated daily radio commentary.
==
https://www.alternet.org/2019/12/how-some-alabama-county-sheriffs-force-their-inmates-into-medical-debt
no lnx
How some Alabama county sheriffs force their inmates into medical debt
Written by ProPublica December 26, 2019
This article was produced in partnership with AL.com, which is a member of the ProPublica Local Reporting Network.
In Alabama, the county in which you’re arrested could be the deciding factor in who will be financially responsible for your medical bills behind bars.
:{
}:
In Baldwin County, known for its white-sand Gulf Coast beaches and waterfront communities, the sheriff’s office ensures that inmates in the county jail do not have to pay anything more than a $15 copayment for medical care.
:{
}:
“Inmates are not billed for the full cost of any medical care either inside or outside” the jail, Sheriff Hoss Mack said in an email. “Alabama Code Title 14 assigns financial responsibility of inmates’ medical treatment to the department where they are being held.”
:{
}:
Just across the bay in Mobile County, home to one of the busiest ports in the U.S. and the eponymous city of nearly 200,000 people built around it, Sheriff Sam Cochran takes a different tack: Some of his inmates are personally on the hook for the full cost of medically necessary care they receive from outside doctors while incarcerated, even if they are awaiting trial.
The difference between the two sheriffs’ approaches demonstrates the unique power Alabama sheriffs have to set their own rules and answer only to voters.Legal experts and civil rights advocates say sheriffs like Cochran are likely violating both state law and the Eighth Amendment of the U.S. Constitution, which prohibits cruel and unusual punishment and excessive fines.
It’s not just happening in Mobile County. In multiple instances confirmed by AL.com and ProPublica, inmates have had medical bills sent to collections while they were still behind bars, damaging their credit and putting pressure on their family members to pay up to ensure the care continued.
Brandon DeLaFosse is among them. He was arrested on domestic violence, burglary and robbery charges and booked into the Mobile County Metro Jail in November 2018, three months after he underwent surgery on his inner ear. Since then, he has received bills totaling thousands of dollars for necessary follow-up appointments and tests, some of which have gone to collections while he remains behind bars.
“He keeps getting bills in the mail,” said Alicia DeLaFosse, Brandon’s mother, who has paid hundreds of dollars for care he has received while in custody. “It’s all money he owes from going back and forth to the doctor.”
Like many inmates, DeLaFosse doesn’t have significant income or access to public or private insurance in jail.
Alabama law is clear: If an “inmate develops a medical condition which requires immediate treatment at a medical-care facility outside the county jail, the department shall be financially responsible for the cost of the treatment of the inmate.”
:{
}:
But Cochran said when the jail’s doctors determine inmates need care that goes beyond what in-house medical staff and contracted outpatient providers can handle, they are often taken to private medical professionals who do not have contracts with the jail. And he allows those medical providers to bill at least some of those inmates directly.
“When that person is taken out to that private medical facility or something like that, then, yeah, they’re going to bill him for that treatment,” Cochran said during an interview in his office last month. “It’s a more than reasonable thing to do.”
Asked later about the details of Brandon DeLaFosse’s case and how the practice squares with state and federal law, Cochran provided an email written by Trey Oliver, warden of the Mobile County Metro Jail.
Oliver wrote that inmates are required to pay “when they have a follow-up procedure or visit from a surgery conducted prior to being booked.”
As for DeLaFosse, Oliver wrote, “There was a follow up visit or two and his mother agreed to pay it beforehand.”
Most jails and prisons across Alabama and the U.S. either have doctors and nurses on staff or contract with outside companies to provide medical care in their lockups. It’s not uncommon for inmates to be charged low copays — typically less than $20 — for medications and medical services.
But requiring inmates to foot the bill for their health care takes that practice to another level.
That’s “like charging them for their own food,” said John Lentine, a Birmingham criminal defense attorney and adjunct law professor at Samford University’s Cumberland School of Law and the Birmingham School of Law. “To me it’s a basic human rights kind of thing.”
Michele Deitch, a senior lecturer at the University of Texas at Austin’s School of Law and Lyndon B. Johnson School of Public Affairs, said the practice is “absolutely” unconstitutional.
“There is a constitutional obligation to provide health care that meets the serious medical needs of people who are incarcerated,” said Deitch, who co-wrote the American Bar Association’s Standards on Treatment of Prisoners. “That’s not negotiable.”
The tactic is another way in which sheriffs across Alabama are avoiding financial responsibility for inmate medical care. AL.com and ProPublica reported in September that many sheriffs in Alabama and across the country are finding ways to release inmates from jail just before they incur expensive hospital bills, a tactic known as “medical bond.”
In several recent cases, incarcerated people around the country have successfully challenged policies restricting their access to free medical care in prison.
Last year, a federal court ruled that transgender inmates in Missouri’s state prisons have a right to receive hormone therapy free of charge while incarcerated, regardless of whether they were already receiving the treatments when they were taken into custody. And this year, prisoners in Minnesota reached a settlement with the state’s Department of Corrections that requires the prison system to provide prisoners who have Hepatitis C with expensive drugs that often cure the infection.
AL.com and ProPublica attempted to contact the sheriffs of all 67 counties in Alabama via email or phone to ask whether they allow inmates to be billed for care they receive while incarcerated. Of those, 13 sheriffs and one chief deputy responded. The sheriff of Mobile County and chief deputy of Jackson County each said they allow providers to bill inmates for necessary care in certain situations. Ten sheriffs said they do not allow inmates to be billed. Two others declined to comment.
“I’m Still Getting Bills”
Days after Thanksgiving last year, Brandon DeLaFosse was arrested in Mississippi on outstanding warrants stemming from an incident earlier that month in Mobile County, Alabama.
The then-28-year-old was driven back to Mobile, where he stayed in the county jail until Feb. 28, when he was sentenced to three years in prison.
DeLaFosse’s health problems continued behind bars. Since his ear surgery last year, he has suffered from persistent ear infections and severe hearing loss.
And his bills are piling up.
In between Marlboro Lights and peanut butter-and-syrup sandwiches at her Irvington home last month, DeLaFosse’s mother, Alicia, said she spends many hours each week making calls, sending emails and conducting research to advocate on behalf of her son.
She said a steady stream of medical bills addressed to her son has arrived at her house since his arrest. Billing records show that she has spent more than $600 on his care since his arrest, and more than $1,000 in outstanding bills have gone to debt collection.
On Dec. 6, 2018, while he was in the Mobile County Metro Jail, Brandon DeLaFosse was taken to see an ear, nose and throat specialist at Providence Hospital in Mobile for a surgery follow-up visit recommended by the doctor. But first, his mother said, jail staff required her to make a payment to the doctor’s office. After the appointment, the hospital’s billing department sent a bill for $729 for tests he underwent that day to Alicia DeLaFosse’s house.
“The way the nurse at the jail explained it to me is because it was something that didn’t happen at the jail, it’s preexisting. … I had to go pay for it myself,” she said. “For the jail to allow him to go see the doctor, I had to go to the doctor’s office and pay $125 first.”
A registered nurse at the jail in Mobile noted in Brandon DeLaFosse’s medical record that his mother made a payment and that the nurse had scheduled a follow-up visit for later that month. In January 2019, a nurse practitioner at the jail wrote a note in his file stating she would request another follow-up appointment with his doctor “with the expectation that it is handled in the usual fashion with his mother arranging for payment.”
“I don’t think it’s fair. They’re responsible for my medical care, so why should it be coming out of my pockets or my family’s pockets?” Brandon DeLaFosse said in a jailhouse phone call.
Cochran, the Mobile County sheriff, said via email that he views the situation as a “legal dispute between [Brandon DeLaFosse], us and our contracted provider. I know of no complaint or claim made against us.”
“The mom agreed to pay [the] bill. Looks like she reneged,” Cochran wrote. “Otherwise if it would have been medically necessary our contracted folks would have handled.”
Alicia DeLaFosse said she “didn’t renege” and paid for all of the medical costs she knew about in advance.
Brandon DeLaFosse continued to be billed for outside medical care after he was moved to state prison. On July 23, nearly five months after his sentence began, he saw a doctor and underwent tests at Providence Hospital. He was sent a bill for $224.70 for outpatient diagnostics administered that day, plus $71.98 for the doctor visit.
That shouldn’t have happened, a spokeswoman for the Alabama Department of Corrections said in a statement.
“By ADOC’S policy, all inmates in the care, custody, and control of any ADOC correctional facility are not charged or responsible for community-based medical care or mental health services,” the spokeswoman, Samantha Banks, said.
Any state prisoners “incorrectly” billed for outpatient medical care should notify the provider that they were incarcerated at the time, the statement explained. “The medical provider should submit to the Department the appropriate paperwork and any outstanding inmate medical bills will be directed to the appropriate payer.”
State prisoners in Arizona have reported similar issues with providers billing them directly for medical care they received while incarcerated, as KJZZ radio reported this year. Like in Alabama, the Arizona Department of Corrections has said the bills were sent out in error and that the department or its medical contractor would pay the inmates’ bills.
But that’s a vastly different situation than the one facing inmates in some Alabama counties, where sheriff’s offices are not chalking up such bills to error and are in fact deliberately choosing to avoid paying medical bills for inmates in their charge.
Constitutional Question
Though the public often has little sympathy for inmates, incarcerated people do have clear rights, particularly when it comes to health care behind bars.
Alabama law states that “necessary clothing and bedding must be furnished by the sheriff or jailer, at the expense of the county, to those prisoners who are unable to provide them for themselves, and also necessary medicines and medical attention to those who are sick or injured, when they are unable to provide them for themselves.”
In another section of the state code, a definition of a county inmate includes an explicit reference to their health care being provided for: “any person being held in a public institution under the administrative control and responsibility of the county sheriff and for whom the county is responsible for the provision of medical care.”
Brandon Blankenship, an assistant professor of law and ethics at the University of Alabama at Birmingham, said that allowing inmates to be billed for care that they receive while incarcerated amounts to cruel and unusual punishment and that the bills are excessive fines.
“I don’t think it’s ever been challenged in court in Alabama, but from where I’m sitting, the answer to me is that, no, it’s certainly not constitutional under the Eighth Amendment.”
The tactics of some Alabama sheriffs stand in sharp contrast to what’s going on elsewhere in the country. This year, California and Illinois banned the practice of charging inmates copays, and a number of other states have taken, or are considering, steps to rein in the practice.
“They usually cannot afford even a $5 copay, so the idea that they could pay thousands of dollars for these services is laughable from a practical perspective and it’s downright evil on many different levels,” said Deitch, the University of Texas at Austin professor.
In 1983, the U.S. Supreme Court decided a seminal case, City of Revere v. Massachusetts General Hospital, involving a person who was hurt during an arrest and taken to a hospital. The court ruled that “as long as the governmental entity ensures that the medical care needed is in fact provided, the Constitution does not dictate how the cost of that care should be allocated as between the entity and the provider of the care. That is a matter of state law.”
But that ruling did not answer the question of whether inmates can be stuck with the bill.
“We don’t have any clear Supreme Court ruling,” said Fred Cohen, a professor emeritus at the University at Albany’s School of Criminal Justice who has decades of experience in corrections law and serves as executive editor of Correctional Law Reporter.
Cohen said he believes there is a good case to be made that the practice of allowing inmates to be billed for medical care violates their constitutional rights.
“I don’t think it’s an open policy question in that inmates should not be required to pay,” he said. “I think it could be held unconstitutional by the right court.”
Different Systems
How Chicago, a Hospital and Private Companies Make Money Off the Poor
Three stories about debt, bankruptcy and the institutions that perpetuate them.
by Logan Jaffe
July 5, 4 a.m. CDT
We’ve got some updates and some stories we think you should read this week about debt, bankruptcy and profiting off the poor:
1. Our ongoing reporting on how Chicago’s vehicle ticketing policies harm black and low-income motorists helped spark a decision from a federal appeals court that may allow thousands of motorists every year to get their impounded cars and trucks back sooner than before.
The city of Chicago used to immediately return impounded vehicles to people who filed for Chapter 13 bankruptcy. But two years ago, it stopped doing so, sometimes holding onto the vehicles for months until motorists agreed to pay back more of what they owed in ticket debt during their bankruptcy payment plans. City lawyers had a number of justifications for holding onto the cars and trucks, including saying it was a matter of traffic safety. Lawyers for motorists argued that the city was trying to pressure them to pay and generate revenue.
A panel of the 7th U.S. Circuit Court of Appeals agreed with the motorists.
“We are persuaded that, on balance, this is an exercise of revenue collection more so than police power,” the judges wrote.
Basically, the court said that the city was just trying to make money from people who are already financially struggling, and that the policy violates one of the leading purposes of bankruptcy, which is to help get people back on their feet.
2 Last week, ProPublica and MLK50, a member of our Local Reporting Network, reported on a hospital in Memphis, Tennessee, that’s filed thousands of lawsuits against patients — and even its own employees — for unpaid medical bills. While Methodist Le Bonheur Healthcare isn’t the only hospital in Memphis or in the country that sues patients, Methodist also owns a collection agency, and the hospital’s aggressive collection practices stand out in a city where nearly 1 in 4 residents live below the poverty line. The hospital’s CEO has since promised a review of its policies and this week suspended its “court collection activities.”
3. ProPublica also reported this week on how **electronic monitoring devices such as ankle bracelets are driving defendants into debt**. Private companies charge defendants hundreds of dollars a month to wear the surveillance devices. If people can’t pay, they may end up behind bars. In Illinois, lawmakers recently passed a bill that would require the Illinois Department of Corrections and the Prisoner Review Board to collect data on how electronic monitoring devices are being used and post that information publicly. Learn more about that in this story from WILL-Illinois Public Media.
Hospital Suspends Debt Collection Lawsuits Amid Furor Over Suing Its Own Employees
Methodist Le Bonheur Healthcare is reevaluating its policy after an MLK50-ProPublica investigation found that it had filed 8,300 lawsuits in the past five years, including against many of its own employees.
by Wendi C. Thomas, MLK50
July 3, 10:01 a.m. EDT
==
==
https://www.propublica.org/article/chicago-ticketing-task-force-fines-fees-access-collaborative
Chicago Task Force Will Take on Ticket and Debt Collection Reform
by Melissa Sanchez, ProPublica , and Elliott Ramos , WBEZ
The group is part of an effort to make vehicle ticketing less unfair
==
==
abc news big data soc net:
I haven’t talked to my former roommate Patti in years. But it only took Bill Bartmann, a veteran of the debt collection industry, minutes to pull up her name and the address of the house we shared in the early 1990s.
Less than a day after I asked Bartmann to see what he could find about me, he provided me with a long list of the addresses of places I’d lived over the years -- including my college dorm address, which I would be very hard pressed to recall myself. He also dug up a list of relatives and details about them, including my husband and father’s ages and first five digits of their Social Security numbers; and former neighbors (some of whom I'd never met), along with their ages, first of their SSNs and their phone numbers.
He found all this using nothing more than my name, and the information was spot on. Even if you wanted to try to hide from debt collectors, it would be nearly impossible to do so.
“Every piece of data you can imagine, even your phone records, watch out -- we got it,” says Alexis Moore, a debt collection investigator and industry consultant. Most people “have no clue how cyberspace has made it simple as a click of the mouse to find anyone anywhere at anytime,” she adds.
If debt collectors want to find you, they have many tools at their disposal. If they can’t locate you, or want to learn more about your ability to pay a debt, they can turn to “skip tracing” tools as they are called in the industry. What are some of the ways they do this?
Information You Provide
Debtors themselves are one of the best sources of information, say most collectors. They start with the information provided by their customer -- the lender or company to whom the money was originally owed. This may include "credit applications, agreements, contracts, personal guarantees, purchase orders and/or emails or orders for services or products," says debt collection expert Michelle Dunn.
In fact, this is the data many collectors prefer. "Debt collectors don’t want to have to skip trace to find a consumer," says Nick Jarman, chief operations at Delta Outsource Group Inc., a collection agency. "A lot of it is counterproductive. We want to use the information provided by the original creditor."
That means that if you filled out an application listing your mom as the nearest relative not living with you, then it shouldn’t come as a surprise if the collector calls her when they can’t find you.
Credit Reports & Scores
A debt collector trying to collect a debt you owe typically will be able to pull your credit reports, though not all do. The reason they might not? Cost.
Both Roger Weiss, chief operations officer at collection agency CACI, and Jarman say their firms are likely to use credit scores before they will pull a consumer’s full credit reports, because the first option is cheaper. Weiss also says his firm is cautious about pulling credit because it creates credit inquiries that can lower the debtor’s credit scores. “We are very careful because we don’t want to place a hard inquiry,” he says.
But a full report can be helpful -- if a collector knows what to look for, Moore says. “A(n) experienced vet investigator knows that every piece of data is vital -- so the credit inquiries, charged-off accounts, address history, name variations all mean something and are invaluable tools.”
You can find out if a collector has reviewed your credit reports or credit scores by getting your free annual credit report from all three major credit reporting agencies. Any request for your report -- or scores -- will be visible on your report. (If you want to see how your collection accounts are impacting your credit scores, you can use a free tool like the Credit Report Card, which shows you two of your credit scores for free and explains the major factors that are helping or hurting you.)
Databases
When Bartmann, who is now president of the Center for Consumer Recovery, gathered information about me, he was tapping into just a few of the many databases that collect and sell information about consumers. “As a debt collector you can sign up for a whole litany of services,” he says. “In an era of big data they have gathered all kinds of information about us, some with your permission, sometimes without it.”
Some resources are available for free, such as WhitePages.com, Weiss points out. “Then there are paid compilation services, like when people register for (contests) or change their address.”
LexisNexis Accurint and SearchAmerica are two examples of popular databases Dunn mentioned. Accurint bills itself as a “direct connection to over 37 billion current public records” whileSearchAmerica says it provides “a much more accurate model for predicting the likelihood that a consumer will pay their medical bills.”
In addition to checking what’s reported about you at the three major credit reporting agencies for free once a year, you can get free reports about yourself from some other national consumer reporting agencies, if they have data about you. But it would be a tough, and often futile, task to track down all your information from all sources.
Social Media
Dodging debts? You may want to think twice about posting to social media that picture of the jewelry you just gave your girlfriend. Unless your privacy settings are high, that information may be perused by anyone, including a collector, who may be looking for information about your income, assets or spending patterns.
“Yes, bill collectors do use social media to find their debtors,” says Natasha Carmon, a writer who says she has worked a variety of collection jobs.
“In a divorce case I discovered a wife had obtained a new vehicle through pictures on her Facebook page,” says attorney Tiffany S. Franc. “The vehicle was considered marital property because the parties were still married at the time and it helped my clients negotiating position on other matters at settlement.” She also says she has used LinkedIn profiles to find where debtors are employed in an effort to garnish wages. She goes on to say:
“We peruse Facebook and social media pages and even if the consumer isn't posting about their bank account, they have often times liked their bank's page to indicate to us where they bank. And consumers with assets they really cherish -- collectibles, nice cars, motorcycles, antiques -- oftentimes place pictures of those items on their social media.”
Not all collectors use social media to track down information about debtors. Weiss and Jarman say their firms have made a “business decision” not to, in part due to security concerns. And it’s not clear at the moment what type of social media information collectors can use without violating consumer protection and privacy laws. But for the moment it’s probably safe to say that anything you post is fair game.
Even with all this information available, there’s still some that’s off limit to collectors. “The database I’d love to get ahold of is the Domino’s (Pizza) database,” says Weiss. “Everyone’s in there.”
Sponsored Stories
==
pruitt
https://en.wikipedia.org/wiki/Bill_Bartmann
William R. (Bill) Bartmann (1948 – November 29, 2016) was the founder and CEO of CFS2, Inc, a consumer financial recovery company based in Tulsa, Oklahoma, and earlier the founder and CEO of Commercial Financial Services Inc., the nation’s biggest debt collection company[1] for a time during its operations from 1986 to 1999. One officer of the company was involved in accounting fraud and the company filed for Chapter 11 bankruptcy[2] though allegations of wider fraud were later determined to be untrue.[3]
Contents
[hide]
- :{1:(style="display:table-cell;padding-left:0px;padding-right:0.5em"):}::{Personal life:(style="display:table-cell"):}:
- :{2:(style="display:table-cell;padding-left:0px;padding-right:0.5em"):}::{Commercial Financial Services:(style="display:table-cell"):}:
- :{3:(style="display:table-cell;padding-left:0px;padding-right:0.5em"):}::{Other activities:(style="display:table-cell"):}:
- :{4:(style="display:table-cell;padding-left:0px;padding-right:0.5em"):}::{CFS2:(style="display:table-cell"):}:
- :{5:(style="display:table-cell;padding-left:0px;padding-right:0.5em"):}::{Industry reform efforts:(style="display:table-cell"):}:
- :{6:(style="display:table-cell;padding-left:0px;padding-right:0.5em"):}::{References:(style="display:table-cell"):}:
- :{7:(style="display:table-cell;padding-left:0px;padding-right:0.5em"):}::{External links:(style="display:table-cell"):}:
Personal life
Bartmann was born in Dubuque, Iowa in 1948. At age 14, he dropped out of high school and joined a traveling carnival. He later joined a gang called the Manor Boys.[4] He attempted to join the Marines but was rejected for hearing problems. Bartmann became an alcoholic by age 17, and one night fell down a flight of stairs while drunk. He became paralyzed and was told that he would never walk again. Against his doctor's wishes, Bartmann embarked on a nightly regimen of physical activity until he eventually regained the use of his legs.
For several years Bartmann worked at the Dubuque Packing Company, a large local slaughterhouse. While there, Bartmann organized a wildcat strike to force the company to give benefits to part-time workers. The strike was successful. Around this time, Bartmann ran into a high school principal who earlier had expelled him from school. The principal challenged Bartmann to get his GED certificate, which he did. Bartmann later earned a BS from Loras College and a JD from Drake University.
After passing the Iowa Bar Exam, Bartmann immediately went into private practice, specializing in consumer law. He also invested in real estate. Bartmann moved to Muskogee, OK to devote full-time to real estate investing. Bartmann was later asked by a local bank to take over a struggling oil equipment company in Oklahoma. He turned around the company and grew it substantially. It folded in 1985 due to falling oil prices, with Bartmann one million dollars in debt due to personally guaranteeing some of the corporate obligations.[4] Bartmann died at the age of 68 due to complications shortly after heart bypass surgery on November 29, 2016.[where?][5]
Commercial Financial Services
Hounded by debt collectors, Bartmann looked for other opportunities. He saw an ad in the newspaper about buying defaulted loans from the federal government. He bought a portfolio of loans, financed by the bank he was $1 million in debt to. Bartmann succeeded in collecting enough money from that first portfolio to recoup the cost of the portfolio, plus make a partial repayment on his bank debt. That led to more purchases of loan portfolios that allowed Bartmann to repay the entire $1 million obligation. Bartmann created a consumer friendly company that would buy delinquent debts from banks and then attempt to restructure them according to terms the customer could afford. The strategy was successful, he was able to help 4.5 million consumers resolve $15 billion in debt, all of it without ever suing a consumer, producing net margins as high as 48%.[4]
By 1997, Bartmann was listed in Forbes magazine as one of the 400 richest people in America. Inc. magazine estimated Bartmann's net worth to be in the range of $2.4 to $3.5 billion.[4] Goldman Sachs offered to buy a 20% stake in the company and Norwest Bank offered to acquire, but Bartmann refused both offers.
As the company grew, Bartmann gained a reputation for doing the unexpected. He challenged his staff that if they beat their performance goals, he would take them all to Las Vegas. They exceeded the target and Bartmann flew the entire company to Las Vegas. Bartmann arrived and wrestled Hulk Hogan at the Thomas & Mack Center in Vegas." [4] On another occasion, Bartmann leased 27 Boeing 747 Jumbo Jets to fly thousands of employees to Disney World for the weekend. CFS offered free on-site daycare that grew to 500 children, as well as free full health care and a 250% company match in its 401(k) program. BusinessWeek magazine called CFS "One of the top 10 family-oriented businesses in America" and Working Mother Magazine named it "One of the top 100 best companies for working mothers."
In 1998 the Harvard Business School published a case study on the methods Commercial Financial Services used to securitize non-performing debt.[6] The Smithsonian Institution's Museum of American History awarded CFS its Computer World award[7] for technological innovations.
Also in 1998, an investigation began after an anonymous letter raised questions about the propriety of certain transactions at the company by a rogue employee. Throughout the ensuing investigation, Bartmann maintained his innocence. Jay Jones, a shareholder of the company, later confessed to the questionable transactions and admitted that Bartmann did not know about them. Nevertheless, the U.S. Department of Justice persuaded a third grand jury to indict Bartmann and other senior executives.
In the trial that followed, Bartmann was found to be not guilty of all charges.[8] One of Bartmann's co-defendants sued the government for malicious prosecution and won.[9] Even so, the controversy meant his company could not obtain financing and Commercial Financial Services declared bankruptcy. A bankruptcy trustee liquidated the company, laying off its 3900+ employees.[10]
In 2005, the bankruptcy trustee for Commercial Financial Services publicly declared that the company had not engaged in fraud.[3] Bartmann was cleared of all wrongdoing.[11][12]
Other activities
In 2002, the Governor appointed Bartmann to the board of Oklahoma Futures, a public-private partnership whose goal was to advise the governor, legislature, and judiciary on ways to promote economic development in Oklahoma.[13] The Senate confirmed Bartmann's nomination.
In 2003 Bartmann founded Bill Bartmann Enterprises in order to offer business training and information to entrepreneurs. In 2008 he noticed that the banking bailout and TARP subsidies presented an opportunity to buy defaulted debt from troubled banks, mirroring the situation he built Commercial Financial Services on in the 1980s and 1990s. Bartmann developed a series of training programs to enable individuals to buy portfolios of defaulted credit-card debt and then taught them how to collect without using litigation or other abusive behavior.
In 2009 Bartmann published a book, "Bailout Riches", which describes the opportunity he says the bank-bailout and recession of 2008-2010 has created. The book became a #1 world-wide bestseller on Amazon, and also made it to the Wall Street Journal, USA Today and BusinessWeek bestseller lists.
In 2010 Bill Bartmann Enterprises was named to the "Inc. 500" for 2009. It's the fifth time Bartmann has made the list.[14][15]
CFS2
Bartmann re-established his former consumer financial recovery company, naming the successor entity, CFS2, in July 2010. Later that year the company leased space at the CityPlex Towers complex in south Tulsa, returning Bartmann to the location where CFS had previously operated.[16] Bartmann is in the midst of reviewing potential sites across the country for expansion, with Nevada, North Carolina, Ohio and Arkansas having offered incentives.[17] Counter-intuitively CFS2 offers a unique array of free services to those they are collecting from, including: employment assistance,[18] credit specialists who negotiate reductions of other personal debt, resume writing, medical discounts and help accessing government assistance. An anomaly to the debt collection industry, CFS2 has pledged to never litigate in order to collect from their accounts and has encouraged others in his industry to follow his lead.[19] This helping hand approach reduces the banks reputational risk while enabling CFS2 to collect at rates twice the industry average.
In April 2013 CFS2 became the first and only collection company to ever win The American Consumer Council's[20] "Friend of the Consumer" award. In bestowing the award American Consumer Council CEO, Thomas Hinton, remarked "as a financial recovery company, CFS2 is offering valued services that millions of consumers desperately need as we emerge from one of the longest recessions in our nation's history."[21] In 2014 he won this award for the second time.[22] CFS2 has also won the Compass Award for Business Ethics;[23] the Beacon Award for Community Involvement[24] the “Stevie” Award for Customer Service, and has been named as one of the most admired CEO's in Oklahoma by the Oklahoma Journal Record.[25][26]
In October 2013 CFS2 was featured on CBS Evening news as the debt collector who thrives using the unique strategy of kindness.[27]
Industry reform efforts
In the 1990s Bartmann gained a reputation for collecting debts by avoiding strong-arm tactics.[4] He is following the same consumer-advocate approach in his new company, CFS2. He says: "We’re going to go at it the same way we did before, treating people with respect and helping them out of bad situations." [28] A Bartmann-run website, StopTheseCriminals.com, urges consumers to sign a petition that calls for drastic legislative and regulatory reforms of the debt-collection industry. Among those recommended reforms are the barring of all collection efforts on debt that is older than the statute of limitations; allowing consumers to record telephone calls from collection agencies; and requiring the licensing of both agencies and individual collectors.
Bartmann has persuaded 200 Debt Buying companies[29] to take the “Bartmann Pledge’.[30] The Bartmann Pledge requires all signors to agree not to use litigation against debtors; not to charge interest on the obligation, not to attempt to contact debtors more than twice in one day, not to pursue debtors beyond the statute of limitations and not to resell delinquent loans.
Bartmann has worked with members of the U.S. House of Representatives and U.S. Senate to reform the current federal debt-collection rules. In addition he helped to enact a recent change to the Oklahoma debt-collection rules, which the Governor of Oklahoma signed into law in June 2011.[31]
Bartmann authored Oklahoma Senate bill 1430 “The Bartmann Bill” which would require debt collectors to follow stringent practices designed to protect consumers. This bill passed the Senate 40-2.[32] In 2011 Bartmann was nominated to the Consumer Advisory Board of the Consumer Financial Protection Bureau (CFPB) by the president of the American Bankers Association (ABA), Frank Keating. The nomination was seconded by six sitting state attorneys general.
In October 2012, Bartmann was invited to the West Wing of the White House to meet with the Deputy Director of the National Economic Council and Senior Policy Advisers to discuss the creation of a moratorium on debt collection litigation that would reduce the national bankruptcy rate by as much as 50% while also reducing the national unemployment rate. Bartmann has worked extensively with Attorneys General across the United States to promote debt collection reforms and has testified as an expert witness at their request at numerous proceedings.[33]
Bartmann is a regular contributor to publications like The Huffington Post[34] and The Christian Science Monitor.[35][36] He authored Out of Control: Cases of Debt-Collection Abuse In America And What We Can Do About It,[37] an expose´of the debt collection industry.
Bartmann created the non-profit organization, The Center for Consumer Recovery,[38] which, in October 2013, launched the Shutdown Affected Forbearance Relief (SAFR) program to help the 400,000 federal employees furloughed by the government shutdown.[39] The Center for Consumer Recovery contacts the creditors of these furloughed workers and persuades them to grant a forbearance of interest, principal and credit reporting until the employee is called back to work. The organization's primary charter is to assist families victimized by natural disasters and act as an advocate and intermediary by dealing with the victim’s creditors, insurers and governmental agencies.
In July 2013 Bill Bartmann was nominated for the 2014 Nobel Peace Prize for his debt collection industry reform efforts.[40][41]
In April 2014, The Governor of Oklahoma appointed Bartmann to the Council of Bond Oversight. This five-member Council is responsible for reviewing and approving all financing requests by state agencies, authorities, departments and trusts.[42]
References
https://www.thenation.com/article/why-are-political-groups-pretending-be-debt-collectors/
January 25, 2010, a coworker e-mailed me after a brief panic. She had just received an e-mail with the subject line “Final notice,” and thought her car was going to repossessed.
But her car wasn’t in danger of disappearing—and she e-mailed me because I was the one who sent the message, to her and 250,000 other people, asking them to sign a petition about a public option in the healthcare reform bill.
I was in charge of e-mail advocacy for the blog Firedoglake, and it was part of my job to get people to open e-mails, sign petitions, and make donations to support our work. I thought using “Final notice” would get more people to notice the pitch, which began “This is your final notice to sign our emergency petition to progressive Members of Congress…”
Unfortunately, it appears I was among the first in the political advocacy world to employ that deception, and today the tactic is increasingly common. Recently, I woke up to an e-mail from an address that began FINAL-NOTICE, and the subject line was “AUTO-CONFIRM: [M. Whitney (3/31/2015)].” It wasn’t from my bank, but rather the Democratic Congressional Campaign Committee.
...
==
you're behind on you're taxes, you could get a phone call from an unexpected place this year.
For-profit debt collectors have been hired by the IRS to chase down long-overdue taxes that the government agency lacks the resources to work on. Four companies were selected for the new contracts, including one whose parent company is currently being sued by the US government over its student loan debt collection practices.
Pioneer Credit Recovery is a subsidiary of the student loan giant Navient; both companies were the subject of a Consumer Financial Protection Bureau lawsuit filed in January. Pioneer was selected for one of the IRS debt collection contacts last September, alongside ConServe, Performant and CBE Group.
More from Buzzfeed:
Navient, formerly known as Sallie Mae,currently holds a federal government contract to service about $300 billion in student loans owed by 12 million borrowers. Pioneer, working under Navient, "systematically misled consumers" when attempting to enroll them in a loan rehabilitation program, the Consumer Financial Protection bureau claimed in its January lawsuit.
The IRS was mandated by Congress to hire private-sector debt collectors, in language that was inserted into a $305 billion highway funding bill in late 2015. Navient spent almost $2.4 million lobbying Congress that year, according to data collected by the Center for Responsive Politics, on topics including "issues pertaining to federal collection programs" in the highway bill.
Some experts on consumer protection say the new contracts create more potential for bad behavior.
"I worry whenever a federal agency employs for-profit debt collectors to settle debts," said David Vladeck, a former director of the Federal Trade Commission's consumer protection bureau and a professor at Georgetown Law. "When you align a situation where the IRS is unable to collect, the incentive to really turn the screws hard is pretty high because that's the only way they're going to get paid. This is a really toxic combination."
Navient pointed BuzzFeed News to its January statement which callsthe bureau's allegations, filed in the final days of the Obama administration, "unsubstantiated, unjustified and politically driven." A company fact sheet says that since 2012, Navient helped nearly 250,000 borrowers successfully rehabilitate their loans using language nearly identical to what regulators used.
The CFPB told BuzzFeed News that it accepts consumer complaints about debt collection.
"The Bureau receives complaints from consumers about a variety of consumer financial products and services, including debt collection," it said in a statement. "In some cases, the Bureau's Consumer Response office refers or sends a complaint to another regulator. All complaints handled by the Bureau, including those sent to other regulators, serve to inform the Bureau in its work to supervise companies, to enforce consumer financial laws, to write better rules and regulations, and to educate and engage consumers."
Pioneer Credit Recovery, which specializes in collecting defaulted loans, has come under close government scrutiny in recent years. The Department of Education cut the company's student loan contract after an audit of several sample calls revealed collectors misled consumers. One Florida borrower accused the company this year of harassing phone calls to collect debt, and a Georgia resident sued the company in 2015 alleging it was aggressively retrieving debt from the wrong person altogether.
A spokesperson for the IRS directed BuzzFeed News to its site which states that Pioneer, and the three other companies, are contractually obligated to respect taxpayer rights and follow fair debt collection laws. The agency told BuzzFeed News it will also conduct monthly oversight and annual reviews of each company, including taxpayer complaints.
"The IRS will do everything it can to help taxpayers avoid confusion and understand their rights and tax responsibilities, particularly in light of continual phone scams where callers impersonate IRS agents and request immediate payment," the agency said in September.
But Chi Chi Wu, a staff attorney with the National Consumer Law Center, told BuzzFeed News that the IRS' previous private debt collection experiments showed "dismal results" where "the government ended up losing money."
The NCLC opposed the contracts when they were awarded last year. "Congress forced the IRS to hire the most complained about industry in the financial sector to undertake a vital and core government function," Wu said at the time.
The IRS last contracted with private debt collectors in 2006 to collect on $1.8 billion in "easy" debts that were 1-3 years old. But an analysis by the Office of the Taxpayer Advocate showed that over the two years it was contracted, the private companies "had little success after working the easy cases."
The IRS on average collected about 62% more than the private collectors, the analysis found.
A 1996 pilot program to use private contractors left the IRS with more money spent than retrieved. It reported $4.1 million in expenses by the end of the program in January 1997, with only $3.1 million in collections, according to a Government Accountability Office report.
Ben Barrett, a program associate with the education policy program at the progressive New America foundation, told BuzzFeed News that the government contracting with a private collector poses certain profit incentives that could open up "unsavory practices, illegal practices."
But he also said a private contractor, with IRS oversight, could collect debts with more efficiency than the government. The Treasury Department said in 2016 that its pilot program to collect on defaulted student loans with a gentler approach failed in comparison to private companies.
"Obviously nobody should be doing anything illegal," he said. "You should never cross that line. In so far as they can adhere to the law and get a delinquent taxpayer on the phone through whatever legal means necessary, that's not necessarily a bad thing."
Watch: Mnuchin on closing loopholes[vid]
==