student Debt 2 loans
---
NOW TWO 12 23 formerly bak
some new on scotus loss 6 23 target? cruz?
no merri
SEE BIG BEUT BILL
see also debt
see also for profit colleges, MOOC,
strict fr?
see thom 3? robert reich US fed? used to pay for 65% of college? gt recession austerity broke state budgets?
bak 11 22
aha hmmn student debt record did not help biden harris? college is biggest div dem/gop; young POC did not benefit or think they can’t?
cruz sued biden?!
AHA FOX BIZ PAYNE REMINDS THIS IS OLD PINKO PROF BS W SNOWFLAKE CODDLE // TRUMP ATTACK ON UNIVERSITIES 5 25 ELITES
LEVER
5 26 lever Trump’s Private Repo Men Are Hunting Immigrants (https://www.levernews.com/trumps-private-repo-men-are-hunting-immigrants/)
theTrump administration (https://www.levernews.com/tag/donald-trump/) has quietly hired a team of scandal-plagued private debt collectors to hound immigrants (https://www.levernews.com/tag/immigration/) slapped with new multimillion-dollar civil penalties for not leaving the country, according to documents reviewed by The Lever. All of the companies previously worked on a federal student loan debt-collection program shut down for widespread abuses.
One private collection notice (https://www.documentcloud.org/documents/28094625-conserve-letter/?ref=levernews.com) obtained by The Lever assessed a $1.8 million fine on its recipient, the maximum penalty allowed under immigration law, plus another half a million in fees and interest charges, bringing the total to $2.3 million.
IFrame Content (https://embed.documentcloud.org/documents/28095201-conserve-letter-rev3/?embed=1)A collection notice sent by a private debt-collection agency regarding a $1.8 million Homeland Security fine, plus another half a million in fees and interest charges.
That notice is not a one-off. According to immigration lawyers, there’s been a recent uptick in collection letters from private firms demanding immigrants pay multimillion-dollar fines, which the Department of Homeland Security began imposing last year.
As directed by a White House executive order (https://www.whitehouse.gov/presidential-actions/2025/01/protecting-the-american-people-against-invasion/?ref=levernews.com) from January, the Trump administration is using these massive new financial penalties to pressure immigrants to self-deport as part of its immigration crackdown (https://www.levernews.com/tag/immigration/). And to ensure immigrants ship out or pay up, the White House is enriching private contractors with a history of dubious practices, just like it has outsourced oversight of its detention centers (https://www.levernews.com/ice-detention-contractors-unhealthy-profits/) to embattled for-profit companies like GeoGroup and CoreCivic.
“This is part and parcel with the administration’s desire to partner with the private sector to make immigration enforcement as punitive and painful as possible,” said Charles Moore, an attorney at Public Justice, a legal advocacy and defense group. “It’s very telling that they view the private market as the best way to accomplish that.”
As of last year, the administration had slapped hefty fines totaling an estimated $6 billion on over 20,000 immigrants (https://legalaidnyc.org/news/federal-immigration-fines-unconstitutional/?ref=levernews.com) for various infractions. The bulk of those penalties relate to overstaying a deportation removal order, for which immigrants are now being fined nearly $1,000 a day for up to five years.
Now, Homeland Security is outsourcing the management of that debt to the private collection industry (https://newrepublic.com/article/117213/debt-collector-malpractice-someone-elses-debt-could-ruin-your-credit?ref=levernews.com), which has faced mountains of lawsuits and consumer complaints (https://www.consumerfinance.gov/data-research/research-reports/fair-debt-collection-practices-act-cfpb-annual-report-2024/?ref=levernews.com) over exploitative practices such as harassing (https://www.consumerfinance.gov/data-research/research-reports/fair-debt-collection-practices-act-cfpb-annual-report-2024/?ref=levernews.com) consumers who are late on credit card bills, medical payments, or auto loans.
At least four private companies inked debt-collection deals with Homeland Security as the agency began ramping up civil penalties on immigrants, according to procurement records. That included (https://embed.documentcloud.org/documents/28093287-screenshot-2026-05-04-at-54724-pm/?embed=1&ref=levernews.com) Continental Services, one of the largest collection agencies nationwide, which signed three purchasing agreements (https://www.usaspending.gov/award/CONT_IDV_70B01C25A00000024_7014?ref=levernews.com) with Homeland Security last September worth a combined $1 million (https://www.usaspending.gov/award/CONT_IDV_70B01C25A00000024_7014?ref=levernews.com). A fifth company is doing debt-collection work for Homeland Security through a contract with the Treasury Department, which manages the account where payments for these fines are deposited.
All of these private agencies were (https://www.americanprogress.org/article/getting-private-collection-agencies-federal-student-loans/?ref=levernews.com) previously part of a federal student loan debt-collection program plagued (https://www.americanprogress.org/article/getting-private-collection-agencies-federal-student-loans/?ref=levernews.com) by alleged misconduct. That program was eventually shut down (https://www.wsj.com/politics/policy/biden-administration-to-sever-ties-with-student-loan-debt-collectors-11636079495?ref=levernews.com) by the Biden administration due to widespread operational problems (https://www.americanprogress.org/article/getting-private-collection-agencies-federal-student-loans/?ref=levernews.com), massive fees (https://www.americanprogress.org/article/getting-private-collection-agencies-federal-student-loans/?ref=levernews.com) on borrowers, and cost overruns (https://www.americanprogress.org/article/getting-private-collection-agencies-federal-student-loans/?ref=levernews.com) for taxpayers.
Now, that same group of debt collectors has been rewarded with new Homeland Security contracts — which have fewer guardrails in place to protect debtors.
“If you’re [Homeland Security Adviser] Stephen Miller, you want the worst debt collector in America to be as aggressive and harassing as possible, because the goal is to make people miserable to get them out of the country,” said Mike Pierce, the executive director of Protect Borrowers, a legal advocacy group for consumer rights, who previously worked on student-borrowing issues at the Consumer Financial Protection Bureau.
Homeland Security and the debt collection agencies did not respond to a request for comment.
“A Total Sham”
Around March 2025, the Trump administration began levying large penalties on immigrants by relying on an obscure provision (https://www.politico.com/news/2026/01/29/immigration-deportation-lawsuits-00755663?ref=levernews.com) from a 1996 immigration law signed by President Bill Clinton. The statute allows the government to fine undocumented immigrants for willfully failing to depart the country — but it had never been enforced until President Donald Trump first took office.
Around 2018, after Congress blocked (https://www.washingtonpost.com/business/economy/house-democrats-prepare-vote-to-reopen-government-as-cracks-appear-in-gop-opposition/2019/01/03/24151490-0f96-11e9-8938-5898adc28fa2_story.html?ref=levernews.com) the total funding requested by the Trump administration to build a wall along the country’s southern border, then-White House advisor Stephen Miller devised (https://americanoversight.org/in-the-documents-stephen-miller-emails-with-justice-department-official-about-anti-immigration-measures/?ref=levernews.com) an alternative strategy. The administration would finance the wall by leveraging its civil penalty authority to raise funds on the backs of immigrants, according to leaked emails (https://americanoversight.org/in-the-documents-stephen-miller-emails-with-justice-department-official-about-anti-immigration-measures/?ref=levernews.com) obtained by the government watchdog group American Oversight.
:{
Once collected, those fines would be held in an “immigration enforcement account” administered by the U.S. Treasury that could then be tapped (https://americanoversight.org/in-the-documents-stephen-miller-emails-with-justice-department-official-about-anti-immigration-measures/?ref=levernews.com) by Homeland Security as a de facto slush fund for enforcement initiatives of its choosing.
While the penalty program remained fairly limited (https://www.politico.com/news/2026/01/29/immigration-deportation-lawsuits-00755663?ref=levernews.com) during Trump’s first administration, it has ramped up (https://legalaidnyc.org/news/federal-immigration-fines-unconstitutional/?ref=levernews.com) considerably under his second term. By August of last year, over 20,000 people (https://legalaidnyc.org/news/federal-immigration-fines-unconstitutional/?ref=levernews.com) had been slapped with new fines.
Homeland Security recently expanded the scope of these penalties, including instituting a new $5,000 fine for illegal border crossings (https://nysfocus.com/2025/10/24/big-beauitful-bill-immigrant-children-fine?ref=levernews.com), as authorized by the One Big Beautiful Bill. But the most common fines target immigrants for overstaying deportation removal orders issued by immigration judges.
The government is now fining immigrants (https://www.dhs.gov/news/2025/06/27/dhs-and-doj-announce-streamlined-process-fining-illegal-aliens?ref=levernews.com) nearly $1,000 for every day they overstay a deportation order, even if those court orders were issued years ago.
The statute of limitations for such a penalty is five years, meaning the maximum fine Homeland Security can levy is $1.8 million. For many immigrants, that’s an insurmountable amount of debt (https://www.wsj.com/politics/policy/ice-immigrant-fine-collection-db1a3610?mod=hp_lista_pos3&ref=levernews.com), and it can’t be waived unless they leave the country.
The department also instituted new rules (https://www.dhs.gov/news/2025/06/27/dhs-and-doj-announce-streamlined-process-fining-illegal-aliens?ref=levernews.com) “streamlin\ing] the process for fining illegal aliens,” which entailed [gutting (https://www.dhs.gov/news/2025/06/27/dhs-and-doj-announce-streamlined-process-fining-illegal-aliens?ref=levernews.com) the administrative hearings where they could previously protest a fine. Now, immigrants are merely entitled to written notice from the government in response to their petitions.
The rules also reduce (https://www.dhs.gov/news/2025/06/27/dhs-and-doj-announce-streamlined-process-fining-illegal-aliens?ref=levernews.com) the number of days’ notice Homeland Security must give immigrants before beginning to collect such fines, so they can contest the matter. That number is now 15 days, down from 30.
According to a lawsuit filed (https://www.publicjustice.net/lawsuit-immigration-civil-fines-ice-homeland-security-department-of-justice/?ref=levernews.com) by a collection of immigration lawyers last year, Homeland Security may be enforcing (https://www.publicjustice.net/lawsuit-immigration-civil-fines-ice-homeland-security-department-of-justice/?ref=levernews.com) this new penalty program illegally by targeting immigrants who have other legal avenues to remain in the country. The suit argues (https://www.publicjustice.net/lawsuit-immigration-civil-fines-ice-homeland-security-department-of-justice/?ref=levernews.com) that the government has failed to demonstrate that many of these fines’ recipients were willfully defying deportation removal orders, per the statute.
According to the suit, in some instances, immigrants have secured permission from immigration authorities to temporarily remain in the country, but they still faced heavy fines. In other cases, immigrants received fines despite being in the process of contesting their deportation orders and pursuing other legal avenues to remain in the country, such as applying for temporary visas that may still be available to them.
“The entire process is a total sham,” said Moore, the attorney at Public Justice.
These ongoing legal challenges haven’t discouraged Homeland Security, which is now working with the Justice Department to file lawsuits (https://www.politico.com/news/2026/01/29/immigration-deportation-lawsuits-00755663?ref=levernews.com) against immigrants who haven’t paid their million-dollar fines. With a court order, the government can begin garnishing wages and seizing assets if payments aren’t made.
“We’ve heard of people who weren’t even notified of the fine before getting served a lawsuit by the government,” said Nicollete Glazer, an immigration lawyer based in Los Angeles. “There’s a lot of bad practices taking place.”
Weaponizing Financial Distress
In addition to bringing legal action against immigrants who haven’t paid their fines, Homeland Security is also using its massive new $190 billion (https://www.nytimes.com/2026/01/28/us/politics/ice-funding-congress.html?ref=levernews.com) immigration enforcement budget to award lucrative contracts to private contractors to collect this debt on the agency’s behalf.
Immigration lawyers say they used to only see debt notices coming directly from the government; now they’ve noticed an increase in notices sent by a host of private debt collectors. From June to September of last year, the Department inked procurement deals with Continental Services and four other debt agencies. That included a major collector, FH Cann Associates, which was awarded a contract valued at nearly $700,000. Coast Professional Inc., Central Portfolio Control Inc., and Pioneer Credit Recovery were also tapped by Homeland Security.
According to immigration lawyers, most of the collection papers they’ve seen from private contractors are for fines in the millions of dollars, accompanied by sky-high fees.
In itemized payment sheets (https://www.documentcloud.org/documents/28094625-conserve-letter/?ref=levernews.com) sent by private collectors and reviewed by The Lever, such “administrative fees” make up the bulk of the financial markups, sometimes totaling $500,000 in charges for an $1.8 million fine. Language from the notices (https://embed.documentcloud.org/documents/28094622-cbp-collections-notice/?embed=1&ref=levernews.com) inform its recipients that authorized private collectors may collect fees as well as charge interest at an unspecified rate.
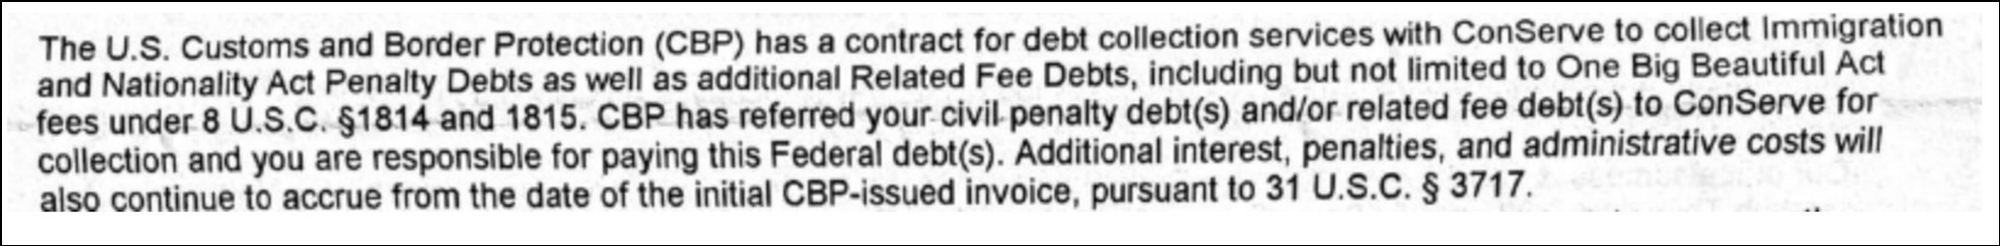 A Customs and Border Protection notice informing people that authorized private debt collectors may collect fees and charge interest on the Homeland Security fines.
“Additional interest, penalties, and administrative costs will also continue to accrue from the date of the initial CBP-issued invoice,” reads (https://embed.documentcloud.org/documents/28094622-cbp-collections-notice/?embed=1&ref=levernews.com) one notice sent by Customs and Border Protection, the division of Homeland Security that administers these fines.
It’s unclear whether these fees and interest charges line the contractors’ pockets or are transferred back to the government’s immigration enforcement account.
Based on the procurement records reviewed by The Lever, the private debt contractors are paid for their debt-collection services, regardless of whether they recover the fine.
A History Of Abuse
All of the debt collection firms now working under contract for Homeland Security formerly held (https://web.archive.org/web/20200508040403/https://studentaid.gov/data-center/student/default) contracts with the Department of Education to collect money from students who defaulted on government-guaranteed loans to pay for college.
The 2010 Federal Direct Loan Program created (https://revealnews.org/article/who-got-rich-off-the-student-debt-crisis/?ref=levernews.com) government-backed student loans, whose debt servicing was then outsourced (https://revealnews.org/article/who-got-rich-off-the-student-debt-crisis/?ref=levernews.com) to private firms. That public-private partnership was eventually expanded under the Obama administration to include 30 contractors (https://www.americanprogress.org/article/getting-private-collection-agencies-federal-student-loans/?ref=levernews.com). But the program quickly became a political and legal debacle (https://www.washingtonpost.com/education/2021/02/01/navient-student-loans-education-department/?ref=levernews.com), one that didn’t fade even after the Obama administration tried implementing (https://www.bloomberg.com/news/articles/2013-03-19/obama-cuts-student-debt-collector-commissions-to-aid-borrowers?ref=levernews.com) reforms to cap exorbitantly high fees charged by student debt collectors.
In 2017, a Consumer Financial Protection Bureau issued a scathing report (https://files.consumerfinance.gov/f/documents/201705_cfpb_Update-from-Student-Loan-Ombudsman-on-Redefaults.pdf?ref=levernews.com) finding endemic problems with the Education Department’s debt-collection privatization effort, including that contractors were profiting immensely from the program despite not delivering results.
For example, investigators found that the companies’ collection cost fees totaled as much as 25 percent of students’ loan balances, even though those fees didn’t reflect the firms’ actual costs of collecting such payments. In total, the Consumer Financial Protection Bureau found (https://files.consumerfinance.gov/f/documents/201705_cfpb_Update-from-Student-Loan-Ombudsman-on-Redefaults.pdf?ref=levernews.com) that the government was reimbursing these firms $40 for every $1 they recovered from students.
The report led to a Senate inquiry (https://web.archive.org/web/20200121170818/https://www.harris.senate.gov/imo/media/doc/180123%20-%20PCA%20Letter%20%281%29.pdf) that concluded the program was fueling (https://web.archive.org/web/20200121170818/https://www.harris.senate.gov/imo/media/doc/180123%20-%20PCA%20Letter%20%281%29.pdf) a punitive, wasteful, and self-defeating debt cycle.
In a letter to (https://web.archive.org/web/20200121170818/https://www.harris.senate.gov/imo/media/doc/180123%20-%20PCA%20Letter%20%281%29.pdf) the Education Department, a group of senators wrote that the “Departmental process provides perverse financial incentives for private collection agencies to aggressively pursue borrowers… and encourages distressed borrowers to use less successful tools to help them deal with default.”
In 2021, the Biden administration shut down (https://www.wsj.com/politics/policy/biden-administration-to-sever-ties-with-student-loan-debt-collectors-11636079495?ref=levernews.com) the private-sector student debt collection effort entirely. But now, some of the same contractors involved in the Education Department program have been reemployed to collect debts for Homeland Security.
:{
Most prominently, in 2017, the Obama administration sued (https://www.consumerfinance.gov/about-us/newsroom/cfpb-sues-nations-largest-student-loan-company-navient-failing-borrowers-every-stage-repayment/?ref=levernews.com) Navient, then an Education Department loan-servicing contractor, and its subsidiary, Pioneer Credit Recovery, for failing to inform students about debt-relief options before demanding payments, among other questionable practices.
In 2024, the Consumer Financial Protection Bureau finalized (https://www.consumerfinance.gov/about-us/newsroom/cfpb-bans-navient-from-federal-student-loan-servicing-and-orders-the-company-to-pay-120-million-for-wide-ranging-student-lending-failures/?ref=levernews.com) a $120 million settlement in the matter banning Navient from all federal student loan servicing and putting Pioneer under the supervision (https://www.consumerfinance.gov/enforcement/actions/navient-corporation-navient-solutions-inc-and-pioneer-credit-recovery-inc/?ref=levernews.com) of the chief consumer regulatory agency.
Now, Pioneer, which was spun off from Navient (https://news.navient.com/news-releases/news-release-details/navient-finalizes-sale-government-services-business?ref=levernews.com) in 2025, appears to have been tapped to work on behalf of Homeland Security’s new financial-penalty effort. The firm has sent collection letters for Homeland Security fines, according to immigration lawyers, as part of an ongoing contract (https://www.usaspending.gov/recipient/82c99c51-b57c-8c7a-f659-c0696b808f14-C/latest?ref=levernews.com) it has with the Treasury Department.
Alongside Pioneer, Continental Services, FH Cann Associates, Coast Professional Inc., and Central Portfolio Control Inc. were all part (https://web.archive.org/web/20201114065942/https://studentaid.gov/sites/default/files/Default_Recoveries_PCA.xls) of the Education Department’s debt-collection privatization effort before being recently tapped directly by Homeland Security. Central Portfolio Control was a subcontractor (https://www.highergov.com/awardee/central-portfolio-control-inc-344642500/?ref=levernews.com#subcontracts) of another debt agency, Professional Bureau of Collections of Maryland, which had secured a $13 million contract from the Education Department.
According to immigration lawyers and debt protection lawyers, the overlap may be by design.
“This kind of operation is going to be a perfect fit for [Homeland Security], which will tell [private contractors] there’s no rules or accountability,” said Glazer, the Los Angeles immigration lawyer. “And with the government guaranteeing pay, it’s a major revenue source for these collectors, even if they don’t end up collecting debt.”
According to Glazer, private collectors’ automated technology systems can churn out text messages, emails, letters, and phone calls at a vast scale to hound debtors for payments. That could be a major boon for Homeland Security, given the massive number of fines it has levied.
And now, the rapacious practices once deployed on student borrowers may be unleashed on immigrants who have even fewer legal protections.
“We’re seeing financial distress weaponized all across this administration to manipulate people’s behavior, especially now with immigration,” said Pierce at Protect Borrowers.
rww
10/30/2025
by
- Stephanie Mencimer @ Mother Jones: Sean Duffy’s Holy War at the Transportation Department
Duffy has found a way to turn even the most mundane highway procurement matters into an opportunity for pandering to the MAGA base—and getting back on Fox News. His secret sauce? He has been enthusiastically using the agency to spread the Gospel and advance his mission to make America fecund again.
- Ewan Palmer @ The Daily Beast: Vicious MAGA Civil War Breaks Out Over Trump’s Third Term
Trump loyalist Steve Bannon is being accused of giving MAGA false hope for 2028.
- Elie Mystal @ The Nation: Why Has Trump Been Flirting With a Third Term?
Trump cannot be president again. But he and his loyal followers have every reason for wanting to make people think he can.
- Ryan Adamczeski @ The Advocate: Trump's DOE will make LGBTQ+ nonprofit workers ineligible for student loan forgiveness
Trump's Department of Education is making workers of LGBTQ+ nonprofits ineligible for student loan forgiveness.
- Doug Bock Clark @ ProPublica: God’s Chief Justice
Paul Newby, a born-again Christian, has turned his perch atop North Carolina’s Supreme Court into an instrument of political power. Over two decades, he’s driven changes that have reverberated well beyond the borders of his state.
- Will Sommer @ The Bulwark: One of the Most Dangerous Interviews Ever in MAGA Media
Why Tucker Carlson platformed white supremacist Nick Fuentes.
---
---
an 5 25
:{:{During the House’s marathon markup of President Donald Trump’s historic budget bill, the Chairwoman of the powerful Rules Committee lashed out at Democrats for plainly describing the legislation’s sweeping consequences. Officially dubbed the “One Big, Beautiful Bill Act,” the measure narrowly passed in the early hours of Thursday by a 215–214 vote. }:
It removes $800 billion in funding from Medicaid, would lead to $535 billion in cuts to Medicare, and is projected to cause an estimated 8.6 to 13.7 million Americans to lose their health care. It will also add $3 trillion to the federal deficit—fueled by tax breaks heavily tilted toward the wealthy and the nation’s first-ever $1 trillion defense budget.}:
“I am concerned about what has been said about this bill and what it’s going to do,” Chairwoman Virginia Foxx (R-NC) told the members of her committee Wednesday night. “The extreme comments that have been made about it, and how I believe that it is scaring people out there in the country unnecessarily.”
“The words I’ve heard, particularly today, are ‘cut,’ ‘rip,’ ‘gut,’ ‘kill,’ ‘cruel,’ ‘stealing food,’ ‘losing coverage,’ ‘jammed through,’ ‘biggest transfer of wealth from vulnerable to wealthy people,’ ‘irresponsible’.”
“That is not the way we ought to be talking about this bill.”
READ MORE: ‘Sovereignly Appointed’: Trump Praised in Pentagon Prayer Event Led by Hegseth and Pastor
Many appear to disagree.
MSNBC columnist Michael A. Cohen, just after the bill passed Thursday morning, wrote: “What we do know about the legislation the GOP is calling the ‘One Big Beautiful Bill Act’ is genuinely terrifying.”
“What makes this situation even worse is that Republicans, from the president on down, are consistently lying about what the bill would do,” Cohen charged.
“The House Republican budget plan would eviscerate Medicaid and food assistance and shift resources toward the wealthiest Americans,” the Center for American Progress (CAP) warned ten days ago, adding that it “would implement the largest cuts to both Medicaid and the Supplemental Nutrition Assistance Program (SNAP) in history—kicking millions of Americans off their health insurance and taking food away from hungry children.”
“It would raise household electricity costs while trapping most middle-class and poor students in greater student loan debt to afford a higher education,” CAP’s Bobby Kogan, Senior Director for Federal Budget Policy wrote. “And it would make all these changes as a means to partially offset tax breaks that disproportionately go to the richest Americans, giving households in the top 0.1 percent a multihundred-thousand-dollar tax break on average while increasing deficits by trillions of dollars. Taken as a whole, the bill would add trillions of dollars to structural deficits despite these enormous cuts to critical services.”
“If enacted,” Kogan warned, “this would be the largest transfer of wealth from the poor to the rich in a single law in U.S. history.”
READ MORE: ‘Get Out of Here’: Trump Erupts, Calls for NBC Probe After Reporter Asks About Qatari Jet
“Taken as a whole, this bill would harm Americans—particularly the most vulnerable people—and leave the country worse off. It would lead to preventable deaths by taking health care away from millions of people. It would worsen food insecurity by taking food away from the hungry, particularly kids.”
“Budgets showcase our morality because they force governments to decide how to prioritize limited resources. The House Republican budget plan would shift funding away from the sick and hungry and, instead, toward the wealthiest Americans.”
U.S. Rep. Veronica Escobar (D-TX) responded to Foxx, saying, “In other words, ‘please don’t call this bill what it is or say what it does’.”
Watch the video below or at this link.
---
---
mma purple suit
May 5, 2025, edition of Fox News' Fox & Friends
BRIAN KILMEADE (CO-HOST): Let's just talk about student loans now. Your feeling about the repayments coming back and how it could really strap people.
CHARLES PAYNE (FOX BUSINESS HOST): I'm thrilled. It's — these are the most pampered, elitist -- this educated elite in this country have, I mean, they just, it's ridiculous. It's absolutely ridiculous. You know, the jobs report came out on Friday[ THEY GLOAT NOT AS BAD A PREDICTED BC OF TARIFF BS] . Alright, so unemployment for someone with a bachelor degree, the unemployment level is 2.5% percent. If you just have less than high school, it's 6%. If you have high school, it's 4%. Double the unemployment for high school grads. They make over a million dollars more in their lifetime. Their kids live in better neighborhoods. They don't face crime, poverty, worries, or concerns. Okay? There's 7.2 million job openings right now. Take one. Take one. Oh, wasn't what you studied for? Too bad. Take one. That's what the average person does. We have coddled these folks. We have — we have created a caste system in America. We have a caste system. We have put the elites above us, and we keep — how many people who have no money in the stock market, 'did you see the stock market under Trump?' You never cared about it before. You said it was for rich people. Why are you letting the elites dominate us? Why is a cab driver taking his tax money to pay your student loan? You're gonna — your kids are gonna have a better life than his kids. What the hell is wrong with this country? Pay your damn student loan. Bottom line, pay it.
:===
an 1 25
GOP proposes repealing Biden’s student debt relief to fund new tax cuts for the rich
an 12 24
According to **The World Happiness Report, the United States fell to #23 in terms of happiness earlier this year — way behind Norway, the Netherlands, Denmark, Iceland and other countries in Europe.
William S. Becker, a former U.S. Energy Department official who now serves as executive director for the Presidential Climate Action Project, lays out a variety of reasons for the United States' declining mental health in a biting op-ed published by The Hill on December 9.
Citing health care, education, inequality and other problems, Becker argues that the United States is failing its people miserably.
READ MORE:[Why Measles, Whooping Cough and worse could roar back under RFK's watch
"The U.S. is the among the wealthiest countries in the world per capita," Becker explains, "but the American people are not happy. The Constitution doesn't guarantee happiness, but the founding documents do say we all have an equal right to pursue it."
Becker points to data from the World Happiness Report, noting that "Nordic nations dominate the top 10 list" in terms of happiness.
"The happiest countries have capitalist economies and democratic governments," Becker argues, "but they provide their people with essential tools for success — tools that American conservatives brand as 'socialist.' Universal health care is one. The United States is the only high-income nation without it."
Becker continues, "Americans pay nearly four times as much for prescription drugs and higher costs for hospitalization and doctors than people in other developed countries. More than 27 million Americans still have no health insurance."
READ MORE:[Kansas Republican slams Louis DeJoy's USPS performance — to his face
The United States' health insurance crisis, Becker warns, will become even worse if the Affordable Care Act of 2010, a.k.a. Obamacare, is overturned during President-elect Donald Trump's second term.
"As of March," Becker observes, "over 45 million Americans were enrolled in Obamacare. Trump tried to kill that option during his first term and says he has 'concepts' to replace it now. According to the Congressional Budget Office, 3.4 million Americans would lose health insurance without Obamacare."
Access to "quality education," according to Becker, also plays a major role in a country's mental wellbeing — and the U.S., he says, falls way beyond Scandinavian countries in that area.
Inequality, Becker adds, is also harming Americans' mental health.
Becker observes, "Income and wealth are more equitably distributed in happy countries such as Iceland, Denmark and Norway.… In 2017, Trump's tax cuts widened the wealth gap by skewing tax policy toward the rich…. Trump has promised to lower corporate taxes even more next year…. Meanwhile, America's middle class is shrinking while its lower class expands. Nearly 38 million Americans live in poverty.
READ MORE:['America will not be made great again': McConnell received ovation after 'swipe' at Trump
*William S. Becker's full op-ed for The Hill is available at this link.
===
very good summary
an no lnx
The real reason Republicans oppose efforts to cancel student debt
Thom Hartmann April 12, 2024
I don’t get it and I’m hoping you can help me figure it out. Why do Republicans oppose President Biden’s efforts to cancel student debt?
This Tuesday, seven states, led by Missouri’s Republican Attorney General, sued the Biden administration to stop his most recent attempt to reduce student debt. In a separate lawsuit, ten other Republican-controlled states filed a separate lawsuit to try to block the same Biden effort.
The week before, somebody slipped this little gem into Maria Cantwell’s must-pass legislation reauthorizing the Federal Aviation Administration (FAA) (my inquiry to her press office was never answered):
“The Secretary, the Secretary of the Treasury, or the Attorney General may not take any action to cancel or forgive the outstanding balances, or portion of balances, on any Federal Direct Unsubsidized Stafford Loan, or otherwise modify the terms or conditions of a Federal Direct Unsubsidized Stafford Loan, made to an eligible student, except as authorized by an Act of Congress.”
READ: White rural rage: The secret political force shaping America's future
In other words, it appears, they’re trying to use the force of law to prevent President Biden from forgiving a large category of student loans. As Forbes noted:
“A proposed bill in Congress would ban mass student loan forgiveness for borrowers who attended certain professional training programs, and advocates are sounding the alarm that this could be a concerning precedent.”
But why?
— No banks are being hurt by these loans being forgiven: they’re all federal loans funded by the government. When the loan is forgiven, the debt simply vanishes: it doesn’t cost any of us a penny and isn’t hurting the big bank donors to the GOP.
— Forgiving student debt is an economic stimulus, freeing people up to buy a new home, start a new business, or just begin the family they’d been putting off because of economic uncertainty. Everybody benefits.
The closest I can come to thinking of a motive for these Republicans is that they think that Biden is essentially “buying” the votes of people whose loans were forgiven, but they’re smart enough to know that people’s politics are influenced by far more than something that simple.
Rightwingers with student debt aren’t going to start voting Democratic; if anything, they’ll take the relief and then brag about how they’re going to vote for Trump anyway.
So, what is it?
Is it that Republicans simply think having Americans in debt somehow works to their advantage? If so, how does that work?
Or is it the old, “You made the commitment, now you must follow through or society will crumble in a mess of lawlessness” argument?
When you search on the phrase “student debt forgiveness” one of the top hits that comes up is a Fox “News” article by a woman who paid off her loans in full.
“There are millions of Americans like me,” the author writes, “for whom debt forgiveness is an infuriating slap in the face after years of hard work and sacrifice. Those used to be qualities we encouraged as an American culture, and if Biden gets his way, we’ll be sending a very different message to the next generation.”
If this is the Republican’s main argument, it is, to be charitable, bullsh*t.
Forgiving student debt is not a slap at anybody; it’s righting a moral wrong inflicted on millions of Americans by Ronald Reagan and his morbidly rich Republican buddies.
Student debt is evil.
It’s a crime against our nation, hobbling opportunity and weakening our intellectual infrastructure. It maintains and in many cases rigidifies the racial and class caste systems today’s Americans inherited from our eras of slavery and indenture.
Combine this decision with the six Republicans on the Court ending affirmative action and legalizing discrimination and it’s clear this is exactly what the rightwing billionaires who put them on the Court and support their lavish vacations and lifestyles want.
They really don’t care about improving the lives of everyday Americans; their philosophy is, “I got mine; screw you.” Educated themselves, they’re now working to “pull up the ladder” behind them and thus maintain their elite status.
As history shows, this harms countries in real and measurable ways.
Every nation’s single biggest long-term asset is a well-educated populace, and student debt diminishes that.
Every other advanced democracy on the planet understands this.
That’s why student debt at the scale we have in America literally does not exist anywhere else in the rest of the developed world.
American students, in fact, are going to college for free right now in Germany, Iceland, France, Norway, Finland, Sweden, Slovenia, and the Czech Republic, because pretty much anybody can go to college for free in those countries and dozens of others.
“Student debt?” The rest of the developed world doesn’t know what you’re talking about.
Student debt also largely didn’t exist in America before the Reagan Revolution. It was created by Republicans here in the 1980s — intentionally — and if we can overcome Republican opposition, we can intentionally end it here and join the rest of the world in once again benefiting from an educated populace.
Forty years on from the Reagan Revolution, student debt has crippled three generations of young Americans: over 44 million people carry the burden, totaling a $2+ trillion drag on our economy that benefits nobody except the banks earning interest on the debt and the politicians they pay off.
But that doesn’t begin to describe the damage student debt has done to America since Reagan, in his first year as governor of California, ended free tuition at the University of California and cut state aid to that college system by 20 percent across-the-board.
After having destroyed low income Californians’ ability to get a college education in the 1970s, Reagan then took his anti-education program national as president in 1981.
When asked why he’d taken a meat-axe to higher education and was pricing college out of the reach of most Americans, he said, much like Ted Cruz might today, that college students were “too liberal” and America “should not subsidize intellectual curiosity.”
It was the 1980s version of today’s “war on woke”: Reagan hated college students.
On May 1, 1970, Governor Reagan announced that students protesting the Vietnam war across America were “brats,” “freaks” and “cowardly fascists,” adding, as The New York Times noted at the time:
“If it takes a bloodbath, let’s get it over with. No more appeasement!”
Four days later four were dead at Kent State, having been murdered by National Guard riflemen using live ammunition against anti-war protesters.
Before Reagan became president, states paid 65 percent of the costs of colleges, and federal aid covered another 15 or so percent, leaving students to cover the remaining 20 percent with their tuition payments.
It’s why when I attended college in the late 1960s — before Reagan — I could pay my tuition working a weekend job as a DJ at a local radio station and washing dishes at Bob’s Big Boy restaurant on Trowbridge Road in East Lansing.
That’s how it works — at a minimum — in most developed nations, although in many European and Asian countries college is not only free, but the government pays students a stipend to cover books and rent.
Here in America, though, the numbers are pretty much reversed from pre-1980 as a result of Reaganomics, with students now covering about 80 percent of the costs. Thus the need for student loans here in the USA.
As soon as he became president, Reagan went after federal aid to students with a fanatic fervor. Devin Fergus documented for The Washington Post how, as a result, student debt first became a thing across the United States during the early ‘80s:
“No federal program suffered deeper cuts than student aid. Spending on higher education was slashed by some 25 percent between 1980 and 1985. ... Students eligible for grant assistance freshmen year had to take out student loans to cover their second year.”
It became a mantra for conservatives, particularly in Reagan’s cabinet. Let the kids pay for their own damn “liberal educations.”
Reagan’s college educated Director of the Office of Management and Budget, David Stockman, told a reporter in 1981:
“I don’t accept the notion that the federal government has an obligation to fund generous grants to anybody who wants to go to college. It seems to me that if people want to go to college bad enough then there is opportunity and responsibility on their part to finance their way through the best way they can. … I would suggest that we could probably cut it a lot more.”
After all, cutting taxes for the morbidly rich was Reagan’s first and main priority, a position the GOP holds to this day. Cutting education could “reduce the cost of government” and thus justify more tax cuts for billionaires.
Reagan’s first Education Secretary, Terrel Bell, wrote in his memoir:
“Stockman and all the true believers identified all the drag and drain on the economy with the ‘tax-eaters’: people on welfare, those drawing unemployment insurance, students on loans and grants, the elderly bleeding the public purse with Medicare, the poor exploiting Medicaid.”
Reagan’s next Education Secretary, William Bennett, was even more blunt about how America should deal with the “problem” of uneducated people who can’t afford college, particularly if they were African American:
“I do know that it’s true that if you wanted to reduce crime,” Bennett famously said, “you could -- if that were your sole purpose, you could abort every black baby in this country, and your crime rate would go down.”
These doctrines became an article of faith across the GOP and remain so to this day, as we saw this week with the Republicans suing to stop Biden from forgiving any more loans.
Reagan’s OMB Director David Stockman told Congress that students were “tax eaters … [and] a drain and drag on the American economy.” Student aid, he said, “isn’t a proper obligation of the taxpayer.”
This was where, when, and how today’s student debt crisis was kicked off in 1981.
Before Reagan, though, America had a different perspective.
Both my father and my wife Louise’s father served in the military during World War II and both went to college on the GI Bill. My dad dropped out after two years and went to work in a steel plant because mom got pregnant with me; Louise’s dad, who’d grown up dirt poor, went all the way for his law degree and ended up as Assistant Attorney General for the State of Michigan.
They were two among almost 8 million young men and women who not only got free tuition from the 1944 GI Bill but also received a stipend to pay for room, board, and books. And the result — the return on our government’s investment in those 8 million educations — was substantial.
The best book on that time and subject is Edward Humes’ Over Here: How the GI Bill Transformed the American Dream, summarized by Mary Paulsell for the Columbia Daily Tribune:
“[That] groundbreaking legislation gave our nation 14 Nobel Prize winners, three Supreme Court justices, three presidents, 12 senators, 24 Pulitzer Prize winners, 238,000 teachers, 91,000 scientists, 67,000 doctors, 450,000 engineers, 240,000 accountants, 17,000 journalists, 22,000 dentists and millions of lawyers, nurses, artists, actors, writers, pilots and entrepreneurs.”
Free education literally built America’s middle class.
When people have an education, they not only raise the competence and vitality of a nation; they also earn more money, which stimulates the economy. Because they earn more, they pay more in taxes, which helps pay back the government for the cost of that education.
In 1952 dollars, the GI Bill’s educational benefit cost the nation $7 billion. The increased economic output over the next 40 years that could be traced directly to that educational cost was $35.6 billion, and the extra taxes received from those higher-wage-earners was $12.8 billion, both in 1952 dollars.
In other words, the US government invested $7 billion and got a $48.4 billion return on that investment, about a $7 return for every $1 invested.
In addition, that educated workforce made it possible for America to lead the world in innovation, R&D, and new business development for three generations.
We invented the transistor, the integrated circuit, the internet, new generations of miracle drugs, sent men to the moon and reshaped science.
Presidents Thomas Jefferson and Abraham Lincoln knew this simple concept that seems so hard for Reagan and generations of Republicans since to understand: when you invest in young people, you’re investing in your nation.
Jefferson founded the University of Virginia as a 100% tuition-free school; it was one of his three proudest achievements, ranking higher on the epitaph he wrote for his own tombstone than his having been both president and vice president.
Lincoln was equally proud of the free and low-tuition colleges he started. As the state of North Dakota notes:
“Lincoln signed the Morrill Act on July 2, 1862, giving each state a minimum of 90,000 acres of land to sell, to establish colleges of engineering, agriculture, and military science. … Proceeds from the sale of these lands were to be invested in a perpetual endowment fund which would provide support for colleges of agriculture and mechanical arts in each of the states.”
Fully 76 free or very-low-tuition state colleges were started because of Lincoln’s effort and since have educated millions of Americans including my mom, who graduated from land-grant Michigan State University in the 1940s, having easily paid her minimal tuition working as a summer lifeguard in her home town of Charlevoix, Michigan.
Every other developed country in the world knows this, too: student debt is rare or even nonexistent in most western democracies. Not only is college free or close to free in almost all of the developed world; many countries even offer a stipend for monthly expenses like our GI Bill did back in the day.
As mentioned earlier, thousands of American students are currently studying in Germany at the moment for free. Hundreds of thousands of American students are also getting free college educations right now in Iceland, Denmark, Norway, Finland, Sweden, Slovenia, and the Czech Republic, among others.
Republican policies of starving education and cranking up student debt have made US banks a lot of money, but they’ve cut America’s scientific leadership in the world and, since the institution of trickle-down Reaganomics, stopped three generations of young people from starting businesses, having families, and buying homes.
The damage to working class and poor Americans, both economic and human, is devastating. Even worse for America, it’s a double challenge for minorities.
And now Republicans are telling our young people who weren’t members of the “Lucky Sperm Club” with wealthy or legacy parents that they’re simply out of luck. And, as noted, the GOP is celebrating.
Which raises the question: how gullible do these Republicans think their voters are?
Marjorie Taylor Greene wrote on Twitter that student loan forgiveness was “completely unfair.” She’s the same Republican congresswoman who had $183,504 in PPP loans forgiven, and happily banked that government money without a complaint.
Republican members of Congress, in fact, seem to be among those in the front of the debt-forgiveness line with their hands out, even as billionaires bankroll their campaigns and backstop their lifestyles.
As the Center for American Progress noted on Twitter in response to a GOP tweet whining that, “If you take out a loan, you pay it back”:
Member —— Amount in PPP Loans Forgiven
Matt Gaetz (R-FL) - $476,000
Marjorie Taylor Greene - $183,504
Greg Pence (R-IN) - $79,441
Vern Buchanan (R-FL) - $2,800,000
Kevin Hern (R-OK) - $1,070,000
Roger Williams (R-TX) - $1,430,000
Brett Guthrie (R-KY) - $4,300,000
Ralph Norman (R-SC) $306,250
Ralph Abraham (R-AL) - $38,000
Mike Kelly (R-PA) - $974,100
Vicki Hartzler (R-MO) - $451,200
Markwayne Mullin (R-OK) - $988,700
Carol Miller (R-WV) - $3,100,000
Every single one of these Republican members of Congress has echoed Greene’s criticism of student debt relief or supported efforts to block it. Every single one also eagerly welcomed forgiveness of their Covid-era debts.
So, yeah, Republicans are complete hypocrites about forgiving loan debt, in addition to pushing policies that actually hurt our nation (not to mention the generations coming up).
President Biden has already forgiven over $143 billion in student debt and this week proposed to extend that debt relief from the 4 million he has reached so far to as many as 20 million people. It’s a great start, but if we really want America to soar, we need to go way beyond that.
Just like for-profit health insurance (which was prohibited in most states before the Reagan Revolution: the companies had to be organized as nonprofits), student loans are a malignancy attached to our republic by Republicans trying to increase profits for their donors while extracting more and more cash from working-class families.
If Democrats can regain control of the House and hold the Senate and White House this fall, they must not only zero-out existing student debt across our nation but revive the post-war government support for education — from Jefferson and Lincoln to the GI Bill and college subsidies — that the Reagan, Bush, Bush, and Trump administrations have destroyed.
Then, and only then, can the true “making America great again” begin.
READ: White rural rage: The secret political force shaping America's future
FROM YOUR SITE ARTICLES
Is the Near-Trillion-Dollar Student Loan Bubble About to Pop? ›
Don’t give Trump a 2nd chance to destroy American democracy ›
Amy Coney Barrett uses bizarre analogy of babysitter and amusement park in student loan opinion ›
Sinema got $27K from student loan industry after helping GOP kill Biden’s debt forgiveness plan ›
Biden could cancel student debt for up to 10 million more Americans before Election Day
RELATED ARTICLES AROUND THE WEB
President Joe Biden Outlines New Plans to Deliver Student Debt ... ›
Student Loan Forgiveness | Federal Student Aid ›
FACT SHEET: President Biden Cancels Student Debt for more than ... ›
The Biden-Harris Administration's Student Debt Relief Plan Explained ›
---
---
---
---
1123
---
an 7 23
...During the White House press conference following the court's decision, Cardona said, "Today, the court substituted itself for congress. It’s outrageous to me that Republicans in Congress and state offices fought so hard against a program that would have helped millions of their own constituents.They had no problem handing trillion dollar tax cuts to big corporations and the super-wealthy, and many had no problems accepting millions of dollars in forgiven pandemic loans.”
He continued, "Senator Markwayne Mullin from Oklahoma had more than $1.4 million in pandemic loans forgiven. He represents 489,000 eligible borrowers that were turned down today. Representative Brett Guthrie from Kentucky had more than $4.4 million forgiven. He represents more than 90,000 eligible borrowers that were turned down today. Representative Marjorie Taylor Greene from Georgia had more than $180,000 forgiven. She represents more than 91,800 borrowers who were turned down today."
---
an 6 23
Amy Coney Barrett was one of the conservative justices who struck down Biden's loan forgiveness plan, but her explanation as to why included talk of babysitters and amusement parks left some people scratching their heads in confusion.
Barrett used the opinion, which ruled that the Biden administration didn't have the authority to authorize the forgiveness, to push for the "major questions doctrine," according to CNN.
"The so-called major questions doctrine says that executive branch agencies only have authority to take aggressive unilateral action of significant political or economic importance if Congress explicitly gives it such power," the news network reported. "The Supreme Court’s use of the major questions doctrine to throw out Biden’s loan forgiveness program struck a nerve that went beyond educational policy – with the conservative justices and liberal justices sparring over how the controversial legal theory that has been used, with increasing frequency, to strike down unilateral acts of executive branch authority."
In order to explain how this particular legal theory comes into play with student loans, Barrett took us all back to elementary school with a unique analogy about a babysitter spending the parents' money on kids she's watching.
According to CNN's report:
"A second hypothetical centered on a babysitter who took the kids to an amusement park for the weekend, having been given a parent’s credit card and told: 'Make sure the kids have fun,'" CNN reported. "Emboldened, the concurring babysitter takes the kids on a road trip to an amusement park, where they spend two days on rollercoasters and one night in a hotel."
This, Barrett suggests, is the equivalent of the government cancelling those student loans. Because the law didn't give explicit authority to do so, she reasons, it would be unreasonable to assume it has that power.
---
---
BRIEF OF SENATOR MARSHA BLACKBURN
AND 42 OTHER MEMBERS OF THE UNITED
STATES SENATE AS AMICI CURIAE IN
SUPPORT OF RESPONDENTS
BRIAN A. KULP
DECHERT LLP
CIRA CENTRE
2929 Arch Street
Philadelphia, PA 19104
STEVEN A. ENGEL
Counsel of Record
MICHAEL H. MCGINLEY
JUSTIN W. AIMONETTI
DECHERT LLP
1900 K Street, NW
Washington, DC 20006
(202) 261-3369
steven.engel@dechert.com
LIST OF AMICI CURIAE
Senator John Barrasso
Senator Marsha Blackburn
Senator John Boozman
Senator Mike Braun
Senator Katie Boyd Britt
Senator Ted Budd
Senator Bill Cassidy
Senator John Cornyn
Senator Tom Cotton
Senator Kevin Cramer
Senator Mike Crapo
Senator Ted Cruz
Senator Steve Daines
Senator Joni Ernst
Senator Deb Fischer
Senator Lindsey Graham
Senator Chuck Grassley
Senator Bill Hagerty
Senator Josh Hawley
Senator John Hoeven
Senator Cindy Hyde-Smith
Senator Ron Johnson
Senator John Kennedy
Senator James Lankford
Senator Mike Lee
Senator Cynthia M. Lummis
2a
Senator Roger Marshall
Senator Mitch McConnell
Senator Jerry Moran
Senator Markwayne Mullin
Senator Pete Ricketts
Senator James E. Risch
Senator Mitt Romney
Senator Mike Rounds
Senator Marco Rubio
Senator Rick Scott
Senator Tim Scott
Senator Dan Sullivan
Senator John Thune
Senator Thom Tillis
Senator Tommy Tuberville
Senator Roger F. Wicker
Senator Todd Young
---
MICHAEL BOOS WILLIAM J. OLSON*
DANIEL H. JORJANI JEREMIAH L. MORGAN
CITIZENS UNITED ROBERT J. OLSON
1006 Penn. Ave. S.E. WILLIAM J. OLSON, P.C.
Washington, DC 20003 370 Maple Ave. W., Ste. 4
(202) 547-5420 Vienna, VA 22180
(703) 356-5070
RICK BOYER wjo@mindspring.com
INTEGRITY LAW FIRM *Counsel of Record
P.O. Box 10953
Lynchburg, VA 24506 Attorneys for Amici Curiae
(434) 401-2093 February 3, 2023
---
Daniel R. Suhr
Counsel of Record
James J. McQuaid
LIBERTY JUSTICE CENTER
440 N. Wells Street, Suite 200
Chicago, Illinois 60654
dsuhr@libertyjusticecenter.org
312-637-2280
---
JESSICA HART STEINMANN
CRAIG W. TRAINOR*
RACHEL JAG
JASE PANEBIANCO
AMERICA FIRST POLICY INSTITUTE
CONSTITUTIONAL LITIGATION
PARTNERSHIP
1001 Pennsylvania Avenue NW,
Suite 530
Washington, DC 20004
jsteinmann@
americafirstpolicy.com
ctrainor@americafirstpolicy.com
rjag@americafirstpolicy.com
jpanebianco@
americafirstpolicy.com
(202) 684-8361
*Counsel of Record
Counsel for Amicus Curiae
America First Policy Institute
---
STEWART L. WHITSON Counsel of Record DAVID CRAIG RYAN YOUNG
THE FOUNDATION FOR GOVERNMENT ACCOUNTABILITY
15275 Collier Blvd., Ste. 201 Naples, FL 34119 (239) 244-8808 stewart@theFGA.org
---
Michael Pepson J. Marc Wheat
Counsel of Record General Counsel
Casey Mattox ADVANCING AMERICAN
Cynthia Fleming Crawford FREEDOM, INC.
AMERICANS FOR PROSPERITY 801 Pennsylvania Avenue, N.W.,
FOUNDATION Suite 930
1310 N. Courthouse Road, Washington, D.C. 20004
Ste. 700 (202) 780-4848
Arlington, VA 22201 MWheat@advancingamericanfreedom.com
(571) 329-4529
mpepson@afphq.org
Counsel for Amici Curiae February 1, 2
---
During his forty-year career representing California’s seventh and eleventh congressional districts, Representative George Millerfrequently engaged with issues of higher education policy. Indeed, he was one of the chief architects of the HEROES Act of 2003, the legislation that authorized the targeted debt relief plan at issue in this case. He was a co-sponsor of the bill that became the HEROES Act of 2003, H.R. 1412, 108th Cong., as well as related legislation in 2001, see H.R. 3086, 107th Cong.; in 2005, see H.R. 2132, 109th Cong.; and in 2007, H.R. 3625, 110th Cong. As a former member and chairman of the House Education and Labor Committee, he also has extensive expertise concerning the U.S. Department of Education and its role in managing the federal government’s portfolio of student loans. Accordingly, he has an interest in this case
ELIZABETH B. WYDRA BRIANNE J. GOROD* SMITA GHOSH J. ALEXANDER ROWELL CONSTITUTIONAL ACCOUNTABILITY CENTER1200 18th Street NW, Suite 501 Washington, D.C. 20036 (202) 296-6889 brianne@theusconstitution.org
BRIEF OF LEGAL SCHOLARS AS AMICI
CURIAE IN SUPPORT OF PETITIONERS
INTERESTS OF THE AMICI CURIAE1
Amici curiae are professors at law schools
throughout the United States. Amici’s expertise encompasses student-financial-assistance programs under Title IV of the Higher Education Act of 1965, consumer finance, administrative and constitutional law,
modes of statutory interpretation, and the development of the major questions doctrine. Amici have a
strong interest in assisting this Court in resolving
questions of law that go to the core of their professional expertise and scholarship, namely, the scope of
the Department of Education’s authority to provide
relief to borrowers and the development of this Court’s
statutory interpretation methodology, particularly in
the context of its precedent concerning the major
questions doctrine. Amici are:
• William Araiza, Stanley A. August Professor
of Law, Brooklyn Law School
• John R. Brooks, Professor of Law, Fordham
University School of Law
• Matthew Bruckner, Associate Professor of
Law, Howard University School of Law
• James J. Brudney, Joseph Crowley Chair in
Labor and Employment Law, Fordham University School of Law
1 Pursuant to Rule 37.6, no party’s counsel authored this brief
in whole or in part, no party or party’s counsel contributed money
intended to fund this brief, and no person other than amici, their
members, and their counsel contributed money to fund this brief.
2
• Erwin Chemerinsky,Dean and Jesse H.
Choper Distinguished Professor of Law, University of California, Berkeley School of Law
• Kurt Eggert, Professor and Director, Alona
Cortese Elder Law Center, Chapman University Fowler School of Law
• Kate Sablosky Elengold, Assistant Professor
of Law and Director, Consumer Financial
Transactions Clinic, University of North Carolina School of Law
• Kathleen C. Engel, Research Professor of
Law, Suffolk University Law School
• Pamela Foohey, Professor of Law, Benjamin
N. Cardozo School of Law
• Jonathan Glater, Professor, University of California, Berkeley School of Law
• Luke Herrine, Assistant Professor of Law,
University of Alabama School of Law
• Dalié Jiménez, Professor of Law and Director,
Student Loan Law Initiative, University of
California, Irvine School of Law
• Creola Johnson, President’s Club Professor of
Law, Ohio State University Moritz College of
Law
• Angela K. Littwin, Ronald D. Krist Professor
of Law, University of Texas at Austin School
of Law
• Jeffrey Lubbers, Professor of Practice in Administrative Law, American University
Washington College of Law
3
• Cathy Lesser Mansfield, Senior Instructor in
Law, Case Western Reserve University School
of Law
• Chrystin Ondersma, Professor of Law and
Judge Morris Stern Scholar, Rutgers Law
School
• Christopher L. Peterson, John J. Flynn Endowed Professor of Law, University of Utah
S.J. Quinney College of Law
• Christopher J. Ryan, Jr., Associate Professor
of Law, University of Louisville Brandeis
School of Law
• Peter M. Shane, Jacob E. Davis and Jacob. E.
Davis II Chair in Law, Ohio State University
Moritz College of Law Emeritus, & Distinguished Scholar in Residence and Adjunct
Professor of Law, New York University School
of Law
• Peter Strauss, Betts Professor Emeritus of
Law, Columbia Law School
• David C. Vladeck, A.B. Chettle, Jr., Professor
of Law, Georgetown University Law Center
• Alan White, Professor, City University of New
York School of Law
• Lauren E. Willis, Professor of Law, LMU Loyola Law School
INTRODUCTION AND
SUMMARY OF ARGUMENT
Respectfully submitted,
/s/ Melissa A. Holyoak
SEAN D. REYES
Attorney General of Utah
MELISSA A. HOLYOAK*
Solicitor General
TIM LONGFIELD
Special Assistant Solicitor General
Office of the Attorney General
350 N. State Street, Ste. 230
P.O. Box 142320
Salt Lake City, UT 84114
(801) 538-9600
melissaholyoak@agutah.gov
ADDITIONAL COUNSEL
Counsel for Amici States
STEVE MARSHALL
Attorney General
State of Alabama
TREG R. TAYLOR
Attorney General
State of Alaska
MARK BRNOVICH
Attorney General
State of Arizona
ASHLEY MOODY
Attorney General
State of Florida
CHRISTOPHER M. CARR
Attorney General
State of Georgia
THEODORE E. ROKITA
Attorney General
State of Indiana
JEFF LANDRY
Attorney General
State of Louisiana
LYNN FITCH
Attorney General
State of Mississippi
AUSTIN KNUDSEN
Attorney General
State of Montana
JOHN M. FORMELLA
Attorney General
State of New Hampshire
DREW WRIGLEY
Attorney General
State of North Dakota
JOHN M. O’CONNOR
Attorney General
State of Oklahoma
KEN PAXTON
Attorney General
State of Texas
PATRICK MORRISEY
Attorney General
State of West Virginia
BRIDGET HILL
Attorney General
State of Wyoming
Michael Pepson
Counsel of Record
Casey Mattox
Cynthia Fleming Crawford
AMERICANS FOR PROSPERITY FOUNDATION
1310 N. Courthouse Road, Ste. 700
Arlington, VA 22201
571.329.4529
mpepson@afphq.org
November 23, 2022 Attorneys for Amicus Curiae
1
Americans for Prosperity Foundation (AFPF) respectfully moves this Court
under Rule 37.2 for leave to file the enclosed brief as amicus curiae in support of
Respondent States’ Opposition to Application to Vacate the Injunction Entered by the
United States Court of Appeals for the Eighth Circuit, (i) without 10 day’s advance
notice to the parties of amicus’s intent to file as ordinarily required by Sup. Ct. R.
37.2(a) and (ii) in an unbound format on 8½-by-11-inch paper rather than in booklet
form.
Respondent States consent to the filing of this brief; Federal Applicants take
no position on AFPF’s motion for leave. The Federal parties filed their application on
Friday, November 18, 2022. As this Court has called for a response by noon EST
Wednesday, November 23, 2022, it was not feasible to provide 10 days’ notice to the
parties.
AFPF participated as amicus curiae below. See App. 1a (listing amici on behalf
of States). As set forth in the enclosed brief, AFPF has a strong interest in the
separation of powers issues that underlie this case, as well as the fiscal impacts of
Applicants’ actions. AFPF further respectfully submits that the amicus brief includes
relevant material not brought to the attention of the Court by the parties that may
be of considerable assistance to the Court. See Sup. Ct. R. 37.1.
AFPF therefore respectfully seeks leave to file this brief in support of
Respondent States’ Opposition to the Federal parties’ Application.
CONCLUSION
This Court should grant amicus curiae AFPF leave to file the enclosed brief.
Amici Curiae are six veterans’ organizations
committed to policy advocacy for—and the provision of
direct services to—U.S. military veterans and their
families. Many have filed amicus briefs in other litigation affecting servicemembers. This case is
important to amici because veteran student debt affects them, their members, and the constituencies
they serve.
Minority Veterans of America (“MVA”) is a nationwide, non-partisan, nonprofit organization that
works to foster belonging and advance equity for the
minority veteran community, many of whom have felt
marginalized, underserved, and underrepresented
both during their time in military service and afterward. MVA aims to transform the narrative of the
American veteran by building an interconnected community, fostering greater understanding of its
members’ identities, and serving minority veterans
through the development of targeted programming
and advocacy. MVA understands that student debt affects minority veterans and seeks to reduce these
obstacles to veteran success.
...The Military and Veteran Women’s Coalition is
a national group of organizations that work collaboratively to serve and support U.S. active duty, Guard,
Reserve, veteran, and retired servicewomen by uniting and elevating their voices to influence policy and
improve their well-being. The Coalition’s goal is for
military women to be fully integrated, equally respected, and equally supported members of the
military and veteran community. The Military and
Veteran Women’s Coalition has a strong interest in
ensuring its constituents are not disadvantaged by debilitating student debt as a result of their service or
their status as women.
..The Center for Law and Military Policy
(“CLMP”) is a nonprofit think tank dedicated to
strengthening legal protections for those who serve
our nation in uniform. CLMP conducts research and
produces educational material in order to meet this
goal. This matter is of particular interest to CLMP,
which seeks to ensure that vulnerable military personnel are not ignored, financially exploited, or turned
into second-class citizens due to the financial hardships associated with student debt.
Combat Sexual Assault (“CSA”) is a nonprofit
organization focused on advocacy and education for
survivors of military sexual assault. CSA’s services
empower survivors of military sexual trauma by
...TAVA also helps to educate
the Department of Veterans Affairs and the Department of Defense regarding fair and equal treatment of
transgender and transsexual individuals. TAVA
seeks to ensure its constituents specifically—and veterans broadly—are not uniquely disadvantaged by
crushing student debt.
Protect Our Defenders (“POD”) honors, supports, and gives voice to the brave servicemembers
and veterans who have been sexually assaulted during
service, and seeks to reform the systems that consistently fail them. In light of its advocacy on behalf of
veterans faced with systemic challenges and inequalities, POD has a vital interest in ensuring veteran
student debt does no
HAMILTON LINCOLN LAW INSTITUTE
Theodore H. Frank
1629 K Street, NW, Suite 300
Washington, DC 20006
(703) 203-3848
Counsel for Amicus Curiae
Hamilton Lincoln Law Institute
1
Motion for Leave to File Brief as Amicus Curiae
Hamilton Lincoln Law Institute (“HLLI”) moves the Court for leave
to file the enclosed brief as amici curiae in support of respondents and in
opposition to the United States’ application to vacate the Eighth Circuit’s
injunction (i) without 10 days’ notice to the parties of amici’s intent to file
as ordinarily required by Sup. Ct. R. 37.2(a), and (ii) in an unbound
format on 8½-by-11-inch paper rather than in booklet form. The
respondents do not oppose the filing of this brief, and the United States
takes no position.
The United States filed its application on November 18, 2022. The
same day, Justice Kavanaugh requested a response to the application by
noon (EST), November 23, 2022. In light of the expedited briefing
schedule, it was not feasible to provide 10 days’ notice to the parties. And
the compressed timeframe prevented HLLI from having the brief
finalized in sufficient time to allow it to be printed and filed in booklet
form.
As set forth in the enclosed brief, HLLI has a strong interest in the
outcome of this application. Amicus curiae HLLI is a public-interest law
firm committed to, among other thingsamong other things, defending the
constitutional separation of powers and principles of limited government
against executive-branch abuse. This case not only presents critical
separation-of-powers issues, but has personal resonance for the many...
an 6 23
some ppl say BS:
Bernie Sanders and Rep. Pramila Jayapal introduced the “College For All Act” in tandem with Sanders and Rep. Barbara Lee reintroducing the “Tax on Wall Street Speculation Act”this past week. The first bill would eliminate tuition and fees at four-year higher education institutions for people and families making under $125,000/7 a year. It would also make community college tuition, and fees, entirely free to everyone.
The plan would also help Americans to refinance existing student loans at considerably lower interest rates while ending the practice of the federal government turning a profit off of student assistance. The second bill, originally introducedin 2021 and based on a similar bill Sanders put forward in 2008 as a response to the Wall Street bailouts connected to the housing crisis, looks to generate the revenues that pay for this plan.
Republicans, disagreeing with the concepts of free college and student debt relief, have offered up status quo plans while trying to push people away from going to colleges and toward trade schools. You can read Sen. Bill Cassidy’s worthless bill here. The right-wing media is now ginning up anti-student loan relief sentiment, directing Americans’ ire not at the predatory loan system or exorbitant higher education costs but at the students themselves. This means framing the conversation as one about Americans being taxed to pay for students who can’t pay back their loans.
While walking to his office, Sanders was asked byFox News Business correspondent Hillary Vaughn, “Is it really free if you're raising taxes to pay for it?” Sanders gave a very short and sweet masterclass on messaging:
“Well, given the fact that we have the billionaire class paying a lower tax rate than working families, I think it's appropriate that the wealthiest people in this country start paying their fair share of taxes.”
Vaughn attempted what passes for a hard-hitting followup at Fox: “People say that the Wall Street tax would hit average Americans saving for retirement.”
Sanders stopped to shut this bullshit down: “What people say that? People on Wall Street. Thank you
an 11 22 ah
https://www.alternet.org/2022/11/clearly-no-jurisdiction-law-professor-rips-trump-judges-ruling-on-bidens-student-debt-relief-program/
Two years have passed since former President Donald Trump was decisively voted out of office, yet his influence on the federal judiciary remains. That includes not only the three socially conservative justices Trump appointed to the U.S. Supreme Court (Brett Kavanaugh, Neil Gorsuch and Amy Coney Barrett), but also, all the lower federal court justices Trump appointed with the help of Sen. Mitch McConnell.
One of them was Judge Mark Pittman, a federal district judge in Texas. Pittman has ordered President Joe Biden’s program for forgiving student loan debt to be discontinued. And according to legal expert Laurence H. Tribe, the Trump-appointed judge has seriously overreached.
In an article published by Verdict Justia on November 14, the Harvard Law School professor notes that Biden’s program “was promulgated by the U.S. Department of Education pursuant to congressional legislation.”
“Judge Pittman held the program null and void and ordered it dismantled,” Tribe observes. “In so doing, he became the first federal judge to conclude that he had jurisdiction to review the program’s validity at the behest of those its opponents had recruited to challenge it. And he went much farther than the U.S. Court of Appeals for the Eighth Circuit had gone when it issued an emergency order temporarily directing the Department to stop processing loan discharges while it reviewed a federal district court’s decision that it lacked jurisdiction to consider the program’s legality.”
Tribe continues, “The district court had concluded that the plaintiffs, six Republican-led states, lacked ‘standing’ to pursue their challenge to the program because they could not show that they were genuinely harmed by it. In contrast, Judge Pittman’s decree permanently ‘vacating’ the program in its entirety left the (Biden) Administration no choice but to stop taking loan forgiveness applications altogether on its official website while the Justice Department filed an immediate appeal to the U.S. Court of Appeals for the Fifth Circuit.”
According to Tribe, Pittman “clearly had no jurisdiction even to hear the merits of the plaintiffs’ claims, much less to dismantle the program.”
“By doing so, he usurped the power of both Congress and the executive branch,” Tribe explains. “The central defining feature of the federal judicial power which flows from Article III of the Constitution is that the courts Congress establishes pursuant to that article may exercise only the power to resolve actual ‘Cases’ and ‘Controversies.’ This ‘cases and controversies’ requirement, as explained by the Supreme Court from its inception, entails the fundamental limitation that the Article III ‘judicial power’ is available only to redress concrete injuries suffered by those who invoke it.”
READ MORE:**'They got nothin': Elizabeth Warren torches Republicans for fighting against student debt relief**
Tribe argues that Pittman’s ruling was inconsistent with what the U.S. Constitution says about “governmental power.”
“Judge Pittman stepped completely outside this judicial role as constrained by the Supreme Court’s standing doctrine,” Tribe writes. “He thereby not only injured the many lower-income and middle-income borrowers who have justifiably relied on the (Biden) Administration’s program of debt relief, but also — and more importantly — further undermined the already frayed rule of law in the United States and contributed to the erosion of the indispensable role of the independent federal judiciary in preserving our constitutional republic.”
Tribe adds, “To add insult to injury, Judge Pittman adorned his adventure in what conservatives used to decry as ‘legislating from the bench’ by righteously insisting that he was just ‘interpreting the law’ as a ‘mere machine’ — an image of bloodless passivity that makes Chief Justice John Roberts’ description of a judge’s role as merely that of an umpire, calling balls and strikes, appear downright activist.”
READ MORE:**Red states are lining up to stop Biden’s student loan forgiveness plan**
comm dr
Justice Department filed an appeal Thursday after a Trump-appointed federal judge in Texas blocked the Biden administration's student debt cancellation program nationwide, declaring it "unlawful" on grounds that legal experts criticized as laughable.
The 26-page ruling by Mark Pittman of the U.S. District Court for the Northern District of Texas finds that the two plaintiffs who brought the case with the backing of the Job Creators Network Foundation—an affiliate of a right-wing, billionaire-funded business trade group—have standing to sue over the debt cancellation program because the Biden administration didn't allow a public comment period before moving ahead with the plan.
A public comment period is not required under the legal authority the Biden administration used to justify the cancellation of $10,000 to $20,000 in federal student loan debt for most borrowers, but Pittman noted that the plaintiffs dispute that legal authority.
"Because the court must 'assume, for purposes of the standing analysis, that [plaintiffs are] correct on the merits of [their] claim that the [program] was promulgated in violation of the [Administrative Procedure Act],' plaintiffs have successfully alleged the deprivation of a procedural right," wrote Pittman, a founding member of the Tarrant County Federalist Society.
Neither Myra Brown nor Alexander Taylor, the two plaintiffs in the case, are eligible for full student debt relief under the Biden administration's plan—Brown has commercial loans and Taylor did not receive a Pell Grant. The Intercept reported earlier this week that Brown "has herself been a beneficiary of debt cancellation, in the form of a Paycheck Protection Program business loan worth over twice the maximum amount covered under Biden's program."
Pittman's reasoning conflicts with rulings in previous cases in which judges—including one appointed by George W. Bush—dismissed lawsuits against the debt cancellation plan over plaintiffs' failure to demonstrate standing, which requires them to prove direct injury or harm.[twt]
"Today, a federal judge conspired with right-wing politicians and corrupt corporations to block life-changing student debt relief for tens of millions of families," said Mike Pierce, executive director of the Student Borrower Protection Center (SBPC). "In courts across the country, dark money-backed legal challenges are growing like weeds. The Biden administration must use this decision as an opportunity to make it clear that the student loan system will remain shut off as long as these partisan legal challenges persist. Student loan borrowers should never be sacrificed as pawns in Republicans' political games."
Shortly after Pittman handed down his ruling, White House Press Secretary Karine Jean-Pierre said in a statement that "we strongly disagree with the District Court's ruling on our student debt relief program and the Department of Justice has filed an appeal."
"The president and this administration are determined to help working and middle-class Americans get back on their feet, while our opponents—backed by extreme Republican special interests—sued to block millions of Americans from getting much-needed relief," said Jean-Pierre.
"For the 26 million borrowers who have already given the Department of Education the necessary information to be considered for debt relief—16 million of whom have already been approved for relief—the department will hold onto their information so it can quickly process their relief once we prevail in court," she added.....
~ cruz?
https://www.alternet.org/2022/10/amy-coney-barrett-student-loan/
same case as cruz?
an 11 22
...Justice Amy Coney Barrett again decided, late Friday afternoon, to not weigh in on the Biden plan. Barrett "denied an emergency application brought by the Pacific Legal Foundation to block federal student loan forgiveness," CNBC reports.
Unfortunately for those 16 million Americans, a GOP lawsuit, at least temporarily, is causing the forgiveness to be put on hold.
Insider on Thursday reported, "the 8th Circuit Court of Appeals temporarily paused the relief, in response to a lawsuit filed by six Republican-led states who argued the policy would hurt their states' tax revenues, along with those of loan company MOHELA."...
an 10 22
President Joe Biden’s relief plan for student loan debt is facing yet another lawsuit with a legal challenge from an organization in Wisconsin.
According to The Washington Post, the Brown County Taxpayers Association in Wisconsin, alleges that the plan includes “improper racial motive” and "violates the 14th Amendment’s equal protection clause."
“By creating and implementing a federal program with an improper racial motive, Defendants violated the Constitution’s guarantee of equal protection of the laws, which among other things, prohibits federal spending based on race,” states the lawsuit, per documents obtained by the news outlet.
READ MORE: 'Just kidding': Biden Administration yanks student debt relief for millions as GOP states sue
However, the White House insists the plan, which is set to provide up to $20,000 in student loan debt relief for American borrows, will “advance racial equity.”
“Black students are more likely to have to borrow for school and more likely to take out larger loans,” the White House's student loan debt relief fact sheet states. It also adds that “Black borrowers are twice as likely to have received Pell Grants compared to their white peers.”
Per HuffPost, The White House also cited "an Urban Institute study that showed tailoring measures to graduates who were awarded Pell Grants would help make progress on racial equity."
The latest reports about the legal challenge in Wisconsin come days after White House press secretary Karine Jean-Pierre was asked whether or not the flurry of lawsuits will cause delays for student loan debt relief.
On Tuesday, October 4, Jean-Pierre addressed the situation while speaking to reporters. While the press secretary did not offer a definitive answer regarding the possibility of delays, she did offer a critical assessment of Republicans fighting to stop Americans from receiving financial relief.
“It’s a shame that you have Republicans out there — Republican groups, Republican states — that are trying to stop Americans from getting a little bit of a breathing room, a little bit of a break,” Jean-Pierre told reporters.
Biden's student loan debt relief initiative is poised to help reduce the financial strain for more than 40 million Americans.
READ MORE: Red states are lining up to stop Biden’s student loan forgiveness plan
Six red states —
Arkansas,
- SEPTEMBER 29, 2022 HTTPS://ARKANSASAG.GOV/
Says, ‘Biden’s unlawful political play puts the self-wrought college-loan debt on the backs of millions of hardworking Americans’
LITTLE ROCK— Arkansas Attorney General Leslie Rutledge today announced a lawsuit against President Joe Biden, Secretary of Education Miguel Cardona and the U.S. Department of Education forviolating federal law when the Biden Administration attempted to categorically cancel student loan debt in August. The suit alleges that Biden violated federal law, the constitutional principle of separation of powers and the Administrative Procedure Actwhen he skirted congressional authority to implement this policy.
“President Biden’s unlawful political play puts the self-wrought college-loan debt on the backs of millions of hardworking Americans who are struggling to pay their utility bills and home loans in the midst of Biden’s inflation,” said Attorney General Leslie Rutledge. “President Biden does not have the power to arbitrarily erase the college debt of adults who chose to take out those loans.”
The lawsuit highlights that President Biden knew he did not have the proper authority to authorize this type of executive action, which is why he attempted to work with Congress to find a legitimate and legal solution to the student loan crisis. After Congress routinely failed to pass legislation addressing the issue, Biden attempted to unilaterally act far beyond the authority granted to him by the Constitution. This action will result in approximately half a trillion dollars in losses to the federal treasury and contribute to the already rampant inflation the nation is experiencing.
The Democrat Speaker of the House, Nancy Pelosi, summarized it best when she said, “people think the President of the United States has the power for debt forgiveness. He does not.”
Joining Arkansas in the suit are the states of: Iowa, Kansas, Missouri, Nebraska and South Carolina.
:{About Attorney General Tom Miller | Iowa Attorney General:(style="margin:0px;padding:0px;border:0px;font-style:inherit;font-variant:inherit;font-weight:inherit;font-stretch:inherit;vertical-align:top;display:inline-block;max-width:100%;overflow:hidden;text-overflow:ellipsis;white-space:nowrap"):}:
Attorney General Tom Miller is serving in his 10th four-year term as Attorney General of Iowa. He is the longest currently serving attorney general in the nation. He was born in Dubuque on August 11, 1944, the son of the late Elmer and Betty Miller.
Kansas, dacaDerek Schmidt of Kansas,
:{Missouri Attorney General Eric Schmitt:(style="margin:0px;padding:0px;border:0px;font-style:inherit;font-variant:inherit;font-weight:inherit;font-stretch:inherit;vertical-align:top;display:inline-block;max-width:100%;overflow:hidden;text-overflow:ellipsis;white-space:nowrap"):}:
Eric Schmitt was sworn in as the 43rd Attorney General for the State of Missouri on January 3, 2019. As Attorney General, Eric is focused on keeping Missouri families safe and upholding the rule of law. As the lawyer for all six million Missourians, Eric is fighting each and every day to protect opportunities for the next generation.
Nebraska,
:{AG Peterson | Nebraska Attorney General Doug Peterson:(style="margin:0px;padding:0px;border:0px;font-style:inherit;font-variant:inherit;font-weight:inherit;font-stretch:inherit;vertical-align:top;display:inline-block;max-width:100%;overflow:hidden;text-overflow:ellipsis;white-space:nowrap"):}:
Attorney General Doug Peterson - To serve the citizens of Nebraska and Nebraska's elected officials with fidelity to our U.S. Constitution, State Constitution, and Nebraska law.and
South Carolina
:{South Carolina Attorney General - Alan Wilson - AG:(style="margin:0px;padding:0px;border:0px;font-style:inherit;font-variant:inherit;font-weight:inherit;font-stretch:inherit;vertical-align:top;display:inline-block;max-width:100%;overflow:hidden;text-overflow:ellipsis;white-space:nowrap"):}:
South Carolina Attorney General - Alan Wilson. Youth suicide is the 2nd leading cause of death for our young people ages 10-24 in our nation and 3rd in South Carolina today. In South Carolina, the 2013 CDC's Youth Risk Behavioral Survey reported over ONE out of every EIGHT of our youth "seriously considered" suicide and that over ONE out ...
— are suing the administration of Democratic President Joe Biden over Biden’s plan to cancel up to $20,000 in student loan debt for individuals making less than $125,000 a year.
Six red states — Arkansas, Iowa, Kansas, Missouri, Nebraska, and South Carolina — are suing the administration of Democratic President Joe Biden over Biden’s plan to cancel up to $20,000 in student loan debt for individuals making less than $125,000 a year.
The Biden administration based its plan on a 2003 law. According to the Justice Department, the law, initially meant to help military members, says that Biden can reduce or erase student loan debts during times of national emergency.
The red states’ lawsuit, filed Thursday in Missouri, said that Biden’s plan was “not remotely tailored to address the effects of the pandemic on federal student loan borrowers.” The lawsuit adds that, since Biden recently declared the COVID-19 pandemic as over, he can’t use it as a justification for his wide-scale debt relief plan, ABC News reported.
“It’s patently unfair to saddle hard-working Americans with the loan debt of those who chose to go to college,” Arkansas Attorney General Leslie Rutledge said of her state’s lawsuit. “The Department of Education is required, under the law, to collect the balance due on loans. And President Biden does not have the authority to override that.”
The states argued that Biden’s plan inflicted a “number of ongoing financial harms” to student loan providers and also “will ultimately disrupt revenue to state coffers.” They also argued that Biden’s plan violates the Administrative Procedure Act, a law regulating how federal agencies ensure that presidential policies are well-reasoned and explained, the aforementioned publication reported.
Despite these claims, the White House has said it will continue with its plan, confident it can survive a court challenge.
“Republican officials from these six states are standing with special interests, and fighting to stop relief for borrowers buried under mountains of debt,” White House spokesman Abdullah Hasan said Thursday. “The president and his administration are lawfully giving working and middle class families breathing room as they recover from the pandemic and prepare to resume loan payments in January.”
an 'Keep borrowers in debt': Republicans plotting legal challenges to Biden’s student debt relief plan
Although some progressives believe that President Joe Biden’s plan to cancel some student loan debt doesn’t go far enough, a long list of Republicans — from U.S. senators to right-wing think tanks to state attorneys general — have accused the president of overreaching and are looking for ways to undermine Biden’s plan. The National Review’s Charles C.W. Cooke is even calling for Congress to “impeach and convict President Biden.”
Student loan debt has become a major problem in the United States, where it isn’t uncommon for students to graduate from college with six-figure debts that they will spend decades paying off with interest. This debt affects a variety of decisions that college graduates make as young adults, from deciding whether or not to have kids to being able to buy a house. Some older Baby Boomers, according to common complaints from Millennials and members of Generation Z, fail to comprehend the severity of the problem — as they graduated from college at a time when tuition was much more affordable than it is now.
Journalists Tony Romm, Jeff Stein and Danielle Douglas-Gabriel take a look at GOP reactions to Biden’s student loan debt plan in an article published by the Washington Post on September 1, stressing that some of those Republicans are considering lawsuits.
READ MORE:**Joe Biden could have gone much further on student loans**
“Republican state attorneys general and other leading conservatives are quietly exploring a slew of potential lawsuits targeting President Biden’s plan to cancel some student debt — challenges that could limit or invalidate the policy before it takes full effect,” the Post reporters explain. “In recent days, a number of GOP attorneys general from states including Arizona, Missouri and Texas have met privately to discuss a strategy that could see multiple cases filed in different courts around the country, according to a person familiar with their thinking who spoke on the condition of anonymity to describe the confidential talks.”
Romm, Stein and Douglas-Gabriel continue, “Other influential conservatives — including Sen. Ted Cruz (R-Tex.) and allies of the Heritage Foundation, a conservative think tank — are mulling their own options as they ratchet up criticism of Biden’s debt-relief plan, two additional people familiar with the matter said. And a conservative advocacy group founded by a major Trump donor said it would file a lawsuit against the policy.”
The Post interviewed John Malcolm, who serves as director of the Heritage Foundation’s Meese Center. The Heritage Foundation, founded in 1973, has been around 49 years — and its Meese Center was named after Edwin Meese, who served as U.S. attorney general during President Ronald Reagan’s second term and is now 90.
Malcolm told the Post, “The conservative public interest law firms in our network are exploring filing lawsuits against this. They are doing background legal research, trying to find out who might be the most suitable clients for them. They have to find a client with the standing and the gumption to take on a lawsuit. There are several groups in our network who are exploring that right now.”
READ MORE:**'For whom and why?' is the real question behind student loan forgiveness**
Biden’s plan would forgive up to $10,000 in federal student loan debt, or as much as $20,000 if the former student also received Pell Grants. Some liberals and progressives were hoping to see larger amounts of student loan debt forgiven, but the centrist Biden believes that $10,000 or $20,000 is a step in the right direction.
The Post interviewed some former college students who have a lot of student loan debt, and they were appalled that Republicans oppose even the modest amounts that Biden favors.
One of those interviewees was 31-year-old Ohio resident Michael Loomus, who dropped out of the University of Toledo and has been struggling to pay down the $11,400 that he owes. Loomus told the Post, “It just seems they are continuously trying to keep borrowers in debt. I don’t make a lot of money.… and before this, it just felt like I’d never pay off my loans.”
an 9 22 raga?
no lnx twt doc
'Just kidding': Biden Administration yanks student debt relief for millions as GOP states sue
Brett Wilkins and Common Dreams September 29, 2022
"The Biden administration told several million people they'd see their debt reduced by $10-20K, and a month later quietly wrote 'just kidding' on a website," said one affected borrower.
Progressives on Thursday decried the Biden administration's decision to exclude millions of people from its student loan relief plan, a move meant to thwart legal challenges like the lawsuit filed on the same day by six Republican-led states seeking to block President Joe Biden's proposal to cancel up to $20,000 of federal educational debt per borrower.
Politico reports worries over legal challenges from the student lending industry prompted the U.S. Department of Education to reverse course and no longer allow borrowers with Federal Family Education Loan Program (FFEL) and Perkins loans—which are guaranteed by the federal government but held by private lenders—to participate in the debt cancellation plan.
Biden announced last month that his administration will forgive $10,000 in federal student loan debt for borrowers who attended college without Pell Grants and who earn less than $125,000 individually, or $250,000 as a household. Borrowers who received Pell Grants will have $20,000 in federal debt erased.
The president's approval rating bounced by double-digits among young voters in the weeks after his announcement, which fulfilled a campaign promise and came just over two months ahead of the 2022 midterm elections.
However, student loan debtors expressed deep disappointment over Thursday's move, with one borrower and activist calling the administration's about-face a "gut punch."
Another, journalist Dell Cameron, tweeted: "The Biden administration told several million people they'd see their debt reduced by $10-20K, and a month later quietly wrote 'just kidding' on a website. Where's the legal threat over that?"
The administration's reversal came as six Republican-led states filed a lawsuit in a Missouri federal court Thursday arguing that the president's debt relief plan is "not remotely tailored to address the effects of the pandemic on federal student loan borrowers," a legal requirement under the administration's justification
According to The Washington Post:
The suit emphasizes that Missouri's student loan servicer, which is part of its state government, could see a drop in revenue because borrowers are likely to consolidate their loans under the Federal Family Education Loan program.
On Thursday, however, the administration said it would exclude FFEL from the loan forgiveness program... That change could help head off legal claims against the policy, although it will mean that roughly two million of the 44 million otherwise eligible borrowers will not qualify for relief.
Politico cites June federal data showing there were more than four million borrowers with $108.8 billion in privately held student loans.
"Republicans want to keep you in debt for the rest of your life and take away student debt cancellation," the Debt Collective, the nation's first debtors' union, tweeted in response to the suit. "It is an interesting strategy to adopt before the midterms."
an ah 9 22
Although some progressives believe that President Joe Biden’s plan to cancel some student loan debt doesn’t go far enough, a long list of Republicans — from U.S. senators to right-wing think tanks to state attorneys general — have accused the president of overreaching and are looking for ways to undermine Biden’s plan. The National Review’s Charles C.W. Cooke is even calling for Congress to “impeach and convict President Biden.”
Student loan debt has become a major problem in the United States, where it isn’t uncommon for students to graduate from college with six-figure debts that they will spend decades paying off with interest. This debt affects a variety of decisions that college graduates make as young adults, from deciding whether or not to have kids to being able to buy a house. Some older Baby Boomers, according to common complaints from Millennials and members of Generation Z, fail to comprehend the severity of the problem — as they graduated from college at a time when tuition was much more affordable than it is now.
Journalists Tony Romm, Jeff Stein and Danielle Douglas-Gabriel take a look at GOP reactions to Biden’s student loan debt plan in an article published by the Washington Post on September 1, stressing that some of those Republicans are considering lawsuits.
READ MORE: Joe Biden could have gone much further on student loans
“Republican state attorneys generaland other leading conservatives are quietly exploring a slew of potential lawsuits targeting President Biden’s plan to cancel some student debt — challenges that could limit or invalidate the policy before it takes full effect,” the Post reporters explain. “In recent days, a number of GOP attorneys general from states including Arizona, Missouri and Texas have met privately to discuss a strategy that could see multiple cases filed in different courts around the country, according to a person familiar with their thinking who spoke on the condition of anonymity to describe the confidential talks.”
Romm, Stein and Douglas-Gabriel continue, “Other influential conservatives — including Sen. Ted Cruz (R-Tex.) and allies of the Heritage Foundation, a conservative think tank — are mulling their own options as they ratchet up criticism of Biden’s debt-relief plan, two additional people familiar with the matter said. And a conservative advocacy group founded by a major Trump donor said it would file a lawsuit against the policy.”
The Post interviewed John Malcolm, who serves as director of theHeritage Foundation’s Meese Center.The Heritage Foundation, founded in 1973, has been around 49 years — and its Meese Center was named after Edwin Meese, who served as U.S. attorney general during President Ronald Reagan’s second term and is now 90.
Malcolm told the Post, “The conservative public interest law firms in our network are exploring filing lawsuits against this. They are doing background legal research, trying to find out who might be the most suitable clients for them. They have to find a client with the standing and the gumption to take on a lawsuit. There are several groups in our network who are exploring that right now.”
READ MORE: 'For whom and why?' is the real question behind student loan forgiveness
Biden’s plan would forgive up to $10,000 in federal student loan debt, or as much as $20,000 if the former student also received Pell Grants. Some liberals and progressives were hoping to see larger amounts of student loan debt forgiven, but the centrist Biden believes that $10,000 or $20,000 is a step in the right direction.
The Post interviewed some former college students who have a lot of student loan debt, and they were appalled that Republicans oppose even the modest amounts that Biden favors.
One of those interviewees was 31-year-old Ohio resident Michael Loomus, who dropped out of the University of Toledo and has been struggling to pay down the $11,400 that he owes. Loomus told the Post, “It just seems they are continuously trying to keep borrowers in debt. I don’t make a lot of money.… and before this, it just felt like I’d never pay off my loans.”
READ MORE: 'We should be proud': Education secretary explains why student loan forgiveness is an 'investment'
https://www.mediamatters.org/fox-news/tucker-carlson-calls-student-debt-relief-reparations-being-paid-drug-addicted-robots-no
quite a lot of RW BS on student loan forgive, bannon , tucker called reparations?; mebbe a string of dem wins/bills ~ 2022 red wave;
also try culture/class war BS rich college kids vs hard working real am, socialism
https://www.mediamatters.org/steve-bannon/steve-bannon-rails-against-student-debt-forgiveness-then-brags-about-his-ivy-league
biden not cancelled 10K as promised? 4 22 8 22 10-20K$
https://www.motherjones.com/politics/2022/06/education-department-student-debt-cancellation-corinthian/
cannot make 1st payment
https://www.alternet.org/2022/04/half-student-loan-borrowers-payment/
// social safety net ~ strict fr libtard?
an 3 22
With barely a whimper, free community college for all Americans bit the dust, at least for now.
Already stripped from the pared-down Build Back Better bill proposed by the Biden administration in October, free community college will not re-emerge as a free-standing bill in 2022.
An initiative that has been implemented successfully in 19 states as different as Arkansas and California, you might think that two years of free college might have been a model for elevating successful local initiatives as federal policy.
But apparently it was one thing for states to shoulder the burden of creating an educated workforce and another for the Biden administration to make that investment.
First Lady and community college professor Dr. Jill Biden was tasked with presenting the disappointing news to the 2022 Community College National Legislative Summit last week. She spoke of the human cost of this failure.
"These aren't just bills or budgets to me, to you, right?” Biden told colleagues who had hoped for a $45.5 billion infusion of federal money. “And it was a real lesson in human nature that some people just don't get that."
It’s no surprise that Senators Joe Manchin (D-WV), Kyrsten Sinema (D-AZ) and their Republican allies don’t “get that.”
They believe that a $45.5 billion investment in technicians, health care workers and other skilled laborers we desperately need is an unaffordable “handout” that weakens Americans’ moral fiber.
New Hampshire’s Republican Governor Chris Sununu also rejected the plan. Students who didn’t pay, he argued, would not commit seriously to education.
The bill had other enemies. One was inside the house all along.
Private colleges and universities, and at least one major, public four-year institution, saw the plan as a direct threat to their bottom lines.
As early as last October, the National Association of Independent Colleges and Universitieswithheld its support because the idea was “untested” and government could better help students by increasing Pell Grants.
But federally funded free community college is neither new nor untested: many were free for almost a century.
Part of an education reform plan, two-year colleges would, University of Chicago president William Rainey Harper argued in the 1890s, make Morrill Act public education funds available to more Americans.
These “junior colleges” would be situated in public high schools and would relieve four-year colleges and universities from teaching basic college-level skills and general education courses.
As an example of what this could look like, Harper divided his own tuition-driven university into a “junior college” and a “senior college” in 1892. But it was a high school principal, in Joliet, Illinois, who, in 1901, took up Harper’s challenge to first offer college-level courses for free and then establish an independent, public junior college.
The junior college movement expanded heterogeneously before World War II. Some, as in California, were public and free, and usually an extension of high school. Others, like the private, tuition-driven Harcum Junior College in Bryn Mawr, Pennsylvania, established in 1915 to educate middle-class women, were intended as a launching pad for a university education.
But by the mid-century 20th century, that status of community colleges declined in many states. As college enrollment expanded dramatically under the 1944 GI Bill, Harvard president James Bryant Conant argued that junior colleges — now known as “community colleges” because of their democratic to local education — were primarily for students with modest, vocational goals.
Similarly, all community colleges were never free, but they were free in places where the desire for economic growth and democratic social mobility merged.
Native Floridians paid no tuition until 1969. Similarly, post-secondary schools in California, the largest educational system in the country, offered post-secondary education to in-state students for free until 1978.
Its 73 community colleges also served as feeder schools to four-year institutions. By providing skilled labor, free community and four-year colleges fueled both states’ growth as national hubs for the aerospace and military industries.
Although the United States is currently faced with worker shortages across its skilled labor force, there is hard evidence that reviving tuition-free community college could be the remedy.
In 2008, Knoxville, Tennessee, made this move, a program that became statewide in 2014, funded by a combination of taxpayer dollars and private donations. Mentorship and apprenticeship programs that complement course work have boosted poor students into well-paying jobs.
So, what are the barriers to supporting two-year schools?
First, as their opposition to the Biden plan reveals, public and private four-year colleges and universities remain fatally dependent on tuition dollars that would be diminished if students who wanted a four-year degree could complete two of them for free.
Despite the economic vulnerability that became evident during the first months of the covid crisis, these institutions and the politicians that support them have no immediate plan to replace tuition with more sustainable income streams, like taxes.
As importantly, Joe Manchin’s anxiety that Americans will become moochers, and Chris Sununu’s belief that students will only be disciplined learners if they have skin in the game, reflect a national divide on whether public goods should be shared or earned, and whether the nation benefits from educated workers.
But voters, not surprisingly, break along ideological, class, age and racial lines.
A recent Pew study reveals that 85 percent of Democrats, and only 36 percent of Republicans, believe public colleges should be tuition-free.
But over half of non-college educated Republicans under 50 do support taxpayer-funded community colleges. So do Americans under 30 by an overwhelming 73 percent.
And while only 51 percent of white Americans are in favor of canceling tuition, Black (86 percent), Hispanic (82 percent) and Asian American (69 percent) citizens support democratic access to post-secondary education.
And best of all, tuition-free community college does have a track record. It creates satisfying and sustainable lives for American families, and a robust economy that can respond to the needs of tomorrow.
ref
new rep
The Soapbox Homepage
Politics
Health Care
Law
Media
Timothy Noah/October 26, 2021
How Four-Year Colleges Helped Kill Free Community College Tuition
One of the best ideas in Build Back Better is dead, and the higher-ed lobby deserves some blame.
Do you know anybody who doesn’t love community colleges? Me neither. They furnish job training that businesses no longer bother to provide. They provide skills that K-12 education is supposed to teach but often doesn’t, and they’re a bridge to a four-year college degree. Democrats love them. Republicans, though mostly hostile to higher education, make an exception for community colleges. “Community colleges,” says Peter Granville, senior policy associate at the Century Foundation, “are some of the most appreciated and widely approved institutions remaining in the United States.”
During the 2020 campaign, candidate Joe Biden promised two years’ free tuition and fees at community college or at a public four-year university. After the election, that was whittled down to funding tuition and fees only at community college, where you can get an associate degree in two years. Over 10 years, the federal government would pay 75 percent of the average national cost (currently that’s $3,700); states would pay the rest. Then that got whittled down to a five-year program in which the feds would pay 100 percent of the average national cost and then ratchet their contribution down gradually to 80 percent by 2028.
Last week, that got whittled down to nothing. The program is out of the Build Back Better reconciliation package. And one of the reasons, it turns out, is that four-year colleges lobbied against it.
That isn’t the only reason free community college tuition got bounced from the bill. It isn’t even the primary reason. But it’s the most shocking reason. Which may explain why I couldn’t get anybody to confirm precisely which four-year colleges lobbied on this. One source very reluctantly told me of hearing secondhand that it was a public university that resides in a state I won’t name. My telephone and email queries to relevant parties at this university went unanswered, which certainly raises suspicions. But that’s as far as this cloak-and-dagger caper took me.
The main reason the free community college tuition proposal got bounced from the bill, President Biden told a CNN town hall last week, was that West Virginia Senator Joe Manchin “and one other person [have] indicated that they will not support free community college.” Manchin was the main obstacle; the “other person” presumably was the reclusive Senator Kyrsten Sinema of Arizona, though at least some supporters of the bill thought Sinema was still gettable. Manchin, who last summer stated in a memo, “No additional handouts … or transfer payments” unrelated to families and health, and none of the latter unless they were means tested, hardened his opposition to the tuition proposal in the last few weeks. According to the Century Foundation’s Granville, the proposal Manchin was instrumental in killing would have furnished West Virginia with $40 million annually in tuition benefits extended to 22,000 students. (Sorry, kids!) Sinema’s opposition was perhaps less firm because Arizona would, according to Granville, get $400 million annually in tuition benefits extended to 237,000 students.
No Republican was ever going to vote for the reconciliation bill, with free community college tuition and fees or without it, because Republicans hate Democrats much more than they love community colleges. Some Republicans opposed the free tuition program on principle. New Hampshire’s GOP Governor Chris Sununu told The Wall Street Journal that if students didn’t pay part of their tuition, they wouldn’t hit the books. Never mind that if they didn’t get to go to community college, it’s a certainty they wouldn’t hit the books.
Or maybe Sununu’s opposition wasn’t principled at all. The proposal favored states where tuition charges for community college are lower than the national average. Those states would end up with a surplus that they could spend on four-year public colleges. In New Hampshire, by contrast, tuition charges are nearly twice the national average. Under the proposal, states where tuition charges are above the national median would get no surplus and would have to dedicate more state funds to making up the difference. (Sinema’s Arizona—again, per Granville’s calculations—would get $227 million in surplus funds; Manchin’s West Virginia, where community college tuition and fees are a whisker below the national average, would get a tiny surplus of about $1 million.)
The final community college proposal wasn’t exactly cheap, but neither was it intimidatingly high: $83 billion over five years. That’s less than one-quarter the cost of the provision in the reconciliation bill that provides free preschool, according to The New York Times.
But that’s not what’s eating me. What’s eating me is that private four-year colleges lobbied against the plan. Why on earth would they do that?
“They want paying customers,” explains Max Lubin, chief executive officer of RISE, a group that organizes student-led campaigns to reduce or eliminate the cost of attending college. If community college were free, some students would choose community college over a four-year college. The competition would be especially bothersome to for-profit colleges, which compete most directly for this population.
What about four-year colleges that effectively double as community colleges by offering associate degrees? “They would rather get Pell money,” Lubin said. “That’s free money. Then they can hike tuition anyway.” (Community colleges that participated in the free tuition program would be restricted in how much they could raise tuition.) “Pell money” is Pell grant money, which is given to lower-income students. Biden’s Build Back Better plan was supposed to increase the maximum Pell grant, currently $6,495, by $1,400, but that got whittled down to $500. Biden has hinted the final bill may bump that up a bit to make up partly for the loss of free community college.
The National Association of Independent Colleges and Universities didn’t lobby against free community college tuition, according to its president, Barbara K. Mistick. But it didn’t lobby for it, either. “Our efforts have been squarely focused on advocating for increasing the Pell Grant,” she told me by email. Mistick isn’t exactly enthusiastic about free community college. She told The Wall Street Journal last week that it was an untested program that would require building a new bureaucracy. “If you want to have the greatest impact, if you want to touch students in every single sector, the Pell program would do that,” she told the Journal. “You don’t want to do something that is going to take years.”
For four-year colleges, opposing free community college may be penny-wise and pound foolish. Several people pointed out to me that some of the students who acquire a free associate degree will transfer to four-year institutions; many in this group might never have attended college at all. Also, tuition and fees at four-year colleges are so much higher than at community colleges that unless a four-year college gives the student in question a free ride (thereby, in Sununu’s eyes, tempting said student to goof off), it’s a stretch to say it’s competing with community colleges at all. (Average tuition at a public four-year college is $10,560 for in-state students and $27,020 for out-of-state students, and at a private four-year college, it’s $37,650.) And don’t forget that states that don’t charge an arm and a leg for community college stood to receive surpluses that they could then have spent on their public colleges.
Yet four-year colleges and universities lobbied against free community college. It speaks volumes that the specific organizations that did so have gone into hiding. So does the silence we’re mostly hearing from four-year colleges on the demise of this very good idea. To me it sounds like a dowager’s murmur: “Not our class, dear.”
Timothy Noah @TimothyNoah1
Timothy Noah is a New Republic staff writer and author of The Great Divergence: America’s Growing Inequality Crisis and What We Can Do About It.
Sign up for TNR’s The Soapbox weekly newsletter.
Read More: Politics, The Soapbox, Education, Higher Education, Community College, Build Back Better, Reconciliation, Joe Biden, Joe Manchin, Lobbying
Editor’s Picks
Joe Manchin Is Bad for West Virginians
Jason Linkins
Why Are Democrats Fighting Over Free College?
Graham Vyse
where are gop rw 1st amend absolutists?
this is also LEGAL suppression:
i'm sure FIRE is on the case; accred by who?
an 1 22
Baker College, one of the largest private schools in Michigan, is threatening legal action against a former faculty member who spoke to ProPublica and the Detroit Free Press for an investigation published this month.
Jacqueline Tessmer, who taught digital media for 14 years at Baker’s campus in Auburn Hills, told the news organizations that students often came to the nonprofit college unprepared to succeed and exited without degrees or good jobs but with heavy debt from loans. “Baker College has ruined a lot of people’s lives,” she said in the story.
A Jan. 19 letter to Tessmer — sent by the law firm Plunkett Cooney on behalf of Baker — demanded she retract her statements, which it described as “false and defamatory.” It did not specify what, if anything, was false. Arguing that Tessmer was in violation of a nondisparagement clause in a settlement she reached with Baker in an employment dispute, attorney Courtney L. Nichols also demanded that she “agree voluntarily to remit payment to Baker College for the damages it has suffered as a result of your violation(s), including attorney fees.” The letter did not include a dollar amount.
Since publication, Baker has not contacted either news organization to contest the validity of her statements. Before publication, the Free Press and ProPublica informed Baker that Tessmer would be quoted and shared her comments. Baker did not specifically address those quotes or Tessmer’s time at the college.
Baker’s letter to her after publication gave her seven days to respond. Tessmer said in an interview this week she stands by her comments and will not meet the college’s demands.
She said she didn’t see how it would be possible to make a retraction even if she wanted to, given that she expressed her opinion “based on what I did in service to the college” and her comments were only “a couple of sentences in a giant article.”
“I could be quiet, but is it really going to matter at this point?” she added.
The story on Baker examined the college’s low graduation rates, its aggressive marketing and the oversight of a Board of Trustees that has included former presidents of the school.
In addition to the letter to Tessmer, Baker responded to the article by emailing students, writing a letter to the editor in the Free Press, and placing a statement on its website that disparaged the story and touted the school’s achievements. Officials have defended the 111-year-old college as an affordable open enrollment school whose practices are reviewed by regulators and accreditors.
Neither Baker nor its lawyer has responded to a request for comment on the legal threat.
Tessmer’s relationship with Baker ended in a lawsuit she filed for breach of contract and retaliation. The school disputed her claims in a countersuit, and the case ended in a settlement in 2014. The letter from Baker’s lawyer also suggested that if Tessmer had spoken about the settlement, she would be in violation of it.
“This is what they do,” said Tessmer, now self-employed. “They scare. They huff and they puff, and it works a lot of the time. I mean, it’s worked on me.”
The letter to Tessmer said that if she did not comply, “Baker College will consider its available recourse.”
As of Thursday evening, Tessmer had not heard again from the law firm.
no lnx twt
Pennsylvania resident and pizzeria owner Pauline Bauer, one of the many far-right Donald Trump supporters facing charges in connection with the January 6 insurrection, has been resorting to over-the-top antics ever since her arrest. And this week, journalist Scott MacFarlane reports in a Twitter thread, a judge became fed up with Bauer and "ordered U.S. Marshals" to take her "into custody."
Bauer, who was arrested by the FBI in rural Kane, Pennsylvania on May 19, is facing charges that include violent entry, disruptive conduct and obstruction of Congress. Prosecutors, journalist Kelly Weill reported in the Daily Beast on July 11, allege that when Bauer broke into the U.S. Capitol Building onJanuary 6, she threatened violence against House Speaker Nancy Pelosi and said, "Bring Nancy Pelosi out here now…. We want to hang that fucking bitch."
Nonetheless, Bauer has stayed out of jail — until now. This week, MacFarlane reports, Bauer was "screaming" when the frustrated judge ordered that she be taken into custody. The judge said, "The problem is she's not going to do what I direct her to do…. Ms. Bauer is now going to be incarcerated."
:{
}:
In the courtroom, MacFarlane notes, Bauer refused to surrender her U.S. passport while awaiting trial. The pizzeria owner told the judge, "I have (a) right to my self-determination" and insisted that she was not subject to the court's supervision.
According to MacFarlane, Bauer told the judge, "(The) FBI has been watching me ever since Day One.... They know where I'm at 24 hours a day.... I'm not a danger to society.... I am an asset to my community."
Bauer, MacFarlane explained, will be jailed in Washington, D.C. And because she will be behind bars, she will not be unable to attend the "Justice for January 6" demonstration that is scheduled to take place in D.C. this weekend. Organizers of the demonstration are claiming that the January 6 insurrectionists did nothing wrong when they stormed the U.S. Capitol Building in a failed attempt to prevent Congress from certifying now-President Joe Biden's victory over Trump in the 2020 election.
:{
}:
Bauer has insisted on representing herself in court and refused to work with an attorney. During a June 11 proceeding held online via Zoom, she told the court, "I do not stand under the law. Under Genesis 1, God gave man dominion over the law."
:{
}:
McFarlane said that Bauer had previously claimed to be a "sovereign citizen," part of an ideological movement of people who believe they are not subject to U.S. laws. But on Friday, he reported, she claimed to have never said she was a sovereign citizen.
==
big basis for occupy, esp student?
We moved quickly into starting to have general assemblies, having more and more people come out, trying to figure out what this looks like in the context of a midsize Southern town. Durham at the time had, you know, just over 200,000 people. But it was also beginning to go through some serious economic struggles, gentrification, housing displacement. There were a lot of people in Durham who were really struggling. And so, we really resonated with the message that was coming out of New York and with the same conversations that people were having about income inequality, about housing inequality.
I ran for office just four years after Occupy, in 2015. And I think at first it was kind of a leap of faith. I didn't really have a sense that I was going to be able to change things from an elected position. I was hoping that there was an opportunity there. And I think our movement was started to turn more and more toward the idea that electoral politics could provide some opportunities for us to make change and to leverage resources for the benefit of working-class and communities of color.
And I've been able to do that in ways that I didn't expect. I think the transition has been — it's been difficult in ways, but it's also been very empowering and exciting to be able to put my organizing skills and movement skills to work in a different context. And I think bringing more people into the electoral world, through some of the work I'm doing with a national organization called Local Progress and just folks in my community talking to other movement people, younger people who might be interested in moving into the electoral realm someday, I've felt like I've been able to gain skills and knowledge and then pass those skills and knowledge on to other people within the movement. So, it feels — it's felt really rewarding — difficult, of course, at times, but ultimately I feel like I've been able to do something good in this position, and I'm excited about passing the torch on to somebody else.
AMY GOODMAN: I want to go to a few months later, November 2011, during the Occupy protests, about a thousand students marching in New York City outside a meeting where CUNY trustees — that's City University of New York trustees — voted to authorize annual tuition increases. This is Julian Guerrero of Students United for a Free CUNY.
JULIAN GUERRERO: [echoed by the People's Mic] Me, myself, I'm in debt $70,000. I actually got a letter from Sallie Mae saying that if I don't start paying today $900 a month, they're going to have more aggressive attempts at collecting my debt. And so, I'm going to burn this right here and now.
AMY GOODMAN: So, that's Julian Guerrero of Students United for a Free CUNY, using the whole idea of the mic check and the open mic and the mic repeats that we've come to see that are so familiar. Astra Taylor, you are a key member of the Debt Collective. Talk about how that movement has evolved to today.
ASTRA TAYLOR: Now, the Debt Collective is an organization for debtors that fights for the cancellation of all kinds of debt and the provision of the services, the public goods we all need to survive and thrive. It has its roots directly at Occupy Wall Street.
So, just like Nelini felt that space to talk about her condition honestly, you know, for many of us who were in debt, Occupy was a similar space, where we could see that we were not alone — and that is actually the Debt Collective's slogan: "You are not a loan" — A space L-O-A-N, right? — a space where we could come together. And debt was actually part of the protests around the world at the time. Tuition hikes sparked protests in Latin America. And later, in Quebec, there was a wave of protests.
And so, you know, we followed the threads of debt, once the parks were cleared, because how we were thinking about it at the time was, you know, "Yes, we're occupying Wall Street, but Wall Street occupies our lives. And how does it do that? Often in the form of debt. We're forced to debt finance things that should be publicly provided." And it was at Occupy Wall Street that we had the collective epiphany. We started to recognize that our debts, which were so burdensome, could actually be a potential source of power, a source of leverage.
And by consistently organizing, we've moved the needle on that issue. I think, you know, we now are in a world where leading politicians talk about student debt cancellation. The Debt Collective has won billions of dollars of student loan cancellation for debtors. And that demand started at Occupy Wall Street. And the media was very skeptical. They mocked the demand. They said, "It's never going to happen. Isn't Occupy so naive?" Well, look where we are today. We've really moved the debate. And so, I think that's a really concrete, concrete result of this movement.
AMY GOODMAN: I want to go to the issue of police repression of Occupy protests across the country. On November 18th, 2011, campus police officers at the University of California, Davis pepper-sprayed peaceful student protesters. Video of the police attack went viral.
PROTESTERS: Don't shoot students! Don't shoot students!
The whole world is watching! The whole world is watching! The whole world is watching! The whole world is watching! The whole world is watching! The whole world is watching!
Shame on you! Shame on you! Shame on you! Shame on you! Shame on you! Shame on you!
ELLI PEARSON: I wasn't aware I was going to be pepper-sprayed until people told me to protect myself. And then I have friends who were pepper-sprayed who said they did not know that that was happening and that that was coming. And we were actually expected — we were expecting to be shot in the back with something, because they were behind us. And we really had no idea what was going to happen.
AMY GOODMAN: That's UC Davis student Elli Pearson speaking on Democracy Now! after she was pepper-sprayed. And you have the whole coordination. It later came out — I remember that piece in The Guardian by Naomi Wolf, "Revealed: how the FBI coordinated the crackdown on Occupy," the destruction of Occupy Wall Street and other places all over the country, well over a dozen cities. Nelini Stamp, if you can talk about what you understand took place, and how the police dealt with you?
NELINI STAMP: Yeah. I mean, you know, it was interesting, because the first — very early on, that first weekend, I remember going to an officer and saying, "Can my friend's car be there?" And they were like, "Yeah. Y'all will be gone by Monday."
And increasingly, as soon as we started — one of the first direct actions, regular direct actions, we did at Occupy Wall Street was the opening and closing bell. We would march for the opening bell and closing bell of the Stock Exchange and Wall Street. And that first Monday, we started getting shoved and pushed. And every single day that we were out there, things escalated to then a few arrests, to then a few more arrests. And I think things really changed on the Saturday.
There was a few things that I feel like people don't understand, what happened those first two weeks, also in the nation. Troy Davis was executed by the state of Georgia — a huge case of misjustice and racial reckoning again. There was a huge debate in the city of New York around stop-and-frisk. And so, all of these tensions were underlying. But there was also this idea and original, you know, sentiment to say that the cops are the 99%, too, because most of them were not making — if we were really a uniting movement. So, it was this really interesting juxtaposition that was happening those first two weeks.
And that Saturday — we did weekly actions on Saturday, and I don't remember if it was the 24th or the — I usually used to remember all of the dates in my mind. We took the streets. And it was civil disobedience like New York hasn't seen in a really long time. And I remember getting to Union Square, and all of a sudden they had this orange netting all around us, which I think is now illegal in the city of New York for cops to do. But they had orange netting, and pepper spray was just going everywhere.
And that was kind of the — I think that was a radicalizing moment for a lot of our white comrades at Occupy Wall Street, who never had to deal with the police as those of us who come from communities of color in New York had to, or those of us who have a history of — when I was younger, I remember seeing Amadou Diallo's murder on every single thing, and people marching on the Brooklyn Bridge. And so, for those who didn't have that background or that personal experience, they finally did have that. And that's when I think there was this awakening of a lot of young white folks or more affluent folks who didn't come from overpoliced communities actually saying and trying to hold the police accountable.
So, what you see is, right after Occupy Wall Street, you see Ramarley Graham gets killed in the city of New York, and then Trayvon Martin gets killed in Florida, and people start to act up, you know? I flew down to Florida, because they wanted somebody to train them in direct action, and helped co-found the Dream Defenders. We marched for miles to Sanford. And then you see a big march in June of 2012 with 50,000 people that said, "End stop-and-frisk." And I don't think that would have been — that would have had the new people involved as it did, if we didn't have so much, like, repression from the state. And I think part of it was to make people not come out, to make — people were really threatened by Occupy at that time. And I think that that's what ended up happening, and it was really beautiful to see people get involved and actually call out police brutality after that.
AMY GOODMAN: Nelini Stamp, I want to thank you for being with us. This has to end this discussion today. Nelini Stamp of Working Families Party in Philadelphia; Astra Taylor of the Debt Collective, speaking to us from Asheville; and Jillian Johnson, mayor pro tem of Durham, North Carolina — all three involved in the Occupy movement 10 years ago. And we continue to cover it when we look at the bills that are in Congress right now and so much more. I'm Amy Goodman. Thanks so much for joining us
==
Disturbingly Kafkaesque': Judge slams Betsy DeVos for denying 94% of student debt forgiveness claims
October 22, 2020
Arguing that Secretary of Education Betsy DeVos had undermined the agreement, a federal judge on Tuesday denied approval for a class action settlement over the Trump administration's handling of a student debt forgiveness program.
https://www.alternet.org/2020/09/house-republicans-paint-a-labor-vision-thats-straight-out-of-the-19th-century-robber-barons-era/
dcj dcr
Ten House Republicans who fashion themselves policy wonks are out with their diagnosis of what ails the American worker. Their proposed cure is a future that would be brutish, nasty and short.
The Hobbesian, dog-eat-dog policies the Republican Study Group proposes would enhance the power of those born to privilege, just so long as nothing knocks them off their comfortable perch.
The report proposes:
- No forgiveness of student loans even though our federal government authorized students to borrow huge sums to attend worthless commercial schools that went bankrupt, leaving them with no degree, just debt. The Republican plan lacks even the mercy provisions for debtors written into Hammurabi's Code almost 4,000 years ago, which wiped away debts when storms, war or corruption ruined a borrower's finances.
- A turn away from comprehensive higher education, especially liberal arts, to focus on technical skills and employability.Forget about developing the rigorous and thoughtful minds that enable young people to become informed citizens.
- Throughout, the report makes recommendations that would require a larger federal government workforce to police workers, students, poor people and immigrants.
- Empower workers by further weakening, if not eliminating, unions. TheRepublican Study Group report calls for workers to have more freedom to negotiate directly with their employers, a solution in search of a problem. "Our approach would unleash the full potential of the American people by refocusing labor policy to provide workers more control over their own future," [SEE CA PROP 22 BS ADS I HAVE TIME/FREEDONM TO TAKE CARE OF MY AA GPA]the report states. Given that individual workers are mostly commodities, that's the equivalent of urging that each grain of wheat in a silo be free to negotiate whether it goes into the grist mill first or last.
- Get tough on the poor and immigrants, who are portrayed as greedy thieves who shirk work, especially during the coronavirus pandemic. The poor and hungry get the blame for high levels of what the report artfully calls "improper payments" despite evidence that mostly these are screwups by federal agencies, not applicants. Not a word, by the way, is said about thieving defense contractors, farmers and other business operators even though a link in the report is full of examples where such businesses benefit from fraud, waste and abuse.
The 66-page report, Reclaiming the American Dream: Proposals to Empower the Workers of Today and Tomorrow, is amazingly slipshod. Frankly, the study group, lead byRep. Mike Johnson (R-La.) and its staff should be ashamed that they published such low-quality work.
Many hypertext links in the End Notes don't work, including the first. Others point to web pages that generate a "404" page missing response. While some End Notes refer to official data, many point to ideological marketing organizations like the Heritage Foundation and polemics based on *a priori*assumptions.
Anti-Unions Claim
Bizarrely, the report characterizes unions as holding down the compensation of members. That's absurd since the whole point of collective bargaining is to ensure that workers get fairly paid for their contribution to their employer's financial success.
Consider this lie on Page 32: "Under current law, union contracts set both a wage floor and a wage ceiling. As a result, individual workers cannot be given raises, including performance-based raises, by their employer."
No law is cited because none exists. And not one example of a contract that prohibits merit pay is cited in the report or in the right-wing newspaper article to which it links. I've negotiated a labor contract and I've read countless such collective bargaining agreements, none of which had prohibition of merit pay or bonuses. It's possible they exist, but the Study Group fails to show any evidence.
How revealing, though, that the Republican Study Group describes its imaginary prohibition on merit pay and bonuses as entirely a problem with unions rather than employers. The incentive to hold down pay lies with companies, not unions.
The report's attacks on labor unions as a detriment to members comes right out of the Donald Trump playbook in which making stuff up or distorting it without any respect for facts is the name of the game. Just make the claim and damn reality.
Contradictory Approach
Throughout, the report makes recommendations that would require a larger federal government workforce to police workers, students, poor people and immigrants. Many more auditors and investigators would be needed to investigate anyone who relies on what remains of America's tattered social safety net.
Implementing the proposed changes also would require massive investments in technology, primarily computers to both operate federal programs and to find people who abuse these benefits.
Neglecting to propose these expansions of investigative staff and computer systems makes the study group report empty rhetoric that reveals its members' mindset, favoring much more top-down power and punishment.
Attacking Working-Class Leisure
The report attacks not working, something a wealthy nation could reasonably aspire to achieve. "Among the civilian labor force, less than half of those who fail to complete high school are participating in the labor force," the report states, accurately.
Heaven forbid that people not work. This is on a theme with Trump, who throughout his 2016 campaign complained that too many Americans were not working.
Of course, there are many reasons people don't work, especially the "poorly educated" whom Trump often says he loves.
Those reasons include staying home to raise children, which Republicans used to hail as a virtue. Then there's caring for elderly parents or a disabled spouse or just enjoying leisure instead of chasing every last buck.
Unmentioned in the report are government policies that have driven down wages for the "poorly educated," an issue examined in my 2014 anthology DIVIDED: The Perils of Our Growing Inequality. For the many people whom nature or education made fit only for unskilled work, wages are now so low that it doesn't pay to get a job and can actually make you worse off.
We would have more people working if we moved to the shorter workweeks and mandatory paid vacations found in, say, Germany. That's anathema to the Study Group's perspective.
Tough Luck for Scammed Students
Another bizarre claim is that forgiving the debt of students swindled by corrupt fake colleges "would actually drive up the cost of college tuition and send the message that students who make irresponsible borrowing decisions will ultimately be bailed out by the federal government."
What of the responsibility of Congress, under both Democratic and Republican majorities, and presidents from both parties who enabled fake colleges and who put in place the harsh student loan rules that are also examined in my 2014 anthology DIVIDED. My 2008 bestseller Free Lunch tells of a student loan company that bought a Gulfstream jet to ferry members of Congress around gratis, the kind of institutional bribery that can distort the priorities of lawmakers.
Nowhere does the Republican Study Group propose the most obvious answer to America's higher education affordability issues. To prepare our young for the increasingly complex world of the future, we could simply restore the mid-20th century policies of making public higher education tuition-free or nearly so, an investment of tax dollars to build a prosperous and durable future.
Not everything in the report is without merit. The federal government operates, the study group says, 90 social welfare programs. Consolidating and simplifying those programs is a worthy goal. The report, though, is antagonistic to such programs, making any reader reasonably suspicious of changes the Study Group would seek.
This misunderstanding of the American students' and workers' needs should come as no surprise considering the signatories of this report. Nine are male. All ten are white.
https://www.alternet.org/2020/09/a-cruel-experiment-how-46-million-people-were-trapped-by-student-debt
The democratic principle of tuition-free education in our country pre-dates the founding of the United States. The first public primary education was offered in the Massachusetts Bay Colony in 1635, and its legislature created Harvard College the following year to make education available to all qualified students. Even before the Constitution was ratified, the Confederation Congress enacted the Land Ordinance of 1785, which required newly established townships in territories ceded by the British to devote a section of land for a public school. It also passed the Northwest Ordinances, which set out the guidelines for how the territories could become states. Among those guidelines was a requirement to establish public universities and a stipulation that “the means of education shall forever be encouraged.” After the nation declared independence, Thomas Jefferson argued for a formal education system funded through government taxation.
Jefferson’s vision took form over the course of more than a century, as state and local governments began creating primary schools and then high schools. The federal government became involved in higher education in the 19th century with the creation of land grant colleges and other institutions, used primarily to teach agriculture and education after the Civil War. These institutions created opportunities for people who had long been locked out of the learning process, including formerly enslaved African Americans and impoverished people of all races.
State universities and colleges rapidly expanded as well. By the middle of the 20th century, low-cost or tuition-free education was available in many American states. After the Second World War, the federal government once again turned to education to promote opportunities for its citizens and economic growth for all. The G.I. Bill paid educational expenses for 8 million people, without regard to individual wealth, which helped create a robust middle class and contributed to the vibrant growth economy of the 1950s and 1960s. While those opportunities were still denied to many people as the result of racism, efforts were underway to improve educational access for people of color.
The Reagan era ushered in a belief that government programs, including education, stood in the way of people’s dreams and should be severely cut back. Public goods came to be seen as investments, ones that were purely economic in nature. For these reasons, among others, a nation that had expanded publicly funded education for centuries decided to reverse course. Instead of funding higher education on the principle that it benefits us all, the country began shifting the cost to individual students. in the 1950s, as part of the National Defense Education Act, student loans were created as an experiment in social engineering. Concerned about competition with the Soviet Union, policymakers wanted to increase students’ capabilities in math and sciences. To do that, the country needed more teachers. So, lawmakers offered loans to college students, with the opportunity to have half the loan canceled after 10 years if they became teachers.
The experiment failed. Researchers have not been able to prove that the student loan program led more people to become teachers, despite multiple attempts to do so. The experiment was also cruel. Over the years, the student loan program was expanded, with the claim that a student’s personal investment in their education was an “investment” that would pay off in higher wages. Banks and other private lenders were brought into the process and given considerable incentives and subsidies to issue student loans, without considering the burden being imposed on the student. This financial opportunity was given to banking interests that were already wealthy, with little thought of the resulting damage to an economically sustainable future.
Proponents of financializing the cost of higher education argued that it was cheaper to lend money to students than it was for federal and state governments to provide grants for their education, even after paying subsidies to the private sector for their loans. An entire industry grew up around this process. State and nonprofit guaranty agencies were created to insure the loans. These agencies got paid, no matter what: when loans were issued, when loans became delinquent, when borrowers defaulted, and when they collected on defaulted loans.
In response, most states created guaranty agencies so they could make money from people who needed to borrow to pay for ever-increasing tuitions and fees.Now, states had an extra incentive to cut funding for public higher education. Not only would they save on expenditures, but they could increase the need for students to borrow, which increased their revenue. In many cases, these guaranty agencies don’t handle the loans themselves.They pass the work on to private debt collectors who take collection fees and are aggressive in their handling of cases.
The system took on a life of its own. By the mid-1990s, student loans had surpassed grants in funding students’ higher education. But a system built on debt financing only works if borrowers pay back their loans. That led Congress to make the system even crueler with the Bankruptcy Amendments and Federal Judgeship Act of 1984, which exempted student loans from bankruptcy proceedings and subjected borrowers to draconian collection tools. These tools included wage garnishment without a court order and the seizure of Social Security checks and tax refunds. The Clinton and Obama administrations attempted to lessen the burden slightly by allowing the federal government to lend directly to students while introducing income-based repayment options, but the system’s fundamental cruelty remains unchanged today.
It is time to recognize that the cruel experiment in financing higher education through student loans has failed. It has captured 46 million people and their families in a student loan trap, including people who received vocational training, and has weakened the financial strength of higher education. Inescapable debt is a major driver of social collapse. It has made the racial wealth gap worse and weakened the entire economy, as debt holders are prevented from buying homes or consumer goods, starting families, or opening new businesses. It’s time to restore funds for higher education and cancel student debt for the victims of this failed experiment.
Learn more at Freedom to Prosper.
Mary Green Swig is a senior fellow at the Advanced Leadership Initiative at Harvard University and co-founder of Freedom to Prosper.
Steven L. Swig is a senior fellow at the Advanced Leadership Initiative at Harvard University and co-founder of Freedom to Prosper.
David A. Bergeron is a senior fellow for postsecondary education at the Center for American Progress. Bergeron previously served as the acting assistant secretary for postsecondary education at the U.S. Department of Education.
Richard “RJ” Eskow is senior adviser for health and economic justice at Social Security Works. He is also the host of The Zero Hour, a syndicated progressive radio and television program.
This article was produced by :{Economy for All:(style="box-sizing:border-box;outline:none;margin:0px;padding:0px"):}:, a project of the Independent Media Institute.
https://www.alternet.org/2020/09/the-end-of-the-liberal-arts-dream/
curtis white salon
Most people know that student debt is a problem, and most people agree that “something should be done about it.” The consensus opinion appears to be that something should be done because it’s “not fair” to young people. According to a recent poll conducted by the Pew Charitable Trust, 80% of Americans believe that “the government should make it easier to repay student loans.”
Even so, there is very little understanding of why student debt has become so burdensome in recent decades. It’s as if we thought student debt were an unhappy fact of nature, like a weather front that has passed through leaving us with no option but to put on a warmer coat if we can find one, and if we can’t find one, it’s welcome to the Brave New World of Cold and Indifference.
And yet, it was not so long ago that things were very different. I was born in a working class suburb of San Francisco in 1951. At that time, public education was good, teachers still had some social prestige, universities were affordable (cheap actually), and few students graduated with debt. It was possible for me to sally forth without the threat of young adult bankruptcy.
In other words, at that time students were freer to choose what they wanted to study and freer to explore careers. As for me, I was free to be a student of literature and philosophy at the University of San Francisco. I learned to play the classical guitar up the hill at Lone Mountain College. I was also a longhair war resistor and draft counselor in the chaplain’s office. And I was mostly sure that I wouldn’t be punished for these decisions, or not punished any time soon.
unhappily, the university as I knew it no longer exists.Through the decades of Reaganomics and neo-liberal austerity, an elite determination was made that the state should no longer pay for public higher education; henceforth, universities would be funded through personal debt. Tuition to public colleges and universities became a bloated “user fee” for access to a government-affiliated service, like gaining access to a parking lot. Novel arguments gained force:students were just another type of consumer, and “student demand” should determine the content of the curriculum. What was lost in such market logic was the fact that programs in the arts and humanities—not just in universities but at all levels of education—had become the primary way in which we were allowed to think about who we are, where we are, how we got here, and what, if anything, we’d like to see changed. In the place of that worthy process, we were left with what David Harvey described succinctly: “The traditional university culture, with its odd sense of community, has been penetrated, disrupted, and reconfigured by raw money power.”
In both the public and private sectors, the corporate university has been slowly growing for many years, but it has now become more brazen in its destructive tendencies. For an example that is close to me personally, the Board of Trustees at Illinois Wesleyan University (IWU) in Bloomington, Illinois, announced in May of 2020 that it was considering the elimination of many long established programs all of which were in the liberal arts and social sciences. I say this is personal because my wife, Georganne Rundblad, taught sociology at Wesleyan for twenty-five years, and many of the faculty there were among our friends.
Without the consent of the faculty, the Board of Trustees sent pre-termination letters to twenty-five faculty members and instructional staff in philosophy, anthropology, music, foreign languages, sociology, art, and religion — in total, about a quarter of IWU’s faculty.A liberal arts university without philosophers is a contradiction in terms, but a Wesleyan university without a department of religion is an exercise in self-mockery. No doubt, IWU will continue to claim that its “primary focus” is in “opening students’ minds,” but the college of business will have to do most of the opening.
That, too, is already happening. Those departments that were not eliminated were said to be in need of “transformation.” Provost Mark Brodl told faculty member Scott Sheridan that “philosophy will support business and accounting, computer science and data science.” In another example of what Harold Bloom called the trahison des clerks, university president Georgia Nugent (a classicist by training) said that the department of art will “move more in the direction of art and design,” including graphic design and product design. In other words, before the arts can transform students, commerce will first transform the arts. Andy Warhol saw it coming: art is a can of soup.
Of course, there’s no reason to think that this is the end of these transformations, these latest shudders of what Bill Readings called “the university in ruins.” (Readings: “The contemporary University is busily transforming itself from an ideological arm of the state into a bureaucratically organized and relatively autonomous consumer-oriented corporation.”) Remaining faculty and programs can’t sleep comfortably, wondering who and what will be cut next, a year from now, five years or ten. University boards can wait — they’ve been waiting patiently for fifty years. For fifty years American universities have moved toward a sense of mission that a businessman can recognize, respect, and, most importantly, donate money to.
But from the perspective of the liberal arts itself, a liberal arts university that doesn’t recognize the value of the liberal arts shouldn’t transform anything. It should shut its doors, fold it all up. Better that than becoming what Illinois Wesleyan has become: a watery version of the Wharton School of Business.
Wesleyan trustees felt no need to provide a rationale for their actions beyond the crude idea that the affected programs were not cost efficient and that financial exigency threatened them in the near future, somehow — never mind the university’s $200 million endowment. They offered no educational reasons for the changes, and no argument for how the changes were consistent with the values of the institution. Like the bandits in John Huston’s “The Treasure of the Sierra Madre,” they said, “Reasons? We don’t need no stinking reasons.”
The feelings of faculty and alums are raw now because they feel, rightfully, betrayed. One member of the IWU Alumni for the Liberal Arts, Molly McLay, wrote to me:
I am infuriated by the lack of humanity and empathy in this process. Most of my professional work revolves around understanding, responding to, and preventing trauma. I truly think this experience at IWU has been a collective trauma.
Affirming McLay’s thought, Scott Sheridan, a professor of French and Italian at Wesleyan, commented to me:
I feel like I’m just caught in the middle of an administration that has lost its bearings, that is changing the rules on me late in my career. I’ve bought into the ivory tower model, I’ve done everything asked of me, and now when the economy has tanked, Covid is blazing, higher ed is collapsing, and the University has damaged my professional reputation, I find myself completely cast aside, looking at the necessity not only to retool my professional objectives but to rethink my life.
Professor Sheridan has lawyered up.
Finally, and elegiacally, Professor of English Michael Theune commented to the Chicago Tribune, “It is a bad day. The faculty’s control of the curriculum has been taken away.”
The motto over Wesleyan’s portal should no longer be “Scientia et Sapientia,” knowledge and wisdom. I propose that it should read like the legend over Dante’s Inferno: “No Admittance Except on Business.”
After the second world war, there was an enormous investment in public education. For the first time, the children of the working class had an opportunity to study subjects, like literature, that were formerly a privilege for the children of the affluent. We studied the humanities and the social sciences and in so doing found ways to critique and resist corporate culture and all of its murderous inequalities. In the 1960s, universities became best known for their “student protests.” The protests may now be in the streets and not on campus, but many of the protestors of the present—marching with Black Lives Matter, or against gender bigotry, or against the world as organized for the benefit of oil companies—got their intellectual chops in universities taking courses like Professor Rundblad’s “Sex and Gender in Society” or “Race and Ethnic Relations.”
But all this time our masters have been paying attention, and they have seen clearly and correctly: for many, many students, going to college was and remains a liberalizing experience (thus Biden’s enormous lead over Trump among college-educated voters). Our plutocrat masters concluded, “So this is what happens when you let the working class and minorities go to college. They study things of no value to us, and they learn to hate us.”
As a consequence, slowly, decade after decade, universities were starved and students were put in debt.Meanwhile, the wealthy came to the rescue and became university trustees. In these fallen days, the ideal trustee is someone who has money or knows people with money, ideally both. (The chair of Wesleyan’s Board of Trustees is Timothy Szerlong, former president of worldwide field operations at CNA Financial Corporation.)
The ultimate benefit of all this for our oligarchs, the 1%, is a new but very powerful form of social regimentation. Their message to students: “If you want a job, you will study what we want you to study, or else you will live in debt.” We could call this naked coercion, but for students it is their first adult taste of American Un-freedom.
In 1969, the year before I entered the University of San Francisco, I was working at a McDonalds in the East Bay. The franchise owner liked me and offered me a scholarship to McDonald’s Hamburger University. I laughed. I shouldn’t have.
Curtis White is a novelist and social critic. His most recent book is “Living in a World That Can’t Be Fixed,” published by Melville House.
==
==
parents who co-sign have to pay off, delay retirement?!
==
booktv 5/20
Michael Arceneaux, "I Don't Want to Die Poor"Essayist Michael Arceneaux detailed his economic struggles with student…
==
sotu
gov't school dog whistle to evang?
https://www.alternet.org/2020/02/betsy-devos-approval-rating-is-28-percent-as-voters-back-investigations-into-student-debt-scandal-poll/
==
https://www.alternet.org/2020/01/the-people-with-the-least-resources-are-now-shouldering-the-greatest-burden/
no lnx
‘The people with the least resources are now shouldering the greatest burden’
.
Written by Janine Jackson / FAIR January 24, 2020
Janine Jackson interviewed educator Kevin Kumashiro about student debt forgiveness for the June 28, 2019, episode of CounterSpin. This is a lightly edited transcript.
Janine Jackson: “Bernie Sanders’ Student Loan Debt Plan: Unworkable.” “Sanders Student Loan Debt Forgiveness Plan Makes Little Sense.” “Canceling Student Loan Debt Doesn’t Make Problems Disappear.”
Gee, corporate media, tell us how you really feel.
While Big Media’s coverage has lots of room for arguments against proposals from presidential candidates Elizabeth Warren and Bernie Sanders, and
Our next guest says if we’re thinking big, let’s think really big about the role of education—who gets it, and why—in US society. Kevin Kumashiro is former dean of the School of Education at the University of San Francisco, founder of Education Deans for Justice and Equity, and author of, most recently, Bad Teacher!: How Blaming Teachers Distorts the Bigger Picture. He joins us now from California. Welcome back to CounterSpin, Kevin Kumashiro.
Kevin Kumashiro: Janine, thanks so much for having me.
7 ways $1.6 trillion in student loan debt affects the U.S. economy
JJ: When you’re watching corporate media debate on an issue you care about, it’s hard to know whether to spend time combating the particular myths and misinformation in the conversation as it is, or to simply have a different conversation, with different premises and, frankly, participants.
If people are saying they oppose “government handouts,” for instance, you may feel a need to say, “Well, what about handouts to corporations?” But then you’re still stuck in this frame of seeing government as a separate force, apart from people, that’s giving things and taking them away, rather than a system that’s meant to be working to serve the common good.
Can we begin, though, with your overall take on the plans put forth by Sanders and Ilhan Omar, by Warren and Julián Castro, among others, as compared to the status quo?
And then what do you make of the arguments, those that we are hearing, against those plans?
KK: I think it’s really exciting that student debt relief is being elevated to the level that it is. It’s about time that we’re having this conversation. As you’ve mentioned, we know that there is over $1.6 trillion in student debt currently; that affects about 45 million people in this country. And this is a number, this is an amount, that has actually ballooned over the past couple of decades.
So one of the things that I think the proposals force us to think about is, what are our priorities right now, and how should that be reflected in our national budgets? Budgets reflect priorities, and if we were to fairly tax the rich and the corporations, and if we were to invest in education rather than in instruments of violence and repression, like prisons and war and so on, I think we would be able to create a budget that reflects that. This is absolutely affordable.
One of the things that I like to argue, however, is that as ambitious, as controversial, as some people think that these proposals are, I actually would say that they don’t quite go far enough, in the way that we’re talking about it still.
And what I mean by that is, right now, the debate seems to be, how do we make education more affordable?—as if education is a commodity, where those who have the wealth can afford to buy the best.
And what I would say is, “Yeah, we could engage in that debate, but maybe the bigger debate is, should education be seen and treated as a commodity in the first place?” Right?
Education, I think many of us would argue, is so fundamentally important, not only to individual wellness and livelihood and success, but also to the health and well-being of the community and the society, right? It strengthens democracy, it strengthens participation, social relations, global health. And so one of the things we should be thinking about is how education should be a fundamental human right for everyone. And what did it mean to invest in that? Where pre-K through college, you have the right to get the level of education that you need to be successful and happy in the world. And I think that’s where I would like to see the conversation going. And, hopefully, that’s a reframing that we are heading towards.
JJ: Well, I have seen sympathetic portrayals of people trapped in student loan debt. USA Today, on June 26, had an article evoking how people can get caught up, and how they are left open to predations from scam debt-consolidation companies, for instance. And then on another tack of the issue, the Washington Post had a data-driven piece about the negative impacts on the overall economy of student loan debt, which is something that I know that you’ve thought about, and that noted that the $1.6 trillion in debt that US families are carrying has doubled since the mid-2000s, which you also just said, and which a lot of newspaper articles leave out.
I would also say that media are doing a pretty good job of leaving most of the moralizing to the op-eds—you know, things like “I Worked as a Janitor to Keep My Student Loans Low. Wiping Debt Punishes Students Like Me,” which was in USA Today.
But what I’m not getting is what you’re talking about, which is the idea that, in reality, this is a bigger question about the role of education in society. I wonder how you see us moving the conversation from this specific conversation about Warren, about Sanders, and those plans; how do we push it to that bigger dialogue that you’re looking for?
KK: Yeah, it’s a great question, because overlapping with the ballooning of student debt over the last two decades is something that’s fueled that ballooning, which is the disinvestment by the public sector in public education.
So higher education is a great example, where it’s hard to call public universities public universities, because such a small percentage of their budget actually comes from the public sector. So what we’ve seen in the past 20 years is a massive decline, in some cases half, maybe even more than half, lost—in terms of what the states used to be contributing to, for example, state-run universities.
And where does that shortfall now get taken up? Well, some of it gets taken up in fundraising. And some of it gets taken up in corporate sponsorships. But the vast majority of budget shortfalls gets taken up by tuition increases. So there’s a direct connection between disinvesting in public institutions—in other words, making them less public—and seeing the students take on the burden.
And when we talk about the difference between public and private education, I think it’s also important to think about who do these universities serve. Right? Public universities serve a far more racially diverse population, they have more first-generation students, more working-class students, more immigrant students; they’re actually serving the students most in need.
And I think for many public universities, that was the vision, right, is that they would actually be the universities for the people; they were a counter to the elite private universities.
And so when we see public universities less able to serve their mission of reaching this much more diverse, underserved population, because we’re disinvesting in them, why are we not surprised, then, that the people with the least resources are now shouldering the greatest burden, in terms of trying to get education?
So, yeah, I think pushing the conversation, in terms of saying, “Well, what is the responsibility of society to educate its next generation? And how do we build up institutions where everyone can really benefit from that?”
And let me just say one more thing to even push the conversation a little further. One of the things that I like to argue is that we should not be debating, how do we give equal access to the institutions, to higher education, as it currently exists. That actually isn’t what we should be debating.
Because the reality is that higher education is not equitable right now. The current state of higher education is that it’s sort of like public schools—you have a handful of very elite institutions that serve the more elite population. And then you have a vast number of underfunded, under-resourced institutions that are serving the masses.
We don’t want to give equal access to that. What we actually want to do is level the playing field, by saying that the institutions themselves need to be more equitable.
So when I talk about reforming education, and thinking about the funding of education, I don’t argue that we simply need to equalize how individuals finance their education. I actually argue that we need to be thinking more equitably about the funding of the system, and how that then changes the hierarchy that currently exists between educational institutions. We need to be changing the system of education, not simply individual access.
JJ: And some of the opponents on this particular issue of debt forgiveness, they, I think, have a more comprehensive vision, because some of them are the same people who are also fighting affirmative action—in higher education, in particular; some of them are the same who are against the very idea of public education that you’re talking about.
And I feel like latent in a lot of debate is the idea that education is supposed to be unobtainable for many, because otherwise, it’s not as valuable as a stratifier, as a screen. And among other things, to pick up on that you just said, that’s not the historical vision of education in this country, is it? I mean, if you look back at the history, education had a democratizing impulse behind it.
KK: So that’s such a great reminder, is that the history of education in this country is a very complicated and contested one. And when we look throughout the last century and a half, for example, what we can see is that different groups have argued for competing purposes of education.They’ve put forth different arguments of what education should be about.
So what I like to argue is that, let’s start with kind of public schools, K–12, elementary, secondary schools. When we first created public schools in this country, we didn’t create them for everyone; we created them for only the most elite. And as we were forced to integrate more and more, we just came up with more and more ways to divide and sort them, such as through segregated schools, or tracked classrooms or labeling, discipline and disenfranchisement.
And so, when we think about the achievement gap, or this gap in performance among students, many people say that that’s a sign that schools are failing. I like those who make a slightly more provocative argument, that actually the achievement gap is a sign, in some ways, that schools are succeeding, that they were doing exactly what they were set up to do.
So one of the things that we need to be arguing is not that we simply need to tinker with the system because it’s not really working well. What we actually need to recognize is that the system was built on really problematic assumptions, ideologies and exclusions from its very beginning. And our job is not to wish them away; our job is actually to dive into that contradiction and that messiness, and to say, “Well, how do we work in institutions that maybe were never intended for us, but still make them into the liberatory, revolutionary, democratizing institutions that they have the potential for?” Right?
Alongside the history of sorting and stratifying, you have a equally long history of people arguing that schools can be a democratizing force, and have been very forceful and persuasive at changing policies and institutions to move us in that direction. Schools have always been the site of struggle.
And this is another moment when we need to dive in and say, “Yes, we need to struggle, and we need to put forward a much bolder vision than we’re currently pursuing.”
JJ: Just finally, to return to media: I think part of what resists the bigger and more comprehensive thinking that you are encouraging—I mean, obviously, if you’re thinking about access to education, a natural question is, “Well, what jobs are there for people?” You know, assuming they we had access to education, it has to be a part of a bigger picture.
And part of how media resist that conversation is the way they atomize topics of coverage. So you’ll find this story over here about student debt forgiveness, but it won’t even talk about how people plan to fund that; it’s sort of separated, and so it becomes this idea in isolation.
And that, I think, inhibits not just public understanding of any given issue, but also our imagination, and our ability to believe in the possibilities of change.
KK: Yeah, I love that way of putting it, because it reminds me that education, so often, is talked about with really narrow boundaries, the way we think about what education should be all about. Many people are fixated on the idea that it’s about job preparedness.
And, yeah, of course education is in some ways about preparing us for our future role in the economy. But I like to say that education is also about teaching us to think, and teaching us to question, and teaching us to build a better tomorrow and a better society.
In other words, education isn’t simply to help us succeed in the world as it is. Education is actually about helping us to imagine and create the world that doesn’t yet exist. And that can be most scary to precisely the people that you’re talking about, the corporate elite, the most powerful, the most dominant.
Why? Because they benefit the most from the system as it is, right? And so it’s not surprising that they’re going to be the most vocal and the most forceful and violent in attacking the proposals that can fundamentally transform schools.
But that’s exactly what we need to be doing. That’s exactly what we should be expecting. And I think, in many ways, that’s exactly what we’re seeing. So all the more reason we need to dive in with much more confidence, but also with much more complexity, as we push the envelope.
JJ: We’ve been speaking with Kevin Kumashiro. His most recent book is Bad Teacher!: How Blaming Teachers Distorts the Bigger Picture. You can follow his work at KevinKumashiro.com. Kevin Kumashiro, thank you so much for joining us this week on CounterSpin.
https://www.alternet.org/2020/01/here-are-4-reasons-why-millennials-dont-have-any-money-robert-reich/
no lnx vid
Here are 4 reasons why millennials don’t have any money: Robert Reich
Written by Robert Reich / Robert Reich's Blog January 12, 2020
The same forces that are driving massive inequality between the top 1 percent and the rest of us are creating a vast generational wealth gap between baby boomers — my generation — and millennials.
Millennials aren’t teenagers anymore. They’re working hard, starting families and trying to build wealth. But as a generation, they’re way behind.
They’re deeper in debt, only half as likely to own a home, and more likely to live in poverty than their parents.
If we want to address their problems, we need to understand those problems.
Number one: Stagnant wages. Median wages grew by an average of 0.3% per year between 2007 and 2017, including the Great Recession – just as millennials were beginning their careers. Before that, between the mid-1980s and mid-1990s, wages grew at three times that rate.
Second: As wages have stagnated, the costs of essentials like housing and education have been going through the roof. Millennials own fewer homes, the most common way Americans have built wealth in the past. Education costs have soared. Adjusted for inflation, the average college education in 2018 cost nearly three times what it did in 1978.
Third: As a result of all of this, Debt.That expensive college education means that the average graduate carries a whopping $28,000 in student loan debt. As a generation, millennials are more than one trillion dollars in the red. In addition, the average young adult carries nearly $5,000 in credit card debt, and this number is growing.
Fourth: Millennials are finding it harder than previous generations to save for the future.Among Fortune 500 companies, only 81 sponsored a pension plan in 2017, that’s down from 288 twenty years ago. Employers are replacing pensions with essentially “do-it-yourself” savings plans.
All of this means that fewer millennials are entering the middle class than previous generations.Most have less than $1,000 in savings. Many young people today won’t be able to retire until 75, if at all.
If we don’t start trying to reduce this generational wealth gap — through policies like debt relief, accessible health insurance, paid family leave, affordable housing, and a more equitable tax code for renters — millions of young Americans will struggle to find financial security for the rest of their lives.
==
==
https://www.alternet.org/2019/10/betsy-devos-held-in-contempt-and-gets-100000-fine-for-gauging-defrauded-students/
no lnx
Betsy DeVos held in contempt and gets $100,000 fine for gauging defrauded students
Written by Laura Clawson / Daily Kos October 25, 2019
Education Secretary Betsy DeVos was held in contempt of court and slapped with a $100,000 fine (which the government will pay) for continuing to collect loan payments from students who were defrauded by the now-closed for-profit Corinthian Colleges. U.S. Magistrate Judge Sallie Kim had ordered the Education Department to stop collecting on loans owed by around 16,000 former Corinthian students, an order the Education Department mostly ignored.
In issuing the rebuke, Kim said that “the evidence shows only minimal efforts to comply with the preliminary injunction.” In some cases, the government even seized tax refunds or wages to collect the money that the former students were not supposed to have to pay.
When Sen. Elizabeth Warren confronted DeVos over this issue at a Senate hearing earlier this month, DeVos tweeted, “Loan servicers made an error on a small # of loans.”
Again, 16,000 borrowers are involved. Blaming loan servicers is the Education Department’s strategy for responding to the contempt citation, because, as usual, when rich people like Betsy DeVos get called out on their abuses, they scream that it’s unfair and demand to evade accountability, even as they insist that students who were literally defrauded by a for-profit college should get no relief.
The Education Department is refunding “at least 3,200” of the borrowers, but 3,200 is a long way from 16,000. The $100,000 fine will go to help some of the students. The judge is also requiring the Education Department to provide monthly updates on what it’s doing to make things right, and if the agency continues dragging its feet, she might “impose additional sanctions, including the appointment of a Special Master to ensure compliance with the preliminary injunction.”
==
AN 619
Sanders plan would wipe out all $1.6 trillion in US student loan debt by taxing Wall Street speculators
==
==
// UC slush fund?
Cal State University blasted for $1.5 billion bankroll while hiking tuition
==
https://www.alternet.org/2019/05/bribing-shady-faculty-isnt-the-only-way-parents-get-busted-trying-to-get-their-kids-into-college/
Excerpted with permission from “The New Debtors’ Prison: Why All Americans Are in Danger of Losing Their Freedom” by Christopher B. Maselli. Copyright 2019 by Skyhorse Publishing, Inc.
Wanting your children to succeed in life is a goal that all parents share, and one road to a prosperous future has always been through higher education. However, for the average middle-class family, this can be a real financial challenge even when both parents are working, sometimes more than one job, to make ends meet. If college seems to be getting more and more expensive, that’s because it is.
As an example, take a look at these shocking facts. In 1974, the median American family earned just under $13,000 a year. A new home could be had for $36,000, an average new car for $4,400. Attending a four-year private college cost around $2,000 a year, while a public university averaged $510 a year. To put these figures in current dollars, we’re talking about a median family income of $62,000, a house for $174,000 and a sticker price of $21,300 for the car, $10,300 for the private college and $2,500 for the public one.
How these costs relate today is telling when you realize that median family income has risen slightly to about $64,000, while median home prices have increased by about two-thirds, car prices have remained steady, but the real outlier is higher education. Tuition at a private college is now roughly three times as expensive as it was in 1974, costing an average of $31,000 a year; public tuition, at $9,000, has risen by nearly four times. This is a painful bill for all but the very richest. For the average American household that doesn’t receive a lot of financial aid, higher education is simply out of reach.
Student loan debt is increasing because government grants and support for postsecondary education have failed to keep pace with increases in college costs. Subsequently, much of the burden of paying for college has shifted from the federal and state governments to families. The government no longer carries its fair share of college costs, even though it gets a big increase in income tax revenue from college graduates.
Ever-increasing tuition costs at state and private colleges and universities, coupled with the lack of adequate wage increases, make it a real struggle for many families to provide a college education for their children. With this struggle comes risk, and debt is often a consequence, the penalties for which can be more severe than just debt collection calls and a bad credit score. Young college graduates these days who receive incredibly expensive degrees also leave with an average of $35,000 in student debt, and the parents are the ones who are increasingly being held responsible, putting their very freedom on the line in the process.
With college being so expensive, it might come as a shock to some parents and students when they start the financing process to learn that one form—the Free Application for Federal Student Aid (FAFSA)—may largely determine their financial fate when it comes to federal student aid. FAFSA forms are prepared annually by all current and prospective college students in the United States to determine their eligibility for student financial aid. During the process, there might be an overwhelming temptation to “fudge” the numbers on the FAFSA to get more money to help pay for your child’s education. However, getting caught could spell big trouble.
Filing a fraudulent claim for student financial aid is a direct violation of federal law, specifically 20 U.S.C. section 1097, which makes it a federal offense to knowingly and willfully obtain student aid funds by means of making false statements to the government. Unfortunately, federal student loan fraud is a growing trend, with more and more parents of college students being prosecuted for giving misinformation on the FAFSA. If you are convicted of this federal offense, you may have to pay a substantial fine, serve time in prison, or both. A recent decision by the United States Court of Appeals for the Ninth Circuit, US v. Carlos Javier Ezeta(Case No. 12-10304, May 23, 2014), illustrates how you can be charged with committing financial aid fraud.
Between 2008 and 2011, Carlos Javier Ezeta worked as a counselor and professor at the College of Southern Nevada. Motivated by his interest in helping the Hispanic community, Ezeta often assisted Spanish-speaking students in their college applications and course selections. He also helped the students obtain federal financial aid by falsifying several FAFSA applications. Based on false representations made on the forms, student aid money was dispersed to several students, including some who had not completed high school, received a GED, or passed an “ability-to-benefit” test.
The U.S. Department of Education requires that at least one of these conditions be satisfied in order for an applicant for federal student aid to be eligible. On the forms, Ezeta falsely reported that the students satisfied the education requirements and submitted the forms without the students’ knowledge that they contained false information. Eight applications were generated, and six students obtained funding in the amount of $8,709. One application was intercepted before money could be dispersed, and another was never sent because the student had yet to obtain a phony certificate of high school completion. In all, the falsified documents sought financial aid amounting to over $37,000. An undercover sting operation was launched, and Ezeta eventually admitted to falsifying the applications. Although he did not personally obtain any funding, Ezeta was arrested and charged with four felony counts of financial aid fraud in violation of 20 U.S.C. section 1097(a). The Ninth Circuit Court concluded that although Ezeta did not receive any money himself, criminal liability under federal law extends to knowingly and willfully causing the funds to be disbursed to a third party by fraud, false statement, or forgery.
The law is clear and the consequences severe on this statute, which prohibits anyone from knowingly and willfully embezzling, stealing, or obtaining by fraud, false statement, or forgery any funds provided for higher education purposes. If the amount of the funds provided is $200 or more, you could be charged with a felony. If you are convicted of a felony violation of financial aid fraud under federal law, you could be imprisoned for up to five years, fined a maximum of $20,000, or both. Plus, you’d have to return any aid you had received. If the funds are less than $200, you face a misdemeanor charge. A misdemeanor violation under 20 U.S.C. 1097(a) carries a sentence of not more than one year in prison, up to a $5,000 fine, or both. While this law has been in existence for decades, the prosecution for federal student loan aid is growing steadily.
Federal law also prohibits the acceptance of a loan made under false pretenses. If you are convicted of intentionally providing false information in order to obtain a federal student aid loan, you face a misdemeanor, punishable by up to one year in prison, a maximum fine of $10,000, or both. Because fraud is considered a crime of moral turpitude, a phrase used in criminal law to describe conduct that is considered contrary to community standards of justice, honesty, or good morals, a federal fraud conviction can also result in disciplinary proceedings—such as loss of a professional license (including a teaching license)—and may also lead to your deportation if you are not a US citizen.
Falsifying an Application for Financial Aid is risky and foolish. In the example above, the defendant seemed to have good intentions. After all, he simply wanted to help students from the Hispanic community to pay for their college education. However, as the court pointed out, a crime committed with a “good heart” is still a crime. Additionally, the court noted the professor stood to benefit indirectly from his wrongdoing since the unlawfully obtained funding provided to his students would go to the college where he was employed.
According to Fox Business (July 2015), one commenter in the College Confidential forums said her parents were planning to claim they were separated in an attempt to maximize their chances of financial aid. “I was definitely NOT on board with this but they refuse to listen to anything I’m saying,” the student wrote.
In 2014, the Boston Globe reported that a father of a former Harvard student pleaded guilty to charges of falsifying income information to get more than $160,000 in financial aid. He apparently filed false tax returns, which likely carries additional penalties. In another example, a college professor and counselor was charged with fraud after he allegedly falsified applications for students he said he was just trying to help. And there is the case of a mother and daughter who pleaded guilty in 2014 for making false statements to federal agents in connection with an investigation of student aid fraud. The mother reported no income for a period during which she reportedly received over $521,000 in income.
So, if you’re thinking of falsifying your FAFSA, just don’t. And if you think you can’t get caught, think again. College financial aid administrators are more skilled and experienced at detecting lies than families are at perpetrating them. In fact, about one-third of all FAFSA applications are selected for verification by the Department of Education. If yours is chosen, additional documentation will be required. An example of a red flag: the tax return shows dividends and interest on investments, but little or no assets are reported on the application.
Then there are other examples such as parents who pretend they are separated. Separation is prevalent enough in society today, but in the instances where there is an informal separation, the parents must be living apart for this to be a legitimate claim, and you have to be ready to show divergent utility bills or some other form of proof that the parents are occupying two separate households. That’s just one of the ways in which a lie like this can be discouraged, or uncovered.
Not telling the truth about which parent a child is living with in order to get more financial aid is another common occurrence. You can get caught easily in this lie, as well. It can slip out accidentally if a student reveals contradictory information about his or her living arrangements to a teacher or authority figure. And this is fraud. Schools are aware of this and have a compulsory responsibility to look into any instances where they suspect fraud.
A college education is expensive, and parents and students who want to avoid student loan debt may be tempted to fudge facts. But it’s not worth it. If federal student loans aren’t enough to cover your total student loan bill, you have other options. Private student loans are available for students and parents, but private loans (unlike federal student loans) will most likely require a credit check to determine your interest rate, and a cosigner if the borrower has a limited or nonexistent credit history. You can get a free credit report summary every month on Credit.com to see where you stand. If you have great credit, private student loans may even get you a better interest rate than Parent PLUS loans, so doing your research, improving your credit, and monitoring your progress are key.
From Bernie Sanders to Elizabeth Warren to Kirsten Gillibrand to … lots of others, Democratic candidates in 2020 seem to have plans to lower the cost of education and make it possible for more Americans to attend college without drowning under a mountain of debt. Democrats recognize that education is critical to obtaining a good job, and that the cost of education in 2019 means that students are often saddled with loans that can not only erase the benefits of that education for years, but take those new college graduates out of the market for homes, or restrict their ability to move. In short, high costs for college not only means misery for graduates, it harms American companies at every level by depriving them both of workers and consumers.
So, naturally, Donald Trump is making it worse.
While Trump’s tax break for billionaires is just that—a plan that awards Trump himself tens of millions in tax breaks and means that some of the largest, most profitable companies in the country pay no tax at all—it punishes working class and middle class students. As *The New York Times* reports, students attending college on scholarships or financial aid packages are being taxed at a rate higher than Trump pays on his eight-figure income, with rates going up to 37%. That means that some of the students who most needed the money the most, but who made it into college on academic or athletic scholarships, or those who assembled an aid package that let them barely climb over the cost hurdle … are finding their mailboxes full with bills from the IRS. And, unlike Trump, they can’t get away with ignoring tax law.
Somehow, when they were crowing about this tax plan, Republicans failed to brag about how it was going to sock low income and middle class students for tens of thousands so that billionaires and corporate CEO’s could take home maximum benefits. It it seems like skimming from students wouldn’t make much of a difference, this isn’t just a slap on a few. This Trump tax hits about 1.3 million undergraduates and 15,000 grad students. And that’s not all. This “mistake” by Trump and the Republicans in designing their tax plan, is also taxing tribal funds paid to Native Americankids to help them get an education … or simply to live. That’s quite a mistake.
But was it a mistake? The reason all these students are being hit is because the Republican law didn’t just include the special “kiddie tax” rate that was originally established to punish wealthy parents who tried to avoid taxes by hiding money under the names of small children, it expandedthat tax. The new law increased the age limit from 14 to 23 and removed language that limited the application of the tax. That makes punishing low income and middle class students seem a lot less like an accident, and more like a plan.
Democratic Representative Elaine Luria is leading an effort to roll back the expanded “kiddie tax.” Republicans may claim that the fact that low income students are finding financial aid packages taxed at the same rate as the maximum paid by wealthy toddlers whose parents try to hide a few million under their blankets is a mistake—just something they overlooked in their headlong rush to express mail trillions to the wealthiest people in the world—but somehow getting them to agree to fix this mistake is “not far along.”
https://www.alternet.org/2019/05/mistake-in-republican-tax-plan-taxes-1-3-million-scholarship-students-more-than-millionaires/
==
https://www.alternet.org/2019/05/public-service-loan-forgiveness-is-in-trouble/
https://www.c-span.org/video/?458861-1/land-fee
quite good
MARCH 18, 2019
Land of the Fee
Devin Fergustalked about his book, Land of the Fee: Hidden Costs and the Decline of the American Middle Class, on the hidden transaction fees that Americans regularly pay and the impact these costs have on the middle class.
==
==
richard wolff 519 share-cropper student loan tuition
- Right-wing outlets like The Wall Street Journal editorial page are touting a deeply flawed new study attacking electric vehicles.
- Trump Fed pick Stephen Moore repeatedly said that he liked working at Fox News because he met "a lot of beautiful women" there. Moore has also praised slave-owning Confederate general Robert E. Lee and hates climate science so much that he even attacked Ivanka Trump.
- Tucker Carlson's wild new talking point is that abortion is somehow a tool of "corporate" oppression.
- A Fox host blamed bank regulation for high tuition and the student loan crisis.
==
https://www.alternet.org/2019/04/elizabeth-warren-announces-plan-to-end-student-debt-and-provide-free-public-higher-education/
==
https://www.alternet.org/news-amp-politics/heres-how-trump-devos-and-mulvaney-helped-banks-and-colleges-steal-students
Trump Administration hid a study documenting financial abuse of students by some banks working hands-in-glove with colleges, the latest example of how instead of “draining the swamp” Donald Trump is turning official Washington into a paradise for swamp monsters.
The suppressed fee gouging report was made by the Consumer Financial Protection Bureau or CFPB.
Students attending colleges which have marketing agreements with banks and other financial institutions paid much higher overdraft and account fees than students at schools with no such deals, the study found.
“Wells Fargo charged students the most of all those with college campus marketing agreements—an average of $46.99 per account per year, while banks without such deals charged students an average of $11.93 in fees,” Kate Berry of American Banker reported.
Some nonprofit credit unions also engaged in fee gouging. The University of Kentucky Federal Credit Union, for example, charged $37 per account annually, the study found.
One lender has charged $600 just to issue loan checks.
The Trump administration wants to kill the CFPB, as we have documented in nine previous DCReport articles. Lacking authority to do that, Team Trump has turned the bureau into a protection agency for the worst banking practices, damaging millions of consumers. Hiding findings of abusive practices and disloyalty to customers are key parts of this Trumpian strategy.
We know of the study only because it was mentioned last August in a scathing resignation letter by Seth Frotman, a CFPB assistant director and student loan ombudsman. Frotman accused Mick Mulvaney, who is Trump’s director of the Office of Management and Budget as well as acting director of the CFPB, of suppressing the report because it showed large banks knowingly ripped off students by charging high or inappropriate fees.
Frotman’s resignation letter charged that under Mulvaney the bureau was “shielding bad actors from scrutiny” while both undercutting enforcement of laws to protect consumers and undermining the bureau’s independence.
Referring to his extensive travels and especially his talks with military families who were conned by financial product sales agents,Frotman wrote that “American families need an independent consumer bureau to look out for them when lenders push products they know cannot be repaid, when banks and debt collectors conspire to abuse the courts and force families out of their homes and when students loan companies are allowed to drive millions of Americans to financial ruin with impunity.”
Mulvaney offered a cavalier response in a CNBC interview. Mulvaney said that he had never even heard of Frotman and had been told that while ombudsman Frotman never complained about the issues raised in his resignation letter. He avoided dealing with the substance of the issue—lender disloyalty to customers.
The study was pried loose by Allied Progress through the Freedom of Information Act, a nonprofit consumer watchdog created in 2015, during the Obama Administration, by Karl Frisch, a lifelong communications adviser for Democratic candidates and progressive organizations.
The fees in the study Mulvaney suppressed are modest compared to a test of student loan fees I made in 2008. The cost to a bank of sending a payment electronically is so minute that many banks charge nothing for the service.
After failing to get NelNet, a student loan servicer, to discuss its fees, I took out a Sallie Mae student loan for one of my children, an action I described in my 2012 book The Fine Print. NelNet divided the loan into two payments, one for each semester. It levied a $300 fee for the cost of issuing the first check. I repaid the loan immediately to avoid a second $300 charge.
Responsibility for protecting students from lenders falls to the CFPB under the law creating it. That law was sponsored by Senator Elizabeth Warren, a Massachusetts Democrat whom Trump loathes. The duty to police colleges so they do not help banks abuse students falls to the federal Department of Education, where Betsy DeVos, the education secretary, has repeatedly taken the side of bankers against the interests of students, as well as parents and grandparents who co-sign student loans. Some of her anti-student actions are detailed in It’s Even Worse Than You Think, my book about the Trump administration.
Hiding the study until it was flushed out using the 1966 Freedom of Information Act is just the latest example of how Trump has aggressively worked to do the opposite of what he promised in his inauguration speech:
“What truly matters is not which party controls our government, but whether our government is controlled by the people… January 20th, 2017, will be remembered as the day the people became the rulers of this nation again. The forgotten men and women of our country will be forgotten no longer. Everyone is listening to you now. You came by the tens of millions to become part of a historic movement the likes of which the world has never seen before. At the center of this movement is a crucial conviction: that a nation exists to serve its citizens.”
A core finding of the suppressed report is that marketing deals between colleges and banks enrich the banks at the expense of students.
“The bureau and other government entities have expressed concern over the relationship between revenue sharing provisions in contracts and fees charged to student accountholders,” the report says. “These provisions raise questions about potential conflicts of interest, including whether revenue sharing encourages higher-fee financial products that crowd out competition from providers of accounts for which student accountholders” would pay less.
Bank representatives say the report is hooey.
The report found that 573 colleges had marketing agreements. About 1.3 million students paid $27.6 million in fees to 14 banks and credit unions in the 2016-17 academic year, the report states.
In a form of what is apparently a legal kickback, 116 colleges were paid $16.7 million by banks and credit unions to promote financial accounts in 2017, deals designed to capture young customers whose financial resources would be expected to grow over time. PNC Bank paid colleges $7.6 million, U.S. Bank paid $3.2 million and Wells Fargo paid $2.1 million.
Significantly, lower fees were paid by students at the 457 colleges which did not get kickbacks. The estimated 839,000 students at colleges without marketing agreements paid $11.93 on average in fees, compared with $36.52 for the 482,000 students who used accounts at colleges with marketing agreements.
These fees differences indicate there is no enforcement of a 2015 Obama era rule by the Education Department requiring colleges to exercise reasonable diligence to make sure that under marketing agreements with banks students pay fees “consistent with or below prevailing market rates.”
==
trump transition team:
The placement of all these lobbyists as de facto — or actual — high-level agency staffers “raises the appearance that you could be attempting to influence public policy in favor of your former client,” said Meredith McGehee, chief of policy, programs and strategy at Issue One. “This isn’t saying that lobbyists are bad or evil, it’s simply saying the reason that you should have rules governing lobbyists in government is because they have been paid by private interests to promote the interests of their employer.”
It makes a difference whether an individual lobbied last year of 10 years ago, McGehee said. Revolving door restrictions are written with time limits, because it’s understood your relationships with clients and freshness of information cool over time.
One former for-profit college lobbyist has already resigned from his beachhead position at the Department of Education, where he worked for about a month. Taylor Hansen lobbied for Career Education Colleges and Universities until July 2016, where he focused on trying to weaken the “gainful employment” rule that puts for-profit schools’ federal funding at risk if their graduates don’t earn enough to pay back their student loans.
*ProPublica* reported that soon after Hansen started working at Education, the agency began delaying deadlines for the gainful employment rule and is reviewing the implementation of the rule. Hansen told ProPublica he didn’t work on gainful employment while at the department.
OpenSecrets Blog contacted the federal agencies with former lobbyist beachhead members about their ethics policies. The Department of Homeland Security was the only one to get back to us, and its response was vague:
“Ethics training, consistent with U.S. Office of Government Ethics regulations, is provided to all political appointees,” said DHS spokesman David Lapan in an email. “DHS ethics attorneys conduct reviews for potential conflicts of interest and provide guidance to employees.”
Nine beachhead members were registered lobbyists as recently as last year; eight of them have filed forms with the Senate deregistering from that work. General Mills has not filed paperwork that shows Erika Baum ending her lobbying gig at the food company, although she is now an executive assistant to the Secretary of Transportation, according to ProPublica‘s data and lobbying records....
==
ref
https://www.bloomberg.com/news/articles/2017-03-20/betsy-devos-hands-victory-to-loan-firm-tied-to-adviser-who-just-quit
Americans who default on some of their federal student loans are likely to pay more after Education Secretary Betsy DeVos reversed an Obama administration directive limiting some fees. But it turns out the Trump administration decision has some beneficiaries — including the father of a key DeVos lieutenant who just quit.
DeVos's decision, announced Thursday in a memorandum to the student loan industry, allows companies known as guaranty agencies to charge distressed student debtors fees equivalent to 16 percent of their total balance, even when borrowers agree within 60 days to make good on their bad debt.
The reversal is almost certain to hand United Student Aid Funds Inc., the nation's largest guaranty agency, a victory in its two-year legal battle against her department. The fees could translate into an additional $15 million in annual revenue for the company, filings in a related lawsuit suggest. Until Jan. 1, United Student Aid Funds was led by Bill Hansen, who served as Deputy Secretary of Education under President George W. Bush. His son, Taylor Hansen, a former for-profit college lobbyist, was until three days ago one of the few DeVos advisers with professional experience in higher education.
The younger Hansen resigned from the Education Department on Friday, department spokesman Jim Bradshaw said in an email. Hansen couldn't be immediately reached for comment on his departure.
Ben Miller, senior director for postsecondary education at the Center for American Progress, a persistent critic of the new Republican administration, said on Twitter the rule change was "an early Father's Day gift in the Hansen household." Sen. Elizabeth Warren, a Massachusetts Democrat, was equally blunt: "There's no question" that Taylor Hansen's family ties posed a conflict of interest.
Tens of millions of dollars in revenue was at stake for companies such as United Student Aid Funds, which until 2015 had regularly charged borrowers the fee.A senior executive there last year warned in a court filing that the Obama administration's decision to prohibit the fees-and to remind the industry that such fees had long been banned-generated "potentially massive retroactive liability" for companies such as United Student Aid Funds in the form of federal fines and lawsuits from aggrieved debtors. The company reckons it levied as much as $119 million in these fees from 2007 to 2015, or about $15 million annually.
Meanwhile, other companies active in student loan matters faced the prospect of having to reverse years of assessed fees and unravel tens of thousands of borrowers' accounts to recalculate their balances, according to a legal filing last year by the National Council of Higher Education Resources, a Washington trade association. Had the Obama administration's decision stood, a federal judge warned in 2015 that the entire student loan industry faced the prospect of being sued for allegedly violating anti-racketeering laws by imposing the fees.
DeVos's decision is likely to put those concerns to rest.
With almost all senior positions at the Education Department vacant — and few political hires with professional experience in higher education — the younger Hansen may have wielded significant influence on DeVos's policies. With his departure, the department has yet another post to fill.
"We have no idea what Betsy DeVos thinks about or wants to do on higher education policy. If one of the key people advising her is someone whose close family member is hoping to charge defaulted borrowers a lot more money, that's not a good sign of her agenda," Miller said before the department announced Taylor Hansen's exit.
Both the Education Department and Bill Hansen's current organization, of which he is chief executive, Strada Education Network (formerly known as USA Funds), said there's no impropriety.Taylor Hansen recused himself from "all matters" related to United Student Aid Funds' lawsuit challenging the Obama administration directive, Bradshaw said. "He served ably and without conflict and decided his service had run its course," Bradshaw said Monday, declining further comment. But it's unclear whether Taylor Hansen's recusal extended to internal department discussions over the appropriateness of the fees. Bradshaw didn't answer additional questions, and Taylor Hansen didn't respond to emails, phone calls, and a message sent on social network LinkedIn seeking comment.
Bob Murray, a spokesman for Bill Hansen, said no one representing the company had asked Taylor Hansen to intervene on its behalf in its dispute with the department. Furthermore, he said, United Student Aid Funds is now owned by Great Lakes Higher Education Corp. Murray said that Bill Hansen declined to comment.
United Student Aid Funds said in court filings that the Obama administration unfairly changed longstanding Education Department policy when it announced in 2015 that fees added to quickly resolved defaulted loans were illegal. For example, according to industry lobby National Council of Higher Education Resources, the department had never flagged the fee as inappropriate in any of the more than 135 audits or reviews it conducted of companies such as United Student Aid Funds since 1992. The feds, the group said, "knowingly acquiesced for years." In the eyes of the industry, DeVos is simply righting a wrong by reversing Obama's move.
Bill Hansen nonetheless benefits from DeVos' decision. Strada is still liable for potential costs stemming from United Student Aid Funds' lawsuit against the Education Department, as well as a related class action lawsuit filed by borrowers over the same issue, said Richard George, chief executive of Great Lakes.
United Student Aid Funds reached a proposed settlement in January to resolve the proposed class action, filed by Minnesota resident Bryana Bible in 2013 on behalf of borrowers charged what she alleged to be illegal fees. The deal calls for 35,516 borrowers, and their lawyers, to split $23 million to partially reimburse them for as much as $119.1 million in fees assessed over eight years that, under Obama administration guidelines, they shouldn't have been charged. A federal judge is due to decide on the proposed settlement in June.
The now-permissible fees could also beneficially impact Strada's future revenue under an agreement that calls for Great Lakes to give Strada grants partly based on how United Student Aid Funds' loans perform, a person familiar with the matter said. When annualized, the fees represent about 13 percent of United Student Aid Funds' average annual income over the past five years, according to its financial reports.
For struggling borrowers, said Rohit Chopra, a senior fellow at the Consumer Federation of America who previously advised Obama's Education Department and was the top student loan official at the federal Consumer Financial Protection Bureau, "this just adds insult to injury."
Business Briefing from St. Louis Post-Dispatch
\no lnx
==
==
https://www.alternet.org/ending-secrecy-student-debt-crisis
Gamblers and reality TV stars can claim bankruptcy protections when in financial trouble, but 44 million student loan borrowers can’t. Unemployed, underpaid, destitute, sick, or struggling borrowers simply aren’t able to start anew.
With a default rate approaching 40 percent, one would expect armies of distressed borrowers marching in the streets demanding relief from a system that has singled out their financial anguish. Distressed student debtors, however, seem to be terror-struck about coming forward to a society that, they say, ostracizes them for their inability to keep up with their finances.
When we spoke to several student borrowers, almost none were willing to share their names. “I can’t tell anyone how much I’m struggling,” says a 39-year-old Oregon physician who went into student loan default after his wife’s illness drained their finances. He is terrified of losing his patients and reputation if he speaks out about his financial problems.
SPONSORED
“If I shared this with anyone they will look down upon me as some kind of fool,” explains a North Carolina psychologist who is now beyond retirement age. He explains that his student debt balance soared after losing a well-paying position during the financial crisis, and that he is struggling to pay it back.
Financial shame alienates struggling borrowers. Debtors blame themselves and self-loathe when they can’t make their payments, explains Colette Simone, a Michigan psychologist. “There is so much fear of sharing the reality of their financial situation and the devastation it is causing in every facet of their lives,” she says. “The consequences of coming forward can result in social pushback and possible job–related complications, which only deepen their suffering.”
Debtors are isolated, anxious, and in the worst cases have taken their own lives. Simone confirms that she has “worked with debtors who were suicidal or had psychological breakdowns requiring psychiatric hospitalization.”
With an average debt of just over $37,000 per borrower for the class of 2016, and given that incomes have been flat since the 1970s, it’s not surprising that borrowers are struggling to pay. Student loans have a squeaky-clean reputation, and society tends to view them as a noble symbol of the taxpayers’ generosity to the working poor. Fear of facing society’s ostracism for failure to pay them back has left borrowers alienated and trapped in a lending system that is engulfing them in debt bondage.
“Alienation impacts mental health issues,” says New York mental health counselor Harriet Fraad. “As long as they blame themselves within the system, they’re lost.”
Student debtors can counter despair by fighting back through activism and political engagement, she says. “Connection is the antidote to alienation, and engaging in activism, along with therapy, is a way to recovery.”
Despite the fear of coming forward, some activists are building a social movement in which meaningful connections among borrowers can counter the taboo of openly admitting financial ruin.
Student Loan Justice, a national grassroots lobby group, is attempting to build this movement by pushing for robust legislationto return bankruptcy protections to borrowers. The group has active chapters in almost every state, with members directly lobbying their local representatives to sign on as co-sponsors to HR 2366. Activists are building a supportive community for struggling borrowers through political agitation, local engagement, storytelling, and by spreading a courageous message of hope that may embolden traumatized borrowers to come forward and unite.
Julie Margetaa Morgan, a fellow at The Roosevelt Institute, recently noted that student debt servicers like Navient have a powerful influence on lawmakers. “Student loan borrowers may not have millions to spend on lobbying, but they have something equally, if not more, powerful: millions of voices,” she says.
A recent manifesto by activist and recent graduate Eli Campbell calls for radical unity among borrowers. “Young people live in constant fear that they’ll never be able to pay off their debt. We’re not buying houses or able to afford the hallmarks of the American dream,” he explains.
In his call for a unified national boycott of student loan payments, inevitably leading to a mass default on this debt, Campbell hopes to expose this crisis and instigate radical change. In a recent interviewhe explained that the conditions for borrowers are so bad already that debtors may not join the boycott willingly. Instead, participation may simply happen by default given the lack of proper work opportunities that lead to borrowers’ inability to pay.
While a large-scale default may not happen through willful and supportive collective action, ending the secrecy of the crisis through massive national attention may destigmatize the shame of financial defeat and finally bring debtors out of the isolation that causes them so much despair.
Activists are calling for a significant conversation about the commodification of educating our youth, shifting our focus toward investing into the promise of the young and able, rather than the guarantee of their perpetual debt bondage. In calling for collective action they soothe the hurt of so many alienated debtors, breaking the taboos that allow them to say, “Me, too” and admit openly that in this financial climate we all need each other to move forward.
-
https://www.bloomberg.com/graphics/2017-fannie-freddie-friends/
==
In education news,the top federal consumer watchdog for student loans has resigned and accused the Trump administration of siding with predatory lenders over the nation’s student loan borrowers. Seth Frotman worked as student loan ombudsman under Mick Mulvaney, the acting head of the Consumer Financial Protection Bureau. In his resignation letter to Mulvaney, Frotman wrote, “Unfortunately, under your leadership, the Bureau has abandoned the very consumers it is tasked by Congress with protecting. Instead, you have used the Bureau to serve the wishes of the most powerful financial companies in America.” Frotman’s resignation comes as outstanding student loan debt has topped $1.5 trillion.
==
econ update 8/24/18
1.5trillion $ more than credit card, study, lead to house foreclosure, more damage than benefit // prison vs college cost? corp profit? irrational
==
cnbc no lnx tips
Why buying a home can be almost impossible with massive student loan debt
Eighty-three percent of people ages 22 to 35 with student debt who haven't bought a house yet blame their educational loans.
Owning a home, the most common way Americans build wealth, can become a distant dream for many crushed by student debt.
Annie Nova | @AnnieReporter
Published 11:07 AM ET Thu, 19 April 2018 Updated 8:55 AM ET Fri, 20 April 2018
In the late 1990s, Ed McKinley fell in love with a $65,000 house by a lake in New Hampshire.
The owners let him move in early and pay rent until the buying process was completed.
Inside his new home, McKinley installed a modern stove, painted the walls and began to redo the floors.
Then came the bad news.
"The mortgage company decided that my income-to-debt ratio was a little bit higher than they were comfortable with," McKinley, 59, said.
They were referring to his $34,000 in federal student loan debt.
He had to pack up and leave.
"It's crushing," McKinley said, choking up. "I have a very strong desire to own a piece of land that I can put my signature on."
Student loan debt has become a major barrier to home ownership in America.
Some 45 million people in the United States carry student debt. The average borrower owes more than $30,000, according to Student Loan Hero, a website for managing education debt. Almost a fifth owe more than $100,000, according to the National Association of Realtors.
People's monthly student loan payments can eat up a large slice of their income, threaten to push down their credit scores and make saving nearly impossible — all huge impediments, of course, to landing in a house.
For every 10 percent in student loan debt a person holds, their chance of home ownership drops 1 to 2 percentage points during their first five years after school, according to the Federal Reserve.
More than 80 percent of people ages 22 to 35 with student debt who haven't bought a house yet blame their educational loans, according to the National Association of Realtors.
Student debt could hold back economic growth, Fed chief says Student debt could hold back economic growth, Fed chief says
"Student loan debt holders do want to own a home, that's part of their American dream," said Jessica Lautz, managing director of survey research at the National Association of Realtors. "It's just really hard to get there right now."
To be sure, people who receive more education also tend to earn higher incomes, possibly offsetting some of the financial distress of student loan debt, said Jonathan Spader, a senior research associate at the Joint Center for Housing Studies at Harvard University.
"You have these competing influences of greater access to education versus reduced ability to buy a home because of student loan debt," Spader said.
Challenge one: Debt-to-income ratio
Almost one-fifth of people with student debt who apply for a mortgage — like McKinley — are denied because of their "debt-to-income ratio," what a person owes versus how much they make, according to the National Association of Realtors.
The median income for student loan borrowers is $59,746, according to analysts at the Harvard joint center. For borrowers under 30, the average monthly loan payment is $351, according to Student Loan Hero.
"The bank looks at it as 'unsecured debt,'" said Doug Amis, a certified financial planner at Cardinal Retirement Planning in Cary, North Carolina. "With a mortgage, you have the asset of the house. If you stopped paying, you could foreclose on the house. But you can't go and foreclose on an education."
In other words: Banks know you'll most likely be stuck with your student debt until you pay it off.
"The mortgage officer wants to see that your overall expenditures on housing and debt — including student loans and car payments — is not more than 36 percent of your income," Amis said. "That's really going to limit things if you're only making $50,000 a year."
In certain areas where the cost of living is higher, that debt ceiling is pushed up.
Challenge two: Credit score
Eight percent of student loan borrowers are denied a mortgage because of their credit score, according to the National Association of Realtors.
Mike, a government worker in Yukon, Oklahoma, said banks offering loans would line up at his law school at the University of Toledo. (He asked to use his first name only because of his job with the government.) He graduated in 2008, with more than $200,000 in debt, into the Great Recession.
He couldn't find a job and soon defaulted on his student loans, like 40 percent of borrowers are expected to do by 2023, according to the Brookings Institution.
He felt helpless.
"I just ignored it, there was no way — they were wanting $1,200 a month," Mike said.
His credit score sank into the low 500s, which is considered very poor by credit data company Experian.
"If I went into any bank in Oklahoma, they would just laugh at me," Mike said.
Challenge three: Down payment
And he's not alone, 85 percent of student loan borrowers say difficulty in saving has delayed their ability to buy a house, according to the Realtors association.
"It's challenging with student loans to be able to put together $40,000," said Grant Simmons, vice president of search marketing for Homes.com.
(The median home price in America is $241,700.)
Stephanie Pennycuff graduated from Indiana University-Purdue University Indianapolis with $43,000 in student debt.
She works at a nonprofit, helping formerly incarcerated people transition into their communities, making around $30,000. Her monthly student loan payment is $450.
That's made accumulating money almost impossible.
"Pretty much one paycheck a month goes to loans," Pennycuff, 28, said. "Every time I manage to save up a couple of thousand dollars, something happens and it's immediately drained back to nothing. I can't put down any sort of payment on a home."
More from Personal Finance:
Trump opens a door to student loan forgiveness
College students use financial aid money to invest in bitcoin
Graduates of this college get a starting salary of $80,000
As student debt continues to compound, the primary way many Americans build wealth and stability — through owning a house — is likely to become more endangered.
In the two decades after McKinley was forced to leave, he's still been stuck renting. His loans have wavered in and out of default and mushroomed to more than $100,000.
Sometimes he drives past the house that was almost his.
"There was a lot of wildlife, opportunities for outdoor recreation," McKinley said. "It was really beautiful there."
He imagines what would have happened had he been able to stay. His monthly mortgage payments were going to be around $500 a month. He might have even paid them all off by now, he figures.
And the last time he checked, the house's value had swelled from $65,000 to more than $200,000.Why buying a home can be almost impossible with massive student loan debt
==
https://www.cnbc.com/2018/05/31/young-people-choosing-between-paying-for-college-and-buying-homes.html
no lnx, vids
More and more young people have to choose between paying for college and buying a home
Megan Leonhardt | @Megan_Leonhardt 11:51 AM ET Thu, 31 May 2018
Millennials are making a big mistake by not owning a home, says one financial expert Millennials are making a big mistake by not owning their homes, says one financial expert
Millennials increasingly face a difficult decision: pay off student loans or buy a home. That's because doing both is increasingly impossible.
Thanks to soaring college costs starting in the early 2000s, millennials, more than any other generation, were forced to take out massive student loans to pay for their degrees. A decade or so later, they're still not in the black. In fact, student loans currently account for roughly $1.4 trillion of U.S. debt. Today, about one in four millennials has some form of student debt, according to Pew, with those holding a bachelor's degrees carrying about $25,000. And some, of course, have more, even, in some cases, hundreds of thousands of dollars in debt they fear they'll never be able to repay.
That level of student loan debt is not only causing financial stress — it's also keeping millennials from becoming home-owners, which denies them long-term stability and wealth they could eventually pass on to their own children.
Tony Robbins shares why being a millennial homeowner isn't the smartest move Here's how Tony Robbins suggests millennials approach buying homes
A college degree is still worth having: Studies consistently show that a BA provides more secure employment, higher lifetime earnings and even a longer life expectancy. But if you have to pay for it yourself, a college degree doesn't give you enough of a boost to enable you to balance debt and saving for a home at the same time. Over 80 percent of those between the ages of 22 and 35 who have student loans say that debt is the biggest factor holding them back from purchasing a home, according to research by the National Association of Realtors.
The New York Federal Reserve also found that the roughly 35 percent drop in home owners between the ages of 28 and 30 over the eight-year period starting in 2007 was due, in part, to student loan debt. (The other major factor, of course, was the housing crash and foreclosure crisis that started in 2008.) Going a step further, the Fed found that, if student loan levels had remained at 2001 levels, more than 360,000 of those millennials would have achieved home-ownership.
"If people had the same levels of student debt as about 20 years ago, they probably would be buying a lot more homes than they are buying now," Wilbert van der Klaauw, author of the study, tells the New York Times, which concludes, "College loans have made mortgages a pipe dream."
Indeed, the more student loan debt you have, the less likely you'll be to own a home: The New York Fed found that those with $25,000 in student loans will have a substantially lower chance of owning a home by the time they hit age 33 than their debt-free counterparts.
Among older millennials, those aged 29-38, less than a third own a home, the NAR found. And younger millennials fare no better, with only 11 percent achieving home-ownership. Those rates are part of a wider trend that shows home-ownership among those in the 20s and 30s is at an almost 30-year low.
Sadly, that trend is unlikely to change anytime soon. Although the vast majority of millennials say they'd like to purchase a home, most are about a decade away from having the savings to do so, according to 2017 data from Apartment List.
“You do not want to give Jeff Bezos a seven-year head start.”
Hear what else Buffett has to say
A lot still depends on where millennials are looking to buy and their savings rates. For example, the research found that those in Miami may be able to afford a home in a little over six years. Residents of San Jose, Calif., meanwhile, will likely need to save for over 20 years.
Don't miss: Two Harvard presidents agree that Americans need to rethink how they view college
Like this story? Like CNBC Make It on Facebook!
This NYU student paid his four-year $200,000 tuition bill on his own and without student loans — here's how he did it This NYU student paid his four-year $200,000 tuition bill on his own and without student loans — here's how he did it
Megan Leonhardt
Sr. Money Writer, Make It
818 AN
*****
In the latest of her many rollbacks of Obama-era rules designed to protect students from for-profit college scams -- like Trump's own defunct university -- Education SecretaryBetsy DeVos announced plans to kill the "gainful employment rule," which "sought to punish for-profit college programs that left graduates with heavy debt compared to their incomes."
According to Collin Binkley at *The New Republic*,it was "the second planned rollback of a major Obama-era rule in a matter of weeks. On July 25, DeVos proposed changes to the so-called borrower defense rule to toughen the process by which defrauded students can get their loans erased."
******
==
Education and consumer protections
June 14, 2017
Borrower Defense Rule
California filed a motion to defend the loan-forgiveness process for students defrauded by their schools after the Department of Education announced plans to overhaul the rule. The department eventually cut back forgiveness. Read more
Result: Case is pending
Jan. 16, 2018
Net neutrality
California filed suit against the Federal Communications Commission challenging its attempt to repeal net neutrality rules. Read more
Result: Petition to block FCC action was rejected, state Legislature is moving to impose statewide net neutrality rules
WINNER: CALIFORNIA
http://www.latimes.com/projects/la-pol-ca-california-vs-trump-lawsuits/
==
2017
end of summer fast approaching comes another year of rising college tuition costs and looming student loans.
College tuition has increased over the past several decades, but in the last 10 years the average cost of tuition for four-year public colleges and universities has grown at a lower rate than previous decades. Still, the price tag for college is not cheap. For the average four-year public institution, tuition can cost about $9,650, according to College Board. The average tuition total for private non-profit institutions is more than triple that at $33,480.
These high tuition costs have inevitably led to more students taking out loans in order to afford their education. Across the United States, there are more than 44 million student loan borrowers who have accrued approximately $1.3 trillion in student loan debt, according to Forbes.
The student loan industry is a major player in money in politics, but was not as active in 2016 as it has been in the past. For the 2016 election cycle, student loan companies gave just over $982,000 in contributions to federal candidates, parties and outside groups. The industry reported more than $1 million in contributions for both the 2014 and 2012 cycles.
Roughly three-quarters of the industry’s contributions for 2016 went to Republican candidates and parties. The student loan industry has allocated more of its contributions to Republicans than Democrats in every cycle since 1996.
The top three student loan companies making campaign contributions in 2016 were College Loan Corp with $668,000 donated, Navient Corp with almost $283,000, and NelNet Inc with just under $168,000. All three companies gave the majority of their contributions to Republican and conservative candidates and parties.
Student loan companies are even more active in the lobbying world, spending more than $4.4 million on lobbying efforts in 2016. The top lobbying client by far in 2016 was Navient Corp with more than $2 million spent. Other major lobbying spenders for the industry last year were NelNet Inc and SLM Corp with $620,000 and $570,000, respectively.
Last year these companies mainly lobbied on issues related to student loans, particularly federal credit programs, student borrowing and loan servicing, IRS private debt collection and Title IV of the Higher Education Act, which aims to make grants and other benefits available to eligible students seeking post-secondary education. So far in 2017, student loan companies have spent roughly $3.6 million on lobbying.
Student loan companies aren’t the only ones getting political — colleges and universities are, too. For the 2016 election cycle, the education industry had a record-high contribution totalof almost $81 million. Nearly all of this money is donated by school employees, such as professors, since most non-profit educational institutions do not have political action committees. Of the contributions to political candidates and parties, Democrats received 86 percent — the most significant liberal lean in the industry’s history. Since 1990, the education industry has never given less than 58 percent of its contributions to Democrats, with an overall average of 77 percent going to the left.
The higher education institutions with affiliates who gave the most money during the 2016 election were theUniversity of California system (roughly $4.4 million), Stanford University (almost $2.3 million) and Harvard University (more than $1.6 million). Every university among the sector’s top 20 donors made at least 83 percent of its contributions to Democrats.
Democratic presidential nominee Hillary Clinton received the most money from the education industry in 2016 by far, with a total of approximately $23.7 million. Her primary challenger Sen. Bernie Sanders (I-Vt.) came in second with almost $5.5 million, while her general election opponent Donald Trump was further down the list of top recipients at No. 8, with a total of about $778,000.
In recent years, the education industry’s lobbying spending has been on a downward slope, and 2016 was no exception. The industry’s lobbying total was about $74.4 million — over $3.6 million less than its 2015 total and $35 million short of the industry’s record-high lobbying total from 2010.
Last year, the biggest lobbying clients in the education industry were the Association of American Medical Colleges (more than $2.8 million), Apollo Education Group (about $1.4 million) and the education-related subsidiaries of Warburg Pincus (just over $1.1 million). The top education-related issues these groups focused on included cuts to graduate and professional student loan benefits, global health learning opportunities, financial aid (including Pell Grants), campus sexual assault and post 9/11 G.I. bill benefits.
RELATED TOPICS
- 2016 election
- Bernie Sanders
- college
- contributions
- democrat
- Donald Trump
- education
- education industry
- financial aid
- Harvard University
- higher education
- Hillary Clinton
- industry
- influence
- lobbying
- republican
- sara swann
- Stanford University
- student loan companies
- Student Loans
- students
- university
- University of California
https://www.opensecrets.org/industries./indus.php?ind=F1410
| Navient Corp |     $258,560 |
|---|---|
| College Loan Corp | $116,000 |
| NelNet Inc | $72,477 |
| Sallie Mae | $31,176 |
Contributions to:
Democrats
Republicans
Liberal Groups
Conservative Groups
2018
1 Guthrie, Brett (R-KY) House $15,000
2 Messer, Luke (R-IN) House $13,576
3 Heinrich, Martin (D-NM) Senate $12,000
4 Foxx, Virginia (R-NC) House $11,500
5 Bloom, Stephen (R-PA) $10,800
5 Mooney, Alex (R-WV) House $10,800
7 Perlmutter, Ed (D-CO) House $10,000
7 Scalise, Steve (R-LA) House $10,000
9 Moore, Roy (R-AL) $8,100
10 McHenry, Patrick (R-NC) House $7,500
11 Sasse, Ben (R-NE) Senate $6,000
12 Sinema, Kyrsten (D-AZ) House $5,500
13 James, John (R-MI) $5,400
13 Fulcher, Russ (R-ID) $5,400
13 Sanford, Mark (R-SC) House $5,400
13 Davidson, Warren (R-OH) House $5,400
13 Saccone, Rick (R-PA) $5,400
13 Perry, Scott (R-PA) House $5,400
13 Roy, Chip (R-TX) $5,400
13 Gohmert, Louis B Jr (R-TX) House $5,400
1Guthrie, Brett (R-KY)House$15,0002Messer, Luke (R-IN)House$13,5763Heinrich, Martin (D-NM)Senate$12,0004Foxx, Virginia (R-NC)House$11,5005Bloom, Stephen (R-PA)$10,8005Mooney, Alex (R-WV)House$10,8007Perlmutter, Ed (D-CO)House$10,0007Scalise, Steve (R-LA)House$10,0009Moore, Roy (R-AL)$8,10010McHenry, Patrick (R-NC)House$7,50011Sasse, Ben (R-NE)Senate$6,00012Sinema, Kyrsten (D-AZ)House$5,50013James, John (R-MI)$5,40013Fulcher, Russ (R-ID)$5,40013Sanford, Mark (R-SC)House$5,40013Davidson, Warren (R-OH)House$5,40013Saccone, Rick (R-PA)$5,40013Perry, Scott (R-PA)House$5,40013Roy, Chip (R-TX)$5,40013Gohmert, Louis B Jr (R-TX)House$5,400
2016
1 Murray, Patty (D-WA) Senate $19,000
2 Foxx, Virginia (R-NC) House $16,700
3 Sasse, Ben (R-NE) Senate $15,400
4 Biggs, Andy (R-AZ) $13,500
4 Paul, Rand (R-KY) Senate $13,500
6 Meadows, Mark R (R-NC) House $13,100
7 Scott, Bobby (D-VA) House $13,000
8 Thomas, Mary (R-FL) $10,800
8 Mandel, Josh (R-OH) $10,800
8 Johnson, Mike (R-LA) $10,800
8 Bridenstine, James (R-OK) House $10,800
12 Brat, Dave (R-VA) House $10,600
12 King, Steven A (R-IA) House $10,600
14 Ashford, Brad (D-NE) House $10,000
15 Scott, Tim (R-SC) Senate $9,900
16 Gosar, Paul (R-AZ) House $8,100
16 Heck, Joe (R-NV) House $8,100
18 Amash, Justin (R-MI) House $7,900
19 Huelskamp, Tim (R-KS) House $7,700
20 Fortenberry, Jeff (R-NE) House $7,500
1Murray, Patty (D-WA)Senate$19,0002Foxx, Virginia (R-NC)House$16,7003Sasse, Ben (R-NE)Senate$15,4004Biggs, Andy (R-AZ)$13,5004Paul, Rand (R-KY)Senate$13,5006Meadows, Mark R (R-NC)House$13,1007Scott, Bobby (D-VA)House$13,0008Thomas, Mary (R-FL)$10,8008Mandel, Josh (R-OH)$10,8008Johnson, Mike (R-LA)$10,8008Bridenstine, James (R-OK)House$10,80012Brat, Dave (R-VA)House$10,60012King, Steven A (R-IA)House$10,60014Ashford, Brad (D-NE)House$10,00015Scott, Tim (R-SC)Senate$9,90016Gosar, Paul (R-AZ)House$8,10016Heck, Joe (R-NV)House$8,10018Amash, Justin (R-MI)House$7,90019Huelskamp, Tim (R-KS)House$7,70020Fortenberry, Jeff (R-NE)House$7,500
==
https://www.commondreams.org/news/2018/04/03/more-one-third-college-students-struggle-food-and-housing-insecurity-study-finds
While higher education has historically been promoted as a "great equalizer," new research offers the latest evidence that poverty and economic inequality continue to inhibit the realization of that promise.
A studyby the Wisconsin HOPE Lab and Temple University found that about 36 percent of students struggle with food insecurity, or inadequate access to nutritious food, while more than a third also face housing insecurity—defined as the inability to pay rent or utilities or the need to move frequently.
The researchers documented the experiences of 43,000 college students at more than 60 public and private universities as well as community colleges—the largest-ever national survey assessing whether the basic needs of students are being met.
"The data show that basic needs insecurities disproportionately affect marginalized students...However, the level of academic effort—in and outside the classroom—is the same regardless of whether or not students are dealing with food and housing insecurity." —Wisconsin HOPE Lab and Temple UniversityIn addition to the large percentage of students who were found to lack adequate housing and food, about nine percent of students reported homelessness in the 30 days leading up to the survey. Community college students struggled more than those at universities and private colleges, with 46 percent of students at two-year institutions reporting that they couldn't afford balanced meals, 37 percent saying their food supplies ran out before they could afford to buy more, and nine percent saying they had involuntarily gone a whole day without eating.
"The data show that basic needs insecurities disproportionately affect marginalized students," reads the study. "...However, the level of academic effort—in and outside the classroom—is the same regardless of whether or not students are dealing with food and housing insecurity. It is therefore critically important to match their commitments with supports."
The report comes as students at Howard University are in their sixth straight day of protests which erupted last week in response to alleged corruption in the school's financial aid department, but has also focused on housing insecurity in the student body amid "unsubstantiated tuition hikes" and a lack of transparency regarding administrators' salaries.
In its list of demands, the protesters denounced the university for leasing three dormitories to real estate developers, resulting in inadequate on-campus housing for students, and noted, "Since 2008, the cost of tuition has nearly doubled while the median household income of African-American households has decreased," potentially adding to financial difficulties for students.
Howard students are far from alone, as average room and board fees for undergraduate students climbed to nearly $10,000 in the 2013-2014 school year, according to the National Center for Education Statistics—50 percent higher than what families were asked to pay just 20 years ago.
"There has been an uptick in low-income students on campus, but there hasn't been a corresponding change in university policy to welcome and prepare for these students," Anthony Abraham Jack, an assistant professor at the Harvard Graduate School of Education, told theWashington Post.
To respond to growing needs on college campuses, more universities are establishing food banks for students. The College and University Food Bank Alliance (CUFBA) has grown from 12 members in 2012 to 591 members as of February 2018, according to Wisconsin HOPE Lab.
"Better understanding how students experience and cope with basic needs security is essential for designing effective interventions and policies," reads the study. "Researchers have begun to document some of these supports, including case studies of specific programs and comparisons of varying responses across institutions. To ensure that students are receiving the help they need, researchers now must focus on rigorously evaluating existing interventions."
https://www.alternet.org/news-amp-politics/warren-refuses-play-dead-big-banks
Thanks to the help of 16 Senate Democrats and Sen. Angus King (I-Maine), a Wall Street deregulation measure disguised as a "community banking" bill is barreling toward passage—but Sen. Elizabeth Warren (D-Mass.) vowed Wednesday to not let the bill sail through without forcing votes on a series of amendments aimed at showing Americans whose side their lawmakers are really on.
"The fight over the Bank Lobbyist Act isn't over yet," Warren wrote on Twitter, unveiling 17 amendments that, if approved, would uphold strict oversight of big banks and shield consumers from Wall Street fraud and abuse. "I'm not going to roll over and play dead for the big banks."
First introduced last November by Sen. Mike Crapo (R-Idaho), the officially named "Economic Growth, Regulatory Relief, and Consumer Protection Act" (S.2155) could hit the Senate floor for a final vote as soon as Thursday after it easily cleared a procedural hurdle earlier this week.
Far from what its title suggests, progressive lawmakers and independent analysts argue the legislation would dismantle many consumer protections, provide huge gifts to Wall Street firms, and—according to the Congressional Budget Office (CBO)—significantly increase the likelihood of future taxpayer-funded bank bailouts.
In an effort to let the American people know whether their senators are on the side of "working families or the big banks," Warren announced her plan on Wednesday to push for votes on amendments to the bill that, if implemented in its current form, would "turn over the keys to our economy to the same people who crashed it ten years ago."
"The Senate is expected to pass the #BankLobbyistAct—with Democratic support. But I'm not going down without a fight," Warren declared.
Below is a full list of the amendments accompanied by a short summary of their contents. The full amendments can be viewed on Warren's Twitter page.
1. (#2056) BAILOUTS: This amendment ensures that banks that received more than $1 billion in bailout money during the 2008 financial crisis are still subject to tougher federal oversight.
2. (#2064) DEFERRED PROSECUTION AGREEMENTS: This amendment ensures that banks that are currently operating under a deferred prosecution agreement or a consent order are not deregulated by the bill.
3. (#2063) FINES:This amendment ensures that big banks that have been assessed more than $10 million in fines in the last ten years remain subject to stricter federal oversight.
4. (#2061) OUTSOURCING: This amendment ensures that banks that have outsourced more than 50 jobs in any of the last five years remain subject to stricter federal oversight. The Communications Workers of America support this amendment.
5. (#2060) STOCK BUYBACKS: This amendment prohibits any big bank that gets deregulated under the bill from buying back its stock for the next five years. If the purpose of this bill is to promote lending and economic growth, the banks that benefit from it should not be permitted to funnel any savings into additional stock buybacks.
6. (#2058) MERGERS: This amendment prohibits any big bank that gets deregulated under the bill from merging with or acquiring another bank for five years. Supporters of the bill claim it is intended to reduce consolidation in the banking industry, but experts agree that the bill, as currently written, will spark a wave of new mergers. This amendment will limit that consolidation.
7. (#2067) FREE CREDIT FREEZES:This amendment amends section 301 of the bill to include the full text of Senator Warren's FREE Act. The FREE Act provides for a more consumer-friendly free credit freeze process than the current bill and prohibits credit bureaus from selling data to third parties when a freeze is in effect.
8. (#2065) MANDATORY PENALTIES FOR CREDIT BUREAU DATA BREACHES:This amendment inserts the Warren-Warner Data Breach Prevention and Compensation Act of 2018 into the bill. The bill imposes large, mandatory penalties on credit bureaus that allow personal consumer data to be accessed or stolen.
9. (#2057) NO CREDIT REPORTS IN JOB APPLICATIONS:This amendment inserts Senator Warren's Equal Opportunity for All Act into the bill. The bill prohibits employers from requesting a job applicant's credit report.
10. (#2069) GLASS-STEAGALL: This amendment inserts Warren-McCain-Cantwell-King 21st Century Glass-Steagall Act into the bill. The bill would re-establish the divide between commercial and investment banking.
11. (#2062) CARD ACT EXPANSION: This amendment expands the CARD Act to include other financial products marketed on college campus, including debit cards and checking accounts.
12. (#2059) STUDENT LOAN ARBITRATION: This amendment bans the use of mandatory arbitration clauses in contracts for private student loans.
13. (#2066) DISCLOSING SEXUAL HARRASSMENT:This amendment inserts Senator Warren's Sunlight in Workplace Harassment Act into the bill, which would require publicly-traded companies to disclose the number and dollar amount of workplace harassment and discrimination settlements.
14. (#2070) STUDENT LOAN SERVICING:This amendment grants student borrowers a private right of action against student loan servicers, lenders, and holders, and adds additional requirements for loan servicers to support borrowers throughout the repayment process.
15. (#2068) PRIVATE STUDENT LOANS:This amendment offers consumer protections for private education loan borrowers, including servicing transfer protections, fee prohibitions and protections, and private student loan discharge for borrower death or disability.
16. (#2054) LIMITING IMMUNITY: This amendment amends section 303 of the bill to limit the immunity provided to bank personnel so that they do not receive immunity for violations unrelated to the reporting of financial exploitation of seniors.
17. (#2055) CLOSING WALL STREET LOOPHOLE: Section 165 of Dodd-Frank currently states that the Fed "may" tailor the enhanced prudential standards depending on the size, risk, complexity, and activities of specific banks or categories of banks. Section 401 of S. 2155 says the Fed "shall" tailor these requirements - which, under the bill, now only apply to banks bigger than $250 billion in assets. That one word change gives the biggest Wall Street banks a massive legal hook to challenge Fed requirements and systematically weaken the rules. This amendment would strike the "may" to "shall" change.
==
In a data-driven deep dive, the Huffington Post reports on the rising student debt numbers and weakening 401(k) returns that are hurting Millennials — America's largest generation.
The bottom line:"Millennials are facing the scariest financial future of any generation since the Great Depression," per the Huffington Post's Michael Hobbes.
The numbers for millennials:
- 300% more student debt than their parents, on average.
- 1/2 as likely to own a homeas young people — ages 25–34 — were in 1975.
- One in five of young adults live in poverty.
- 2.9% average annual returns on 401(k) plans, compared to 6.3% returns for baby boomers.
- Many millennials will have to work until the age of 75, based on an analysis of federal data.
- A typical 2009 college graduate could earn up to $58,600 less than a typical 2007 college graduate over a decade, based on current trends.
- The American racial wealth gap is widening, with the median white household projected to have 86 times more wealth than the median black household by 2020.
http://highline.huffingtonpost.com/articles/en/poor-millennials/
==
http://www.alternet.org/education/college-us-more-expensive-any-other-country-world
==
kos
...Yet another story to make the heart drop and the blood pressure soar. The controversial Trump appointmee Betsy Devos, who was bulldozed in by Republicans to head the U.S. Department of Education, was bad enough to many around the country to stomach. Now she reportedly appointed someone with conflicting interests to head the Office of Federal Student Aid (FSA).
NPRreports that James Runice “abruptly” resigned as head of the FSA last month due toclashes with the Trump administration. The vacant position has been filled and will now go to newly appointed Wayne A. Johnson. Though it was not mentioned in the Dept. of Education’s press release, Buzzfeedwas the fist to report that Johnson is currently the CEO of Reunion Financial Services Corporation, a private student loan company. Johnson will now be responsible for “administering $1.4 trillion in outstanding student loans from 42 million borrowers, plus other aid programs for millions of college students.”
Liz Hill, press secretary at the U.S. Department of Education, provided NPR with a statement that read in part: “Dr. Johnson has 30 years of experience in the private sector and is going to be a tremendous asset to the Department and to FSA’s customers [...] Wayne knows this industry inside and out and has seen first-hand the benefits of serving students and helping them meet their financial and educational goals. This is just another reason why we are so excited to have him on the team as we work to put students’ needs first.”
Wayne Johnson may have experience in the student loan industry, but clearly it has been on the side of corporate profit. That’s how CEOs of corporations roll. So, how is it that he is somehow is deemed fit to work with, and be an advocate for our college students in a fair and unbiased way?
NPR adds that the head of the FSA doesn’t require a Senate confirmation. Given the Republican majority in the House and Senate, it’s doubtful Devos would run into any trouble getting her way. After all, she made her way into her current positions via Trump and the Republicans, much to the great dismay of Democrats and citizens around the country who protested her lack of experience, billionaire status, alleged prejudices, and* herrefusal to say she would not discriminate against the LGBT community.
What makes things more disturbing is that it was previously stated by the Dept. of Education that Johnson would leave his current CEO position with Reunion before taking appointment at the FSA. So far, he has not resigned, and it’s unclear why.
The Consumer Financial Protection Bureau, a federal watchdog agency, reported last week that there is a wide range of loan industry practices that reportedly deny consumer protections. The agency also reviewed thousands of consumer complaints from student borrowers between March 2016 and February 2017 and found the number of complaints more than tripled. But let’s put in a corporate billionaire to relate to the day-to-day struggles of mostly poor college students.
Read the NPR’s full story here.
==
http://www.npr.org/sections/ed/2017/06/24/533950485/devos-appoints-ceo-of-a-student-loan-company-to-head-federal-aid-agency
Welcome to this week's edition of our national education news roundup.
DeVos appoints current student loan company CEO to head student loan agency
Wayne A. Johnson will be the new head of Office of Federal Student Aid after James Runcie abruptly resigned last month, the U.S. Department of Education announced this week. FSA is the agency responsible for administering $1.4 trillion in outstanding student loans from 42 million borrowers, plus other aid programs for millions of college students.
As not mentioned in the department's press release, and first reported by BuzzFeed, Johnson is currently the CEO of Reunion Financial Services Corporation, a private student loan company.
Liz Hill, press secretary at the U.S. Department of Education, provided NPR with a statement that read in part: "Dr. Johnson has 30 years of experience in the private sector and is going to be a tremendous asset to the Department and to FSA's customers [...] Wayne knows this industry inside and out and has seen first-hand the benefits of serving students and helping them meet their financial and educational goals. This is just another reason why we are so excited to have him on the team as we work to put students' needs first."
The head of FSA is an appointment that doesn't require Senate confirmation. It's unclear why Johnson did not resign before his appointment was announced. Hill said in the statement, "This goes without saying, but he will separate from the company should he join FSA."
New federal report says student loan borrowers are being denied their rights
Many "borrowers attempting to invoke their rights under federal law ... point to a range of student loan industry practices that delay, defer or deny access to critical consumer protections," the Consumer Financial Protection Bureau, a federal watchdog agency, reported this week. The report reviewed thousands of consumer complaints from student borrowers between March 2016 and February 2017. Over that time, the number of complaints more than tripled.
The report particularly focused on troubles from people enrolled, or trying to enroll, in Public Service Loan Forgiveness, a program that cancels the student loans of people employed in the government or for a nonprofit for at least 10 years. The first group of borrowers is supposed to get their loans forgiven starting this fall, but what the report describes as "servicing breakdowns" is preventing many from enrolling and making progress toward that goal.
DeVos named in civil rights probe
The U.S. Commission on Civil Rights, a congressionally authorized independent watchdog group, announced a two-year investigation of federal civil rights enforcement to be completed by 2019.
Its statement cited President Trump's proposed budget cuts, and "changing ... priorities" as reasons to be concerned about a "dangerous reduction of civil rights enforcement across the country."
DeVos was the only government official named in the statement, which read in part, "These proposed cuts are particularly troubling in light of Education Secretary Betsy DeVos' repeated refusal in Congressional testimony and other public statements to commit that the Department would enforce federal civil rights laws."
As we've reported, DeVos has been questioned repeatedly — and has repeatedly deflected questions — about whether she would uphold the rights of LGBT students at private schools that receive public money, such as vouchers. In the United States, most private schools have religious affiliations.
Wealthy, white communities are seceding to form new school districts
And their secession is taking money from poorer schools, a new report from the nonprofit EdBuild finds.
Since 2000, 71 communities have attempted to secede from their school districts following this pattern; 47 have succeeded.
Thirty states "have processes codified in state law that allow for secession," according to EdBuild. Among those profiled in the report are Tennessee, Louisiana and Colorado— which brings us to ...
Colorado firearms training for teachers
At some schools in Colorado, teachers are undergoing firearms training. The training, offered by an Ohio-based pro-gun group known as Faculty/Administrator Safety Training and Emergency Response, allows "teachers, administrators, and other personnel to stop school violence rapidly" and "administer medical aid where necessary," the BBC reports.
FASTER was organized in the aftermath of the 2012 Sandy Hook shooting, in which 26 teachers, staffers and elementary students were killed. Colorado law allows firearms to be carried in public places provided they are in plain view.
Dallas schools aim for diversity
The Dallas school system, one of the most segregated in the country, is making great efforts to integrate, The New York Times reports.
The district plans to open more than 35 new schools in the next three years, with themes such as single-sex education, science, the arts and dual-language programs, in hopes of enticing more white and college-educated families. They are also taking the unusual step of reserving seats at some schools for students who are not considered low-income, even those who come from outside the district.
The district went from a majority white population before desegregation in 1960 to a 93 percent black and Hispanic student body today. Dallas is one of a few cities pushing for integration, as nationwide, public schools are more segregated than they were in 1970.
Stephens College creates first women's 'esports' team
Video games played as a spectator sport, known as esports, are on the rise, and Stephens College wants to be ahead of the curve. This fall the small private women's college in Columbia, Mo., will have the first all-women's collegiate varsity esports team in the nation.
"There isn't any reason that women shouldn't be competitive in esports, just as they're competitive at any other sport," the president of Stephens College, Dianne Lynch, told KOMU. The school will also offer esports scholarships.
civil rights, student debt
http://www.alternet.org/education/betsy-devos-undermines-civil-rights
...RANDI WEINGARTEN: Look, the great thing is that 18—you know, we went to—we went to the attorney generals. It is fantastic that the attorney generals, 18 or 21 of them, are now, you know, suing to enforce the borrower defense law—or, regulation. I mean, what this essentially means—let me just—because those are code words. What this essentially means is that Corinthian College went bankrupt. All these kids were left holding the bag, with the student debts. What the borrower defense law means—or, rule means, is that just like Corinthian gets its debts discharged in bankruptcy, these kids should not be holding the bag. That’s what it means. So, the AGs are suing on that. And look, we—thankfully, we were able, in a bipartisan way, to get the new federal law covering K-12 passed last year in the Congress. And even Lamar Alexander just said to Betsy DeVos, "You’re misreading the law."
AMY GOODMAN: I wanted to ask you about—well, NPR is reporting Wayne Johnson will be the new head of Office of Federal Student Aid, after James Runcie abruptly resigned last month.
[
http://www.npr.org/sections/ed/2017/05/25/529560167/why-did-the-top-student-aid-official-under-betsy-devos-resign
]
RANDI WEINGARTEN: Right.
AMY GOODMAN: This is according to the Department of Education. FSA is an agency responsible for administering $1.4 trillion in outstanding student loans from 42 million borrowers, plus aid programs for millions of college students. As not mentioned in the department’s press release and first reported by BuzzFeed, Johnson is currently the CEO of Reunion Financial Services Corporation, a private student loan company.
RANDI WEINGARTEN: Right. I mean, this is—I don’t think saying the fox guarding the hen house is enough to describe what is going on. You basically have people from an industry that bilked kids, that have had predatory practices, now running the student aid programs. And it’s just—again, it is this preference, this out-and-out preference for the lenders, for the for-profit colleges, that we have fought for the last several years. Like, you can’t give worthless degrees and leave kids holding the bag with unsustainable debt. And basically, we are winding back the clock on this, as well as on rights.
AMY GOODMAN: Well, Randi Weingarten, we want to thank you very much for being with us, president of the American Federation of Teachers, as we move on to other education news.
==
npr:
The sudden resignation of an Obama appointee who oversaw student aid at the U.S. Department of Education has brought forth competing explanations.
James Runcie managed the Federal Student Aid office, which administers $150 billion in grants, loans and work-study funds that help 13 million students pay for college each year. The announcement of his resignation came a day after the Trump administration called for large cuts to these aid programs and on the same morning that Runcie's boss, Education Secretary Betsy DeVos, was testifying about those cuts on Capitol Hill.
"I cannot in good conscience continue to be accountable as Chief Operating Officer given the risk associated with the current environment at the Department," Runcie wrote in his resignation memo, which was confirmed by NPR.
Reaction to his departure split along partisan lines.
Statements by DeVos' office, as well as from Republicans in Congress, pointed to recurring allegations of financial mismanagement against the FSA, going back to at least 2011, as well as to online security lapses.
Runcie was scheduled to testify before the House oversight committee Thursday.
"He chose to resign rather than face Congress," Liz Hill, a spokeswoman for DeVos, told NPR.
In an email response to NPR on Thursday, Runcie denied this explanation. "I did not leave simply to avoid a hearing on improper payments," he wrote. "That is not credible." He declined further comment.
Meanwhile, Democrats in Congress called the resignation "deeply troubling" (Sen. Patty Murray of Washington) and "cause for serious alarm" (Sen. Elizabeth Warren of Massachusetts).
Runcie's departure comes as the Education Department, like other federal agencies in the Trump administration, is facing an unusual number of vacancies and a slow pace of appointments.
So, did Runcie resign out of conscience? Or because he didn't want to face the music? And what is all this likely to mean for young people seeking help paying for college or managing their debt afterwards?
Here are two possible scenarios:
Storyline No. 1: Federal Student Aid was mismanaged.
A statement on the resignation by the oversight committee chairman, Jason Chaffetz, R-Utah, said that under Runcie's leadership federal student aid systems were "less secure, performance has suffered, and improper payments have increased."
Those "improper payments" were to be the subject of Runcie's testimony Thursday. The phrase basically refers to any erroneous, and therefore wasteful, money spent by the federal government. At least as far back as 2011, the Office of Management and Budget had identified student aid programs, both Pell Grants and student loans, as being particularly prone to paying out money when they didn't have to because of poor record-keeping and other issues.
A little background is in order.
Runcie, who had led the FSA since 2011, comes from the banking world. He oversaw a big transition in student lending initiated by then-President Barack Obama: from loans originated by banks to all student loans being made directly by the Education Department. Under his tenure, the portfolio of loans held directly by the government grew almost tenfold, to more than $1 trillion.
This move saved students billions. It also took away business from banks like Citibank and Wells Fargo. And it forced the reorganization of Sallie Mae, a once enormously profitable student lender.
But, while the federal government now originates loans, the FSA continues to work with "servicers" — for-profit middlemen that deal with borrowers and collect payments. Navientspun off from Sallie Mae to become the largest of those servicers.
And here is where one set of issues have arisen with the FSA, according to other federal agencies:
- In 2014, federal prosecutors accused Navient of illegally overcharging active-duty military members for loans. Navient denied wrongdoing as part of a $60 million settlement. The FSA, under Runcie, investigated and publicly exonerated Navient, but the Education Department's own inspector general found that FSA investigation to be flawed.
- In 2015, the Government Accountability Office found that the FSA's "instructions and guidance to loan servicers are sometimes lacking, resulting in inconsistent and inefficient services to borrowers."
- This year, the Consumer Financial Protection Bureau, a federal watchdog, sued Navient, accusing it of "systematically and illegally failing borrowers at every stage of repayment." The attorneys general of Illinois and Washington State have joined the case. Navient called the suit "unfounded" and said it was politically motivated. In court filings, the company said, "There is no expectation that the servicer will act in the interest of the consumer."
In a statement provided to NPR, Navient spokeswoman Patricia Christel said,
"Since the 2014 voluntary settlement, which was grounded in conflicting federal guidance, there have been six independent reviews confirming that Navient was following federal regulations ... Navient is a leader in enrolling eligible borrowers into income-driven repayment programs and helping borrowers avoid default. Navient-serviced borrowers are 31 percent less likely to default, and 49 percent of Direct Loan balances serviced by Navient are enrolled in income-driven repayment programs—more than any comparable servicer."
Second, in his statement on Runcie's departure, Chaffetz also referred to security issues.
In March, the IRS reported a "major" breach of an online tool that was supposed to make it easier for families to apply for college financial aid by adding tax information with the click of a button. The Education Department took down that tool in the middle of application season.
Runcie testified earlier this month before the House oversight committee that the FSA was working with the IRS to enhance security through encryption.
That's the phrase used by Warren in her statement.
It's been reportedthat, in his resignation memo, Runcie referred to plans underway to shift responsibility for federal student loans to the Treasury Department, and that he complained"about significant constraints being placed on our ability to allocate and prioritize resources, make decisions and deliver on the organization's mission.
According to this narrative, the idea that Runcie left because of the FSA's myopic oversight of companies like Navient doesn't square with DeVos' own actions.
DeVos wrote to Runcie in April withdrawing three memos issued under Obama, all regarding the oversight of loan servicers to protect borrowers. This move was seen as improving Navient's chances to become the sole student loan servicer when the current contract is up in 2019 — a massive federal contract.
Plus, Navient announced last month the purchase of $6.9 billion more in student debt from JPMorgan Chase & Co. Some public officials, including the state attorneys general in Washington and Illinois, urged DeVos to block that acquisition because of Navient's legal troubles.
Some are calling for an investigation to find out more. "Congress needs to get to the bottom of what's going on here," Warren said in her statement.
==
7/16
public citizen is suing Betsy DeVos.
:{Before she was installed as Secretary of Education, the extreme right-wing magnate had a financial interest in hedge funds invested in for-profit colleges and a corporation that went after student loans in default.
Now DeVos is blocking implementation of the “Borrower Defense Rule” — a rule to protect students defrauded by predatory for-profit colleges.}:
Along with a Harvard Law School program, we represent two victims of predatory student loans, Meaghan Bauer and Stephano Del Rose.
The two former students of the New England Institute of Art allege that the for-profit institute deceived them and left them with a useless education, few job prospects and tens of thousands in debt.
They would like to sue the school. But the school is trying to keep them out of court, and force them into a corporate-friendly arbitration system where their rights will be restricted.
The Borrower Defense Rule exists to ensure defrauded students like Bauer and Del Rose can have their day in court, and as a class action — with others alleging they were similarly scammed — if they choose.
But the students can’t invoke the protections of the rule while DeVos delays it.
So, we’re suing DeVos to force the rule to take effect.
The rule also authorizes the Department to cancel student loans for schools that lure students through trickery and deception.
Trickery and deception are the stock-in-trade for the for-profit school industry.
But the students can’t effectively assert their right to have the loans cancelled while DeVos delays the rule.
Our case charges that DeVos’ delay has no basis in law and that she failed to follow the proper procedures to change a rule.
==
—
CONSUMER AND LABOR GROUPS BLAST DEVOS’ DECISION TO SCRAP OBAMA-ERA OVERHAUL OF STUDENT LOAN SERVICING.On Tuesday, DeVos halted Obama-era plans to overhaul how millions of student borrowers pay back their federal loans including new consumer protections for borrowers and contract provisions aimed at boosting the quality of federal loan servicing. Sen. Elizabeth Warren (D-Mass.), called the change a “gut punch” to the nation’s student loan borrowers because the policies would have made it harder for companies to cheat borrowers. Persis Yu, director of National Consumer Law Center’s Student Loan Borrower Assistance Project, said DeVos is walking away from “common-sense protections.”
— Randi Weingarten, president of the American Federation of Teachers called the move “just another clear example of Betsy DeVos and the Trump administration putting the interests of predatory profiteers over the needs of the little guy — in this instance, the millions of people trying to go to college or acquire career skills without being crippled by debt.”
— In a memo, DeVos wrote that it was necessary to scrap the plans because of “a myriad of moving deadlines, changing requirements and a lack of consistent objectives” and a need to move forward “with precision, timeliness and transparency.” The Obama administration’s plan had called for a streamlined loan servicing platform in which borrowers make payments through a single web portal, rather than going through individual loan companies. The first phase of that project was initially slated to be finished by the end of 2016 but was delayed until this past February.
— “This increases the stakes for the CFPB to write clear rules to solve the problems in the loan servicing market,” said Rohit Chopra, the bureau’s former student loan ombudsman, who criticized the decision. “If the Education Department won’t use its buyer power to clean up bad practices, law enforcement has to step in.”
— The Education Department did not consult with the Consumer Financial Protection Bureau, which helped craft the policy guidance, before withdrawing it, according to a CFPB spokesman.“Borrowers deserve to be treated fairly and should be able to repay their debt without having to deal with illegal loan servicing practices,” the spokesman told Morning Education. “The CFPB will continue to find ways, working with all of our partners, to support and protect the 44 million Americans with student debt.” Michael Stratford hasmore.
==
AZ makes all students elegible, no dems; same day NY sez free college for under 100K$
==
People worried about college affordability today can at least take this to heart: it could get much, much worse.
Tuition has been rising by about 6% annually, according to investment management company Vanguard. At this rate, when babies born today are turning 18, a year of higher education at a private school — including tuition, fees, and room and board — will cost more than $120,000, Vanguard said. Public colleges could average out to $54,000 a year.
That means without financial aid, the sticker price of a four-year college degree for children born today could reach half a million dollars at private schools, and a quarter million at public ones. That’s for a family with one kid; those with more could be facing a bill that reaches seven figures.
How much will a year of college cost in the future?
How much will a year of college cost in the future?
Vanguard / Via investor.vanguard.com
How much families realistically need save for their children to go to college is a very real question for new parents.
“When you look at these numbers and how college has increased from an inflation standpoint historically, it is staggering,” said Maria Bruno, a senior investment strategist at Vanguard.
Many factors have been blamed over the years — a decline in state funding for public schools, along with administrative bloat, rising salaries and new construction at private colleges.
Incomes, meanwhile, have not kept up. In 2015 the median income for families with children rose by 4.3%, and in 2014 by 3%. If family income continues to grow at 4.3% each year, it will reach about $142,000 in 18 years.
Bruno estimates to save enough to cover 50% of tuition, families will need to put away (and invest) about $1,000 each month for the next 17 years if their child wants to attend a private school, $320 per month for a public school, and $147 per month for community college.
It’s a serious burden for new parents, plenty of whom still have their own college debt to pay off, and who are also advised to put aside 10% to 15% of their income for retirement. Bruno said retirement should take priority over college funds, “because there’s the possibility that other resources may be available” to help pay for education.
“With limited resources and multiple goals, it can be very overwhelming,” she said.
The silver lining, according to Jennifer Ma, senior policy research scientist at the College Board, is about 70% of students get some grant or scholarship money and pay less than the so-called “sticker price.” And while $121,000-per-year private college may seem like an option for only the wealthy, she added that private schools account for roughly 30% of undergrads anyhow; the majority go to public colleges.
Yet this free scholarship money is not enough, even at public schools. About 60% of undergrads borrow money. Of those at public colleges who took out loans, the average debt is $26,800, said Ma. At nonprofit private colleges, the average is $31,400.
Ma even had a note of relative optimism for new parents. In recent years college costs have increased at a slower rate than the 6% in Vanguard’s model — something closer to 4%. “These days, colleges and universities have an enormous amount of pressure to minimize costs and control tuition increases, more so than in the past than 20 to 30 years,” she said.
A couple of percentage points really add up. At a growth rate of 4%, four years of college will cost about $185,000 at a public school, and $363,000 at a private college, according to the College Board’s college cost calculator.
https://www.buzzfeed.com/venessawong/in-18-years-a-college-degree-could-cost-about-500000
==
https://www.propublica.org/article/colleges-flush-with-cash-saddle-poorest-students-with-debt
...NYU is not the only university with a billion-dollar endowment to leave its poorest students with heavy debt loads. More than a quarter of the nation’s 60 wealthiest universities leave their low-income students owing an average of more than $20,000 in federal loans.
At the University of Southern California, which has a $4.6 billion endowment, low-income students graduate with slightly more debt than NYU’s graduates: $23,375. At Boston University ($1.5 billion endowment), it’s $27,000, and at Wake Forest University ($1.1 billion endowment) low-income students graduate with $29,150 in debt.
This new data on student debt is drawn from numbers that the Obama administration assembled as part of a planned effort to create grades for every college. In the face of fierce lobbying from universities, the administration backed away, but has made much of the data public on a new website called College Scorecard. ProPublica has used that material to create Debt By Degrees, an interactive database that allows you to search information for almost 7,000 schools. The data provides an unprecedented level of detail on the financial burden that the poorest college students face, showing for the first time how much federal debt poor students take on compared to their wealthier peers, and how well these students are able to repay their loans. The database also shows how much graduates earn on average after leaving school.
The implications of these numbers can be far-reaching. Studies have shown that even small debts can increase a student’s chances of dropping out, particularly for minorities and low-income students. Also, federal loans, which are typically capped at $27,000 over four years, often don’t cover the full expense of college. Many students also take on private bank loans or work jobs outside school.
...
==
https://projects.propublica.org/graphics/ncaa-bracket-2017
We used federal data to create an NCAA Tournament bracket based on five factors that measure each school’s ability to graduate low-income students with little debt: the percentage of undergraduates from low-income households, the average financial support given to those students, the tuition discount that those students receive, their post-graduation debt, and the percentage of those students who are unable to pay back their loans after graduation.
Click any game in the bracket below to view more information on how both schools fare in each Debt by Degrees head-to-head matchup. You can also compare any two schools by clicking here.
See Top Colleges
Use the menus below to change the school categories.
Private for-profit, 2-yearPrivate for-profit, 4-yearPrivate for-profit, less-than 2-yearPrivate not-for-profit, 2-yearPrivate not-for-profit, 4-yearPrivate not-for-profit, less-than 2-yearPublic, 2-yearPublic, 4-yearPublic, less-than 2-year UnclassifiedResearch UniversitiesPredominately Associate's Degrees CollegesPredominately Bachelor's Degrees CollegesReligious SchoolsMedical & Nursing SchoolsTech & Engineering SchoolsBusiness SchoolsArt SchoolsLaw SchoolsMaster's CollegesTribal Colleges
Percentage of Students Who Received Pell Grants »
Highest
| 1. | 71.9% | Clark Atlanta University |
|---|---|---|
| 2. | 58.6% | Union Institute & University |
| 3. | 50.7% | California Institute of Integral Studies |
| 4. | 50.6% | American International College |
| 5. | 50.5% | National Louis University |
| 6. | 50.5% | Barry University |
| 7. | 49.8% | Liberty University |
| 8. | 49.0% | Regent University |
| 9. | 48.9% | Trinity International University-Illinois |
| 10. | 48.3% | Howard University |
Lowest
| 115. | 6.7% | Washington University in St Louis |
|---|---|---|
| 114. | 10.8% | Wake Forest University |
| 113. | 11.2% | University of Notre Dame |
| 112. | 11.3% | California Institute of Technology |
| 111. | 11.4% | Tufts University |
| 110. | 11.5% | Villanova University |
| 109. | 11.6% | University of Dayton |
| 108. | 11.9% | Yale University |
| 107. | 12.3% | Alliant International University-San Diego |
| 106. | 12.5% | University of Chicago |
Avg. Cost for Low-Income Students »
Lowest
| 1. | $2,473 | Harvard University |
|---|---|---|
| 2. | $2,841 | Stanford University |
| 3. | $3,186 | Brown University |
| 4. | $3,630 | Princeton University |
| 5. | $3,918 | Yale University |
| 6. | $5,128 | Massachusetts Institute of Technology |
| 7. | $6,468 | Rice University |
| 8. | $6,696 | California Institute of Technology |
| 9. | $6,905 | Vanderbilt University |
| 10. | $7,529 | Dartmouth College |
Highest
| 114. | $30,500 | Clark Atlanta University |
|---|---|---|
| 113. | $29,820 | Catholic University of America |
| 112. | $29,089 | Tulane University of Louisiana |
| 111. | $29,010 | The New School |
| 110. | $28,524 | American University |
| 109. | $26,809 | Hofstra University |
| 108. | $26,745 | University of Dayton |
| 107. | $26,742 | Immaculata University |
| 106. | $26,717 | Azusa Pacific University |
| 105. | $26,588 | Drexel University |
Avg. Discount for Low-Income Students »
Highest
| 1. | 96% | Harvard University |
|---|---|---|
| 2. | 95% | Stanford University |
| 3. | 95% | Brown University |
| 4. | 94% | Princeton University |
| 5. | 94% | Yale University |
| 6. | 91% | Massachusetts Institute of Technology |
| 7. | 89% | Vanderbilt University |
| 8. | 89% | California Institute of Technology |
| 9. | 88% | Dartmouth College |
| 10. | 88% | Rice University |
Lowest
| 114. | 10% | Union Institute & University |
|---|---|---|
| 113. | 14% | Clark Atlanta University |
| 112. | 16% | Wilmington University |
| 111. | 27% | Liberty University |
| 110. | 34% | National Louis University |
| 109. | 34% | Lindenwood University |
| 108. | 40% | Dallas Baptist University |
| 107. | 41% | Azusa Pacific University |
| 106. | 43% | Immaculata University |
| 105. | 44% | Maryville University of Saint Louis |
Median Federal Debt of Pell Grantees »
Lowest
| 1. | $3,013 | Princeton University |
|---|---|---|
| 2. | $6,250 | California Institute of Technology |
| 3. | $6,856 | Dartmouth College |
| 4. | $7,903 | Stanford University |
| 5. | $8,100 | Rice University |
| 6. | $8,336 | Duke University |
| 7. | $8,750 | Florida Institute of Technology |
| 8. | $8,816 | University of the Cumberlands |
| 9. | $8,945 | Vanderbilt University |
| 10. | $9,982 | Brigham Young University-Provo |
Highest
| 115. | $30,500 | Rensselaer Polytechnic Institute |
|---|---|---|
| 114. | $29,000 | Syracuse University |
| 113. | $28,901 | Wake Forest University |
| 112. | $28,543 | Stevens Institute of Technology |
| 111. | $28,500 | Marquette University |
| 110. | $28,250 | Worcester Polytechnic Institute |
| 109. | $28,000 | Duquesne University |
| 108. | $27,500 | George Washington University |
| 107. | $27,038 | Brandeis University |
| 103. | $27,000 | Boston University |
Source: U.S. Department of Education College Scorecard Data; NACUBO Endowment Study 2014; Pell graduation rate data from The Education Trust
==
tuition up 80? 2000, income flat
https://projects.propublica.org/graphics/publictuition
==
http://bigthink.com/videos/daniel-altman-sell-your-future-to-avoid-student-loans-2
Economist Daniel Altman acknowledges that the student loan industry in the United States is a disaster. The obvious solution of government intervention by way of forgiveness could make things even thornier. Rather, Altman imagines a scenario where students could sell shares of their future income to fund their education.
Show Transcript
DANIEL ALTMAN
Daniel Altman is Big Think's Chief Economist and an adjunct faculty member at New York University's Stern School of Business. Daniel wrote economic commentary for The Economist, The New York Times, and The International Herald Tribune before founding North Yard Economics, a non-profit consulting firm serving developing countries, in 2008. In between, he served as an economic advisor in the British government and wrote four books, most recently Outrageous Fortunes: The Twelve Surprising Trends That Will Reshape the Global Economy.
binders full of students/bundle
==
eclipses credit card loans
1.3 trillion? can be 100K; tuition up 500% since 80's kpfa 1/22/14 8 am strike debt, union; citibank, fannie?
https://www.propublica.org/article/new-jersey-senate-examines-controversial-student-loan-agency
This story was co-published with The New York Times.
Almost a dozen people with harrowing experiences with New Jersey’s controversial student loan program testified on Monday before state lawmakers, detailing its aggressive collection tactics and onerous terms that some said had ruined them financially.
“Hesaa destroyed my family,” Tracey Timony, referring to the state’s Higher Education Student Assistance Authority, said at a hearing before the Higher Education and Legislative Oversight Committees of the New Jersey State Senate.
Ms. Timony had co-signed on her daughter’s loans totaling $140,000. After her daughter defaulted, Ms. Timony was sued by one of the agency’s collection firms and has since declared bankruptcy to get more manageable monthly payments.
The hearing was prompted by an investigation published last month by ProPublica and The New York Times into the agency, which runs the largest state-based student loan program in the country, with nearly $2 billion in outstanding loans.
The agency charges higher interest rates than similar federal programs, the investigation found, and has strikingly broad collection powers. If borrowers fall behind on payments, the agency can garnish wages, seize tax refunds and revoke professional licenses, all without getting a court judgment.
State legislators, who on Monday pushed forward two measures that would give a break to borrowers in the program, said they were troubled by the agency’s tactics.
“We need to end this program, start over from scratch and find ways of providing assistance for students so that they can get an education without it bankrupting them,” said Sen. Robert M. Gordon, a Democrat from northern New Jersey and the chairman of the Legislative Oversight Committee.
The agency’s executive director, Gabrielle Charette, declined to testify at the hearing. Instead, she sent a letter to legislators, explaining that because the agency is currently conducting an internal review, it would be “premature” to testify on the concerns of borrowers and legislators. Ms. Charette added that the agency would brief the State Senate in the future.
“We’re disappointed that the agency didn’t show up,” Stephen M. Sweeney, a Democrat and president of the State Senate, said before the hearing.
An executive from the agency had previously dismissed reporting from ProPublica and The Times as “one-sided,” calling the investigation a “biased op-ed.”
New Jersey’s Student Loan Program is ‘State-Sanctioned Loan-Sharking’
The loans have extraordinarily stringent rules, aggressive collections and few reprieves, even for borrowers who’ve died. The head of the loan agency was appointed by Gov. Chris Christie.Read the story.
As ProPublica and The Times have detailed, repayment of the state loans cannot be adjusted based on income, and borrowers — alongside their co-signers — are given few breaks, even when facing disability or death...
==
https://www.propublica.org/article/new-jersey-student-loan-agency-to-staff-dont-tell-borrowers-about-help-unle
6/16
http://ww2.kqed.org/forum/2016/07/12/one-in-five-uc-students-struggles-to-pay-for-food-study-finds/
==
pro publ 4/16
Federal Government Finally Forgives Billions in Debt of Students Who've Become Disabled
by Cezary Podkul and Marcelo Rochabrun | @cezary and @mrochabrun
The move comes after a ProPublica investigation that documented how the government was making it hard for disabled borrowers to get their loans forgiven.
More coverage: Education Department Bureaucracy Keeps Disabled Borrowers in Debt
?
http://www.notey.com/blogs/student-loan-debt
==
The U.S. Department of Education has blessed a deal under which a non-profit student debt collection company, Minnesota-based Education Credit Management Corporation (ECMC), will pay $24 million to acquire 56 campuses, operating under the brands Everest and WyoTech, owned by collapsing Corinthian Colleges, one of the most abusive and deceptive for-profit college companies.The terms of this deal are extraordinarily unfavorable to students. The agreement creates a remarkable conflict of interest for the Department itself, and it sets terrible precedents for future failing colleges.
The deal is so bad that it seems that the Department is determined to prop up these Corinthian campuses at all costs. In other words, it has concluded that Corinthian Colleges is too big to fail. It is making a terrible mistake.
The Obama administration has done a great deal of hard work to try to stop the torrent of waste, fraud, and abuse engaged in by many companies in the for-profit college industry, which has been grabbing more than $30 billion a year in taxpayer money, mostly to offer career education programs in fields like medical assisting, criminal justice, and auto repair. The bad institutions in this sector offer poor to middling quality programs, charge sky-high prices, and use deceptive and high-pressure marketing to sign up as many students as possible, and deposit their federal aid checks, regardless of whether they will benefit from the program. Corinthian has been among the worst along those lines. The administration has been doing some good things to try to target federal aid away from such bad programs and toward those that actually help students build careers. But the ECMC-Corinthian decision puts that progress at risk.
It’s not too late, though, for the Department to change course.
Minutes ago, 46 civil rights, veterans, student, and consumer groups, part of a coalition in which I am a participant, sent a letter to Secretary of Education Arne Duncan, Attorney General Eric Holder, and CFPB director Richard Cordray sharply criticizing the ECMC-Corinthian deal and listing multiple specific problems with the proposed agreement. Our group, which includes the NAACP, League of United Latin American Citizens, Iraq Afghanistan Veterans of America, Student Veterans of America, AFL-CIO, Consumers Union, and many others, did so after extensive discussions between coalition representatives and Department of Education officials, as well as multiple conversations with ECMC executives, during which we expressed our strong concerns.
The deal had already been attacked by advocates for students on Capitol Hill. “I’m puzzled and upset by this outcome,” Senator Dick Durbin (D-IL) told Buzzfeed. “I can’t see how students get a break in this scenario. They’re now stuck in this debt collection university.” In the wake of the proposed sale, Durbin, Elizabeth Warren (D-MA), and eleven more Democratic senators have written to Duncan asking that his Department exercise its authority to discharge federal student loans for students with legal claims against Corinthian. Representatives Steve Cohen (D-TN), Raul Grijalva (D-AZ), and Mark Takano (D-CA-41), issued a statement noting that “ECMC has no prior experience operating institutions of higher learning, but,” as the New York Times reported earlier this year, “it does have a checkered history that includes using ruthless collection tactics against student loan debtors who should have reasonably qualified for bankruptcy relief.”
There are indeed real questions about whether ECMC has the corporate character and capacity to undertake the enormously complicated task of suddenly running one of the nation’s largest school systems. But no less concerning are (1) the nature of assets being acquired and (2) the proposed terms of the deal.
There are good programs and instructors, and many fine students, in the Corinthian chain; I have spoken with scores of well-intentioned teachers and staff in the past few years. But they have complained about a company that has sacrificed student outcomes to the company’s bottom line. Corinthian’s deceptive practices and poor record of student success has given many of its programs a weak reputation and left many of its students — people of color, single parents, veterans, and others struggling to build a future — deep in debt. That tarnished image increases the challenges for graduates in finding jobs in their chosen field. It also increases the challenges for any acquirer to recruit new students without engaging in the kind of deceptive marketing that has delivered students to Corinthian programs. It’s not at all clear that anyone, including ECMC, can turn the quality of programs around fast enough to effectively help enough of the current students, who total about 39,000, 51 percent of them studying exclusively online.
It’s thus doubtful that it makes sense to have a plan that depends on new students enrolling at these Corinthian campuses, as opposed to seeking educational opportunities elsewhere. Why would the Department of Education force taxpayers to invest in a risky scheme to prop up these campuses for perhaps decades to come, mostly just to avoid having to redirect the current students to new educational opportunities, especially at a time when various sectors of higher education have excess capacity?
Closing Corinthian programs and campuses will likely occur in California, where Attorney General Kamala Harris refused to agree, as other regulators have now agreed, to shield ECMC from financial claims for past harm to Corinthian students. Thus ECMC declined to buy those campuses, which operate as Everest schools and also under the brand Heald College (a once higher-quality, independent institution that Corinthian bought and promptly ruined, as Heald’s former president recently charged). Shuttering of campuses would create hardships for those students who like their current Corinthian programs, however overpriced they are. It also, of course, would cost many Corinthian employees their jobs. But Attorney General Harris is right to stand up; current and future students, and the country’s long-term interest, is best served without the current anti-student Corinthian-ECMC deal.
Many of the current Corinthian students were defrauded, and they deserve the option of getting their money refunded, or attending another school.
If the Department is reluctant to spend federal dollars on forgiving the Corinthian students’ loans, and if Corinthian’s collapse was hastened when the Department froze federal aid and the company claimed it was almost out of cash, it’s fair to ask where all the federal tax dollars sent to Corinthian are now. Santa Ana, California-based Corinthian, at its peak, was hauling in more than $1 billion a year in federal student grants and loans.
Corinthian CEO Jack Massimino took home more than $3 million a year. He recently put on the market, listed at $11.5 million, his 10,000-square-foot, mountain-view second home in Park City, Utah; the listing says it is “Simply THE finest home in Kamas Valley and possibly the Intermountain West,” and it offers a heated horse barn, a “Children’s ‘Art Barn,’” and a pond on 61 acres.
The complaint against Corinthian filed by California AG Harris, one of many state and federal law enforcement actions taken against the company, alleges that Massimino and other “senior [Corinthian] executives” had “firsthand knowledge of the misconduct,” i.e., the deceptions at the center of Harris’s lawsuit.
Our coalition letter, the text of which is below, lists many of the glaring problems with the ECMC-Corinthian deal, but I will highlight two particularly bad ones:
First, ECMC has insisted on — and the Department of Education has not rejected — requiring students when they enroll to waive any right to pursue disputes in court; instead they must resolve matters through private arbitration. Such mandatory arbitration agreements, which strongly favor companies over individuals, are common when it comes to anti-consumer business like the credit card industry and — of course — the for-profit college industry. The Department could, and should, demand that all recipients of federal student aid, including for-profit colleges, allow students who have been lied to, assaulted, or otherwise harmed by the institution, the option of a day in court. Instead, with this agreement, the Department appears to be moving in the opposite direction, acquiescing in ECMC forcing harmed students into arbitration, even though it plans to run its school system as a non-profit; few, if any, non-profit colleges currently use mandatory arbitration clauses. Denying students such basic legal rights shields a college from accountability for treating its students fairly. ECMC executives’ insistence on arbitration may be revealing of how they really would operate the schools, however well-intentioned and public-spirited they believe they are now. And the Department of Education’s apparent acceptance of that position is another sign of its desperation to have someone take over these campuses before they fold — regardless of the harms and dangerous precedents.
Second, the agreement builds in an extraordinary conflict of interest for the Department of Education. ECMC has insisted it won’t pay more than $24 million up front. So in order to recoup some of the taxpayer investment, the agreement includes an “Earn Out” provision providing that ECMC’s new college subsidiary, Zenith, will pay the Department “up to $17.25 million ... over a seven-year period” based on a still-unspecified “percentage of funds that exceed targets specified by the Department.” In other words, the agreement would essentially give the Department an equity position, dependent on ECMC making a good deal of money. What’s the problem with that? The Department is charged with overseeing ECMC’s conduct — that it is not engaged in predatory marketing, or leaving too many students defaulting on their loans, or lying to the Department itself. How can an oversight body have a financial stake in a company it is charged with regulating? It’s a blatant and unacceptable conflict. It could easily be avoided by ECMC, whose coffers are full of cash, ponying up a bit more money now. But the Department isn’t insisting on that, again suggesting its desperation to prevent these Corinthian campuses from failing.
Right now, at least two other huge for-profit college companies — ITT Tech and Education Management Corporation (EDMC, no relation to ECMC) — may be at serious risk of collapse, with declining enrollments, depleted share prices, and a pile of federal and state law enforcement investigations and lawsuits. Other big industry players are also in trouble. Treating Corinthian as too big to fail, and thus sacrificing students and common sense, simply to find a buyer, any buyer, is a terrible course and a terrible precedent. The time to stop this bad decision is right now.
Here’s the text of our coalition letter:
==
Each year, the collective student loan debt skyrockets as tuitions continue to rise and graduates compete for scarce jobs with stagnant wages. From 2011 to 2013, the amount of debt held by recent graduates increased a whopping 20%, reaching a total more than $1.2 trillion.
As students struggle to pay off their loans, big banks and financial institutions are spending millions to influence elections and prevent policy solutions that might hinder their profits.Every year, Wall Street companies rake in almost $45 billion in revenue from higher education, largely derived from student loans.
Last year, the student loan industry spent $4.5 million on lobbying efforts, followed by $1 million in political contributions. Sallie Mae, a publicly traded company and the nation’s biggest student loan lender, has spent about $3 million every year since 2007 to lobby against bills that would aid college graduates.
While young Americans and their families are desperate for a lifeline, Congress continues to push their own agenda and that of their donors ahead of voters.
Lawmakers who side with Sallie Mae on key issues have collected more money on average than those who have not. With the right sized check, Sallie Mae is able to make and keep friends in Congress while securing policies that increase profits.
When it comes to Sallie Mae’s bottom line, there’s no politician or policy that costs too much. And sadly, American students and their families are paying the price.
==
http://www.propublica.org/article/colleges-flush-with-cash-saddle-poorest-students-with-debt
NYU
... ProPublica analysis based on new data from the U.S. Department of Education shows that students from low-income families graduate from NYU saddled with huge federal loans. The school’s Pell Grant recipients – students from families that make less than $30,000 a year – owe an average of $23,250 in federal loans after graduation.
That’s more federal loan debt than low-income students take on at for-profit giant University of Phoenix, though NYU graduates have higher earnings and default less on their debt.
NYU is not the only university with a billion-dollar endowment to leave its poorest students with heavy debt loads. More than a quarter of the nation’s 60 wealthiest universities leave their low-income students owing an average of more than $20,000 in federal loans.
At the University of Southern California, which has a $4.6 billion endowment, low-income students graduate with slightly more debt than NYU’s graduates: $23,375. At Boston University ($1.5 billion endowment), it’s $27,000, and at Wake Forest University ($1.1 billion endowment) low-income students graduate with $29,150 in debt.
This new data on student debt is drawn from numbers that the Obama administration assembled as part of a planned effort to create grades for every college. In the face offierce lobbying from universities, the administration backed away, but has made much of the data public on a new website called College Scorecard. ProPublica has used that material to create Debt By Degrees, an interactive database that allows you to search information for almost 7,000 schools. The data provides an unprecedented level of detail on the financial burden that the poorest college students face, showing for the first time how much federal debt poor students take on compared to their wealthier peers, and how well these students are able to repay their loans. The database also shows how much graduates earn on average after leaving school.
The implications of these numbers can be far-reaching. Studies have shown that even small debts can increase a student’s chances of dropping out, particularly for minorities and low-income students. Also, federal loans, which are typically capped at $27,000 over four years, often don’t cover the full expense of college. Many students also take on private bank loans or work jobs outside school.
“Student debt is not the same to every borrower,” said Mark Huelsman, a senior analyst at Demos, a public policy nonprofit. “It can look a lot different to a first generation student from a very modest economic background than to someone going to graduate school getting a law degree.”
Indeed, undergraduates take a fraction of the loans of graduate students but default at much higher rates. Debt can put low-income young adults at a disadvantage for years to come, limiting a graduate’s ability to save, get a mortgage, or get the job they aspire to.
“At the end of the day, you’re talking about households that don’t have nearly as much wealth to fall back on,” said Huelsman.
Rebecca Arthur wanted nothing more than to study photography at Tisch, NYU’s arts school. Her mother, however, made less than $25,000 a year working at a nursing home, so Arthur knew the school’s four-year price tag of over $250,000 would be a stretch. When Arthur was accepted, she was shocked – not only because she had gotten into her dream school, but also because the school only offered modest financial aid.
“The first bill was $32,000 and it was more than my mom made in a year,” she said. “Why would they accept me if they knew I couldn’t afford it?”
Arthur tried to crowdfund the remaining amount of her tuition, but it was only when her mother died a month before school started that NYU agreed to take a second look at her financial aid package. Although they increased her aid, she works four jobs and expects to graduate with over $24,000 in loans.
“The one downside to NYU is that money is always a big problem,” said Arthur, who is now a sophomore at the university. “People that really want [to go to NYU] and deserve it shouldn’t have to fight for it.”....
==
http://thinkprogress.org/politics/2015/07/07/3677543/marco-rubios-economic-plan-calls-students-sell-private-investors/
Florida Senator and Republican presidential candidate Marco Rubio described his economic platform in a speech Tuesday in Chicago, touching on well-worn GOP priorities including slashing corporate taxes from 35 to 25 percent, further deregulating the private sector, restricting family immigration, and resisting calls to raise the minimum wage. Taking several specific shots at Democratic frontrunner Hillary Clinton, Rubio said his plan would avoid “pumping more of today’s money into yesterday’s programs,” and bring the U.S. into the future.
In the speech, Rubio also called for a “revolutionized” higher education system. If elected president, he promised to “bust…the cartel of existing colleges and universities” by loosening the rules for accreditation so that “innovative, low-cost competitors” can court students.But critics say the government accreditation process is already far too loose, allowing predatory for-profit chains like Corinthian Colleges to win federal approval and funding even as they mislead students into paying for essentially worthless degrees.
He also touted the “Student Right to Know Before You Go Act” he co-sponsored with Oregon Democrat Ron Wyden — a plan extremely similar to one President Obama pushed for last year that ranks colleges by how much their tuition costs and how much money their graduates make.
Lamenting the “shadow of debt hovering over millions of graduates,” Rubio then proposed a model already suggested by his rival Governor Chris Christie (R-NJ): allowing rich individuals or hedge funds to pay a students tuition and collect their investment back post-graduation.
“It may result in a profit for the investor or it may not – but unlike with loans, none of the risk lies with the student,” Rubio said.
He expanded on this idea in a speech last year:
Let’s say you are a student who needs $10,000 to pay for your last year of school. Instead of taking this money out in the form of a loan, you could apply for a “Student Investment Plan” from an approved and certified private investment group. In short, theseinvestors would pay your $10,000 tuition in return for a percentage of your income for a set period of time after graduation – let’s say, for example, 4% a year for 10 years.
This group would look at factors such as your major, the institution you’re attending, your record in school – and use this to make a determination about the likelihood of you finding a good job and paying them back.
Unlike with loans, you would be under no legal obligation to pay back that entire $10,000. Your only obligation would be to pay that 4% of your income per year for 10 years, regardless of whether that ends up amounting to more or less than $10,000.
But these “Student Investment Plans,” which also have the Orwellian name “human capital contracts,” raise many serious concerns. For one, investors may refuse to cover entire fields of students not likely to bring in the big bucks after graduation, or would charge them a staggeringly high percentage of their income. For those backing this plan, such as the conservative think tank American Enterprise Institute (AEI), this poses no problem.
“Isn’t this ‘unfair’ to those wanting to be librarians, teachers, social workers, etc., since they would have to forego more of their incomes to satisfy the human capital contract? Not really,” writes AEI Adjunct Scholar Richard Vedder. “Society puts a relatively low value on those jobs.”
Additionally, following Rubio’s math of 4 percent over 10 years, a graduate would have to earn an extremely low salary for the investor not to make a profit. Vedder and other advocates of the plan are less cautious, and have voiced support for plans that take as high as 25 percent of a graduates salary for multiple decades after they enter the workforce.
The National College Access Network and other groups have warned that such a plan could cost students even more than high-interest federal loan programs, diverting away money those graduates could have used to save for retirement or buy a house.
Rubio’s proposal is similar to the “Pay It Forward, Pay It Back” model currently being explored by the state of Oregon — with one crucial difference. In Oregon’s plan, the investor is the democratically-elected state government, so when graduates repay their loans that money can go back into public education. Under Rubio’s version, the money would go into the pockets of investors.
Tags
A ‘free market’ solution to college debt?
In order to address the problem of many students graduating from college with huge debts, Bernie Sanders has proposed that all state universities provide free education as an investment in the nation’s future by enabling the creation of a more educated work force. The idea is that freed from such debt, graduates will be able to choose worthwhile careers rather than ones that pay a lot so that they can retire their debt. Sanders points out that many developed countries provide free higher education to their students. Even some developing countries do so. For example, my own university education in Sri Lanka was completely free.
Of course the idea of providing anything free, however worthwhile it may be (such as health care), is anathema to our ruling oligarchs, and free-market devotees have come up with their own capitalist solution to college debt, one that has been seized on by New Jersey governor Chris Christie as his presidential campaign flounders.
The idea is that students incorporate themselves somehow into a kind of company and sell stock in themselves to investors in return for giving them a portion of their future earnings. While on the surface this has disturbing similarities to the practice of sharecropping, with education replacing land, with all the problems that can happen in such a system, its supporters say that it is not that different from the student loan systems we currently have.
Economist Richard Vedder explains how the system would work:
Students currently do the equivalent of selling bonds – they borrow money with the promise to repay the funds. Why not issue stock (equity) in themselves – give investors partial, temporary ownership of a college graduate’s “human capital,” in return for a share of his or her earnings. Call these contracts between investors and future students “income share agreements” or “human capital contracts.”
…
There are lots of advantages to having voluntary arrangements made between individual students and financial service companies financing human capital construction. A contract might go like this: “if you pay one-half of my tuition to go four years to XYZ University, I will give you 15 percent of my earnings beyond $15,000 a year for the next 18 years.” Sometimes the investor will hit a jackpot: the college student becomes highly successful, making a big six digit income. In other instances, the student either flounders in college or secures a low paying job after graduation and, on net, the investor loses. The trick is to have a pool of contracts that collectively provide a good return. The risk, however, passes from a young student with no experience in financial markets to a savvy investor.
One problem with this system can be seen immediately. Investors are more likely to back students who go into areas that promise high earnings (like investment banking, medicine, engineering) and avoid careers that serve the needs of people (like teaching and social work and other forms of public service oriented jobs). But Vedder see no problem with this. In his eyes, the reason some jobs pay poorly is because those jobs have no value in the eyes of society.
Isn’t this “unfair” to those wanting to be librarians, teachers, social workers, etc., since they would have to forego more of their incomes to satisfy the human capital contract? Not really. Society puts a relatively low value on those jobs.If a market-based financing system is in place and, say, fewer kids want to be teachers, in time salaries of teachers would rise to eliminate potential shortages. If lots of kids flee to high paying STEM [Science, Technology, Engineering, Mathematics] disciplines to lower the proportion of equity that has to be paid to human capital investors, in time this will lead to some flattening of salaries in those disciplines – supply will rise to meet high demand.
But this misses the point that there already exists a scarcity of teachers as can be seen in the increasingly large class sizes they are called upon to teach and yet their salaries and benefits are being cut, not raised. This is because schools (and libraries and social service agencies) are funded by taxpayers, and states are cutting those budgets in order to give tax cuts for the wealthy.Furthermore, the number of teachers the nation requires is vastly greater than the number of investment bankers and engineers. There is no way that the salaries of all or nearly all of these teachers will ever approach that of the currently high-paying occupations.
The logical end point of this free-market model for teachers (and one that is ardently sought by conservatives) is for publicly funded schools to disappear and be replaced by entirely private schools that would then compete for teachers and students. But that does not mean that the salaries of all teachers would rise. What would be the more likely result is a further separation of rich and poor, with a few schools catering to the elite and paying higher salaries to their teachers and attracting the children of the wealthy who will then go to elite universities and jobs in high-paying fields, while the majority of people will have to send their students to schools that pay their teachers much less because they cannot afford more. Teachers will take low-paying jobs in such schools simply because they need to earn a living.
This system already partially exists in the US where schools are largely funded by local property taxes. People who can afford to, live in school districts that have high property values that generate higher taxes that can support schools that provide excellent resources. But these are relatively few. In Vedder’s proposed system, the current inequality will likely accelerate.
==
http://www.globalpossibilities.org/liberate-41-million-americans-from-student-loan-debt/
==
I know a high school senior who’s so worried about whether she’ll be accepted at the college of her choice she can’t sleep.
The parent of another senior tells me he stands at the mailbox for an hour every day waiting for a hoped-for acceptance letter to arrive.
Parents are also uptight. I’ve heard of some who have stopped socializing with other parents of children competing for admission to the same university.
Competition for places in top-brand colleges is absurdly intense. With inequality at record levels and almost all the economic gains going to the top, there’s more pressure than ever to get the golden ring.
A degree from a prestigious university can open doors to elite business schools and law schools – and to jobs paying hundreds of thousands, if not millions, a year.
So parents who can afford it are paying grotesque sums [2] to give their kids an edge.
They “enhance [3]” their kids' resumes with such things as bassoon lessons, trips to wildlife preserves in Botswana, internships at the Atlantic Monthly. They hire test-prep coaches. They arrange for consultants to help their children write compelling essays on college applications.
They make generous contributions to the elite colleges they once attended, to which their kids are applying – colleges that give extra points to “legacies” and even more to those from wealthy families that donate tons of money.
You might call this affirmative action for the rich.
The same intensifying competition is affecting mid-range colleges and universities that are doing everything they can to burnish their own brands – competing with other mid-range institutions to enlarge their applicant pools, attract good students, and inch upward on the U.S. News college rankings.
Every college president wants to increase the ratio of applications to admissions, thereby becoming more elite.
Excuse me, but this is nuts.
The biggest absurdity is that a four-year college degree has become the only gateway into the American middle class.
But not every young person is suited to four years of college. They may be bright and ambitious but they won’t get much out of it. They’d rather be doing something else, like making money or painting murals.
They feel compelled to go to college because they’ve been told over and over that a college degree is necessary. Yet if they start college and then drop out, they feel like total failures. Even if they get the degree, they’re stuck with a huge bill — and may be paying down their student debt for years. And all too often the jobs they land after graduating don’t pay enough to make the degree worthwhile.
Last year, according to the Federal Reserve Bank of New York [4], 46 percent [5] of recent college graduates were in jobs that don’t even require a college degree.
The biggest frauds are for-profit colleges [6] that are raking in money even as their students drop out in droves, and whose diplomas are barely worth the ink-jets they’re printed on.
America clings to the conceit that four years of college are necessary for everyone, and looks down its nose at people who don’t have college degrees.
This has to stop. Young people need an alternative. That alternative should be a world-class system of vocational-technical education.
A four-year college degree isn’t necessary for many of tomorrow’s good jobs.
For example, the emerging economy will need platoons of technicians able to install, service, and repair all the high-tech machinery filling up hospitals, offices, and factories.
And people who can upgrade the software embedded in almost every gadget you buy.
Today it’s even hard to find a skilled plumber or electrician.
Yet the vocational and technical education now available to young Americans is typically underfunded and inadequate. And too often denigrated as being for “losers.”
These programs should be creating winners.
Germany – whose median wage (after taxes and transfers) is higher than ours – gives many of its young people world-class technical skills [7] that have made Germany a world leader in fields such as precision manufacturing.
A world-class technical education doesn’t have to mean young people’s fates are determined when they’re fourteen.
Instead, rising high-school seniors could be given the option of entering a program that extends a year or two beyond high school and ends with a diploma acknowledging their technical expertise.
Community colleges – the under-appreciated crown jewels of America’s feeble attempts at equal opportunity – could be developing these curricula. Businesses could be advising on the technical skills they’ll need, and promising jobs to young people who complete their degrees with good grades.
Government could be investing enough money to make these programs thrive. (And raising taxes on top incomes enough to temper the wild competition for admission to elite colleges that grease the way to those top incomes.)
Instead, we continue to push most of our young people through a single funnel called a four-year college education — a funnel so narrow it’s causing applicants and their parents excessive stress and worry about “getting in;” that’s too often ill suited and unnecessary, and far too expensive; and that can cause college dropouts to feel like failures for the rest of their lives.
It’s time to give up the idea that every young person has to go to college, and start offering high-school seniors an alternative route into the middle class.
Robert B. Reich has served in three national administrations, most recently as secretary of labor under President Bill Clinton. He also served on President Obama's transition advisory board. His latest book is "Aftershock: The Next Economy and America's Future." His homepage is www.robertreich.org [8].
==
http://www.alternet.org/culture/get-out-while-you-can-why-young-americans-should-consider-moving-abroad
http://www.tickld.com/x/wtf-is-wrong-is-wrong-with-americans-this-guy-nails-it
==
According to The Costs of War project at Brown University, the total costs for the second Iraq War and the ongoing one in Afghanistan is $4.4 trillion. Cost-wise, these two conflicts should be considered as one because it has long been established that the war in Iraq prolonged the one in Afghanistan by drawing away resources from it and causing it to drag on. Everyone in the country could go to college for nearly a decade free of charge with $4.4 trillion.
http://www.alternet.org/print/education/these-are-worst-colleges-america
==
9/14
Late Tuesday, Mitch McConnell and the Senate Republicans blocked a game-changing bill brought to the floor by Elizabeth Warren -- a GOP favor to the big banks that gave a cold shoulder to 40 million middle and working class students.
Sen. Warren’s "Bank on Students Act" would have allowed borrowers to refinance their student loans just like homeowners can with their mortgage, lowering their interest rate and saving money.
==
7/14
WASHINGTON-- Iraq and Afghanistan veterans have flocked to for-profit colleges, including a troubled chain that is closing or selling its campuses amid a series of federal and state investigations.
A report to be released Wednesday from the office of Sen. Tom Harkin, D-Iowa, a critic of the for-profit education industry who chairs the Senate Education Committee, finds that for-profit colleges received $1.7 billion in Post-9/11 GI Bill benefits in the 2012-2013 school term. About a quarter of benefits paid under the program went to the for-profit sector.
Among the top 10 recipient schools in terms of GI Bill funds, eight were from the for-profit sector. One of them was Corinthian Colleges, a chain based in Santa Ana, California, that recently reached an agreement with the Education Department to sell or close its more than 90 U.S. campuses. The Education Department has said it has concerns about the chain's operations that included allegations of falsifying job placement data used in marketing claims to prospective students, and allegations of altered grades and attendance.
Since the new GI Bill rolled out in 2009, Corinthian has received $186 million in the new GI Bill funds, the report said. Last week, the advocacy group Student Veterans of America placed the schools under the Corinthian umbrella - Everest College, Heald College and WyoTech schools - on its "not recommended" list.
Including Corinthian, the report finds that seven of the eight companies face investigations by states attorneys general or federal agencies for "deceptive and misleading recruiting" or other possible federal violations. Even as overall enrollment decreased at the eight schools since 2009, it says the number of veterans enrolled at these schools increased.
For-profit colleges have been popular among veterans, in part, because of offerings in skilled trades and flexibility such as online classes.The new GI Bill program provides the most generous school benefits paid to warfighters since the original bill was enacted in 1944. It can be used by a veteran or a member of the immediate family - and more than a million people have used it so far.
Michael Dakduk, the vice president for military and veterans affairs with the Association of Private Sector Colleges, said in a statement: "It is no surprise that members of the military choose our institutions because we provide them with career-focused programs, important support services and flexibility they need to complete their education."
But, the for-profit sector has among the highest student loan default rates and lowest graduation rates in higher education and has been a target of Democrats. The Obama administration has pushed "gainful employment" regulations that would penalize career-oriented programs that produce graduates without the training needed to find a job with a salary that will allow them to pay off their debt.
Harkin's report finds that the average cost for a veteran to attend a for-profit college is $7,972, compared to $3,914 for a public college - about twice the price.
The two top recipients of GI Bill money not in the for-profit sector were the public University of Maryland system and the non-profit Embry-Riddle Aeronautical University, according to the report.
Earlier this year, the Student Veterans of America issued a report that said a little more than half of the veterans who got college money under the GI Bill since 2009 eventually graduated. The rate was lower than the graduation rate for traditional students, who generally enroll out of high school, but higher than for veterans' non-traditional peers - those students who also tend to be older and have families and jobs.
It found that about three-quarters of the student veterans who graduated did so from public institutions. Another 15.5 percent attended private universities, while about 13 percent attended for-profit schools.
Another group, the Iraq and Afghanistan Veterans of America, has lobbied against what is known as the "90/10" rule that requires colleges to receive at least 10 percent of their revenue from sources other than the federal government. Students using the new GI Bill don't count toward the limit, so the veterans said they are aggressively targeted by the for-profit industry.
Last month, the nation marked the 70th anniversary of the Servicemen's Readjustment Act of 1944, more commonly known as the GI Bill.
The bill has been credited with providing millions of military veterans with college educations and creating the American middle class.
- Exclusive: Chilean Robin Hood? Artist Known as "Papas Fritas" on Burning $500M Worth of Student Debt
Salon.com / By Thomas Frank [1]
Congratulations, Class of 2014: You’re Totally Screwed
May 18, 2014 |
Welcome to the wide world, Class of 2014. You have by now noticed the tremendous consignment of debt that the authorities at your college have spent the last four years loading on your shoulders. It may interest you to know that the average student-loan borrower among you is now $33,000 in debt [2], the largest of any graduating class ever. According to a new study by the Pew Research Center [3], carrying that kind of debt will have certain predictable effects. It will impede your ability to accumulate wealth, for example. You will also borrow more for other things than people without debt, and naturally you will find your debt level growing, not shrinking, as the years pass.
As you probably know, neither your parents nor your grandparents were required to take on this kind of burden in order to go to college. Neither are the people of your own generation in France and Germany and Argentina and Mexico.
But in our country, as your commencement speaker will no doubt tell you, the universities are “excellent.” They are “world-class.” Indeed, they are all that stands between us and economic defeat by the savagely competitive peoples of Europe and Asia. So a word of thanks is in order, Class of 2014: By borrowing those colossal amounts and turning the proceeds over to the people who run our higher ed system, you have done your part to maintain American exceptionalism, to keep our competitive advantage alive.
Here’s a question I bet you won’t hear broached on the commencement stage: Why must college be so expensive? The obvious answer, which I’m sure has been suggested to you a thousand times, is because college is so good. A 2014 Cadillac costs more than did a 1980 Cadillac, adjusting for inflation, because it is a better car. And because you paid attention in economics class, you know the same thing must be true of education. When tuition goes up and up every year, far outpacing inflation, this indicates that the quality of education in this country is also, constantly, going up and up. You know that the only way education can cost more is if it is worth more.
In sum, you paid nearly sixty grand a year to attend some place with a classy WASP name and ivy growing on its fake medieval walls. You paid for the best, and now you are the best, an honorary classy WASP entitled to all the privileges of the club. That education your parents got, even if it was at the same school as yours, cost them far less and was thus not as good as yours. That’s the way progress works, right?
Actually, the opposite is closer to the truth: college costs more and more even as it gets objectively worse and worse. Yes, I know, universities today offer luxuries unimaginable in the 1960s: fine gymnasiums, gourmet dining halls, disturbing architecture. But when it comes to generating and communicating knowledge—the essential business of higher ed—they are, almost all of them, in a frantic race to the bottom.
According to the Delphi Project on the Changing Faculty [4], only about 30 percent of the teachers at American colleges these days are tenured or tenure-track, which means that fewer than a third of your profs actually enjoy the security and benefits and intellectual freedom that we associate with the academic lifestyle. In 1969, traditional professors like these made up almost 80 percent of the American faculty. Today, however, it is part-time workers without any kind of job security who are the majority of the instructors on campus, and in general these adjuncts are paid poorly and receive few benefits. That is who does the work of knowledge-transmission at the ever-so costly, ever-so excellent American university: Freelancers. Contract laborers.
The awful lives of these workers is the subject of a vast and popular literature. Read around and you will discover that these adjuncts sometimes collect food stamps and live out of cars [5], that they race from job to job [6], that they inflate grades [7] and endure whining rich kids [8] and come todespise the academics [9] they once sought to join. The most shocking tale [10]of all (so far) concerned an 83-year-old adjunct at a university in Pittsburgh who was reduced almost to the level of a homeless person before dying last year from an illness that she endured without benefit of health insurance from her employer.
What makes all these stories so irresistible, of course, is their overwhelming sense of irony. These adjuncts are people who once believed they were signing up for a life of teaching, writing and highbrow contemplation. And just look at the world of shit they got instead. Many of them have PhDs and many work hard at teaching. But it seems that all the learning in the world, all the good grades and high test scores—which they had too, remember, just like you—don’t mean a goddamned thing when people have no bargaining power.
Yes, you are a screwed generation, Class of 2014, with a helping of debt that will take you many years to digest. But consider this other generation that has also been screwed, and screwed by the very same people who secured that millstone to your neck. You borrowed and forked over enormous sums in exchange for the privilege of hearing lectures . . . lectures that were then delivered by people who earned barely enough to stay alive. It is a double disaster of the kind that only we Americans are capable of pulling off.
Actually, it’s worse than that. This is a disaster not only for individual adjuncts but for the production of knowledge itself. What do we really expect college classes to be like when they are taught by people in such dire situations? Is our new precarious professoriate able to research or write at the same pace as its predecessor? How many of them feel secure enough in their position to defy the prevailing conventions of their disciplines?
“No major new works of social theory have emerged in the United States in the last thirty years,” wrote the anthropologist David Graeber in an important 2012 essay [11]about this age of diminishing innovation. “We have been reduced to the equivalent of medieval scholastics, writing endless annotations of French theory from the seventies. . . .” I emailed Graeber and asked him to elaborate. Here’s what he said:
“If you look at the lives and personalities of almost any of the Great Thinkers currently lionized in the American academy, certainly anyone like Deleuze, or Foucault, Wittgenstein, Freud, Einstein, or even Max Weber, none of them would have lasted ten minutes in our current system. These were some seriously odd people. They probably would never have finished grad school, and if they somehow did discipline themselves to appear sufficiently “professional,” “collegial,” conformist and compliant to make it through adjunct hell or pre-tenure, it would be at the expense of leaving them incapable of producing any of the works for which they have become famous.”
It is not easy to discover how heavily any one school uses adjuncts, because the data depends on voluntary disclosures by the institutions themselves and because the number of adjuncts reported doesn’t tell us how many classes those adjuncts teach or how much time they spend on campus. Still, numbers do exist for some institutions, thanks to a survey [12]done by the Department of Education. What you’ll find: some of the most expensive universities in America are also big employers of part-time, non-tenure-track labor. Remarking on this situation, a spunky website for the college-bound asks [13], “There’s No Other Way to Put It: They Like Adjuncts. What’re You Gonna Do?”
It’s a good question. What are you gonna do? The obvious answer, for adjuncts themselves, is to organize, and they are doing it [14] all over the country. The rest of us need to ponder how to stop this insane situation from getting any worse. We might begin by understanding college less as a mystical place of romance and achievement and more as a cartel or a predator, only a couple of removes from a company like Enron or a pharmaceutical firm that charges sick people $1,000 per pill. We might ask why the numbers of university administrators have grown by some 369 percent since 1976 [15], why college presidents are sometimes paid over a million dollars a year, and why state legislatures keep cutting education budgets and passing the burden along to students and their parents.
The word we always hear in connection to university price increases is “unsustainable.” The price tag of college can’t keep going up forever. But of course it can, and the party that will “sustain” it, just as soon as you get those loans paid off, will be you.
See more stories tagged with:
millennials [17],
college [18],
CLASS OF 2014 [19],
college debt [20],
adjunct [21],
Editor's Picks [22],
tom frank [23],
thomas frank [24],
business news [25],
Life News [26]
Source URL: http://www.alternet.org/education/congratulations-class-2014-youre-totally-screwed
http://www.alternet.org/education/student-debtcropper-system-even-destitute-hounded-debt-collectors
==
Rep. Tim Bishop
Rep. Bruce Braley
Rep. Julia Brownley
Rep. Cheri Bustos
Rep. Lois Capps
Rep. Bill Enyart
Rep. Lois Frankel
Rep. Pete Gallego
Rep. Steven Horsford
Rep. Joe Kennedy III
Rep. Ann Kirkpatrick
Rep. Michelle Lujan Grisham
Rep. Jim McGovern
Rep. Gary Peters
Rep. Mark Pocan
Rep. Jan Schakowsky
Rep. Louise Slaughter
Rep. John Tierney
Rep. Paul Tonko
Alma Adams, Candidate for Congress
Aimee Belgard, Candidate for Congress
Erin Bilbray, Candidate for Congress
Joe Bock, Candidate for Congress
Jerry Cannon, Candidate for Congress
Alan Cohn, Candidate for Congress
Debbie Dingell, Candidate for Congress
Michael Eggman, Candidate for Congress
John Foust, Candidate for Congress
Gwen Graham, Candidate for Congress
Patrick Henry Hays, Candidate for Congress
Kelly Kultala, Candidate for Congress
John Lewis, Candidate for Congress
Jackie McPherson, Candidate for Congress
Jim Mowrer, Candidate for Congress
Suzanne Patrick, Candidate for Congress
George Sinner, Candidate for Congress
Michael Wager, Candidate for Congress
Margie Wakefield, Candidate for Congress
Democratic Congressional Campaign Committee
THE DEBT LOBBY: While lawmakers debate solutions to the national debt problem on Capitol Hill, many Americans are struggling with a different sort of debt. The New York Timesreports that in 2010, the national student loan burden surpassed the national credit card debt burden for the first time in history. Projections show that the student loan burden is likely to soon pass $1 trillion.
These numbers may not come as a surprise to many recent college graduates. According to finaid.org, the average cumulative loan burden for a graduating senior in 2008 was $23,186. This number only increases for graduate and pre-professional students, who often graduate from law or medical school owing more than $100,000. Often times, these students graduate from school with more than just student loans: According to a 2009 report by Sallie Mae, the average college student graduates with $4,100 in credit card debt on top of their student loan burden.
Both credit card companies and student loan providers have an active presence in Washington D.C., and despite the student loan burden outpacing the credit card burden, credit card companies spend far more money on political campaigns, the Center for Responsive Politics' research indicates. During the 2010 election cycle, student loan companies contributed $410,500 to federal candidates, while Visa,Mastercard andAmerican Express alone donated more than $1.1 million.
These numbers pale in comparison to the amount of money credit card companies spend on lobbying. In 2010, the three major credit card companies spent $12.9 million on lobbying lawmakers and federal agencies.SLM Corp, the major affiliate of student loan provider Sallie Mae, alone spent $3.7 million.
Future law school graduates can take solace in the fact that even though they may graduate with an average student loan burden of approximately $93,000 (according to the National Postsecondary Student Aid Study), they may eventually become among the top contributors to national campaigns themselves. During the 2008 election cycle, lawyers and law firms contributed a staggering $234 million dollars to federal candidates, with the vast majority of that money (76%) going to Democrats.
WAL-MART'S D.C. CLOUT:If you've noticed that your favorite brand of cereal has been absent from the shelves of your local Wal-Mart, take heart. Yesterday, the major retailer announced that it will be bringing back over 8,500 products, many of which had been pulled in recent months due to budgetary concerns. To accommodate these new items, the Los Angeles Times reports that many Wal-Mart stores will be raising their ceilings and placing items in the middles of aisles. According to Wal-Mart, customers will be able to identify the returning products by nearby "It's back!" tags
The top 100 lenders originated 98.1% of all FFELP loan volume in FY2009, up from 95.7% in FY2008 and 91.5% in FY2007. The total of FFELP loan originations for the all lenders was $72.7 billion in FY2009, up from $63.2 billion in FY2008 and $56.7 billion in FY2007.
Note that Wachovia and Wells Fargo have subsequently merged, as have PNC Bank and National City Bank.
Former top lenders (including school-as-lender schools) that experienced a decline of more than 25% in origination volume in FY2009 as compared with FY2008, possibly because of the credit crisis, include: AES/PHEAA, Arizona Higher Education Loan Authority, Arkansas Student Loan Authority, BancorpSouth, Bank of Lake Mills, Beneficial Bank, Boone County National Bank, Brazos Group, Bremer Bank, Carnegie Insurance Company, Chicago School of Professional Psychology, College Loan Corporation, College Solutions Network, Comerica Bank, Compass Bank, Connecticut Student Loan Foundation, Des Moines University, DeVry University, Dollar Bank, ED LOAN TRUST IV, Emory University, First Financial Bank, First National Bank of Omaha, Franklin Bank, HSBC Bank, ISAC/IDAPP, M&T Bank Educational Lending, National City Bank, New York Institute of Technology, Northstar, Nova Southeastern University, Palmer College of Chiropractic, Parker College of Chiropractic, Southern Methodist University, St. Louis University, Student Loan Xpress (Education Lending Group), Touro College, Trustmark National Bank, TCF Bank, University of Phoenix and Walden University. These lenders represent almost two-fifths of the top 100 lenders from FY2008.
Lenders that have gained more than $500 million in loan volume include Sallie Mae ($6.7 billion), Discover Bank ($1.5 billion), PNC Bank ($1.4 billion), Wells Fargo ($1.2 billion), Bank of America ($650 million) and Nelnet ($540 million).
| Rank | Lender | Origination Volume |
|---|---|---|
| 1. | Sallie Mae | $20.990 billion |
| 2. | Citi Student Loans | $5.870 billion |
| 3. | Wachovia Education Finance Inc. | $5.540 billion |
| 4. | Wells Fargo Education Financial Services | $5.147 billion |
| 5. | Bank of America | $4.921 billion |
| 6. | JP Morgan Chase Bank | $3.548 billion |
| 7. | Pittsburgh National Corp | $2.656 billion |
| 8. | U.S. Bank | $2.262 billion |
| 9. | Discover Bank | $1.726 billion |
| 10. | EdAmerica | $1.563 billion |
| 11. | National Education Loan Network (NELNET) | $1.557 billion |
| 12. | Citizens Bank Education Finance | $1.251 billion |
| 13. | Regions Bank | $1.147 billion |
| 14. | Fifth Third Bank | $1.128 billion |
| 15. | Access Group | $1.012 billion |
| 16. | College Foundation Inc. | $967.4 million |
| 17. | Suntrust Bank | $932.2 million |
| 18. | South Carolina Student Loan Corp | $754.4 million |
| 19. | Key Corp | $619.4 million |
| 20. | Kentucky Higher Education Student Loan Corp | $577.4 million |
| 21. | Commerce Bank | $478.0 million |
| 22. | Vermont Student Assistance Corporation (VSAC) | $342.4 million |
| 23. | Rhode Island Student Loan Authority (RISLA) | $303.0 million |
| 24. | All Student Loan Corp | $279.6 million |
| 25. | Arvest | $270.0 million |
| 26. | Union Bank \& Trust Company | $241.7 million |
| 27. | Dollar Bank | $228.7 million |
| 28. | Utah State Board of Regents | $228.1 million |
| 29. | CollegeInvest (Colorado) | $225.8 million |
| 30. | New Mexico Education Assistance Foundation (NMEAF) | $215.0 million |
| 31. | Missouri Higher Education Loan Authority (MOHELA) | $177.2 million |
| 32. | Associated Bank | $176.2 million |
| 33. | Banc First | $160.1 million |
| 34. | Bank of North Dakota | $159.3 million |
| 35. | New Hampshire Higher Education Loan Corp | $158.9 million |
| 36. | First Tennessee Bank | $137.1 million |
| 37. | Georgia Student Finance Authority | $135.4 million |
| 38. | USC Credit Union | $133.9 million |
| 39. | University of Wisconsin CU | $127.0 million |
| 40. | University Federal Credit Union | $126.9 million |
| 41. | Louisiana Public Facilities Authority | $122.1 million |
| 42. | Navy Federal Credit Union | $122.0 million |
| 43. | Marshall & Isley Bank | $115.2 million |
| 44. | Midwestern University | $113.5 million |
| 45. | First National Bank of Texas | $106.4 million |
| 46. | America First Credit Union | $99.6 million |
| 47. | Simmons First National Bank | $92.6 million |
| 48. | Compass Bank | $89.8 million |
| 49. | National Ed Financing II, LLC | $89.6 million |
| 50. | Education Services Foundation | $89.2 million |
| 51. | Stillwater National Bank | $77.3 million |
| 52. | Pennsylvania State Employees Credit Union | $75.6 million |
| 53. | Illinois Student Assistance Commission/IDAPP | $63.7 million |
| 54. | Alaska SLC (ACPE) | $62.1 million |
| 55. | Anchorbank | $59.8 million |
| 56. | Arkansas Student Loan Authority | $54.7 million |
| 57. | Mountain America Credit Union | $54.3 million |
| 58. | Wells Fargo ELT Student Funding Group | $50.9 million |
| 59. | Herring Bank | $50.7 million |
| 60. | Aggieland Credit Union | $47.2 million |
| 61. | American Savings Bank FSB | $46.1 million |
| 62. | Campus Federal Credit Union | $44.1 million |
| 63. | Wyoming Student Loan Corp | $43.4 million |
| 64. | Touro College | $40.5 million |
| 65. | First Hawaiian Bank | $39.6 million |
| 66. | First Interstate Bank of Montana | $39.1 million |
| 67. | Student Lending Works, Inc. | $38.2 million |
| 68. | Northstar Education Finance | $37.3 million |
| 69. | Independence FSB | $37.2 million |
| 70. | Montana Higher Education Student Assistance Corp (MHESAC) | $37.1 million |
| 71. | First Security Bank | $36.1 million |
| 72. | Educators Credit Union | $35.2 million |
| 73. | Utah Community Credit Union | $35.1 million |
| 74. | Emory University | $32.8 million |
| 75. | SMART Financial Credit Union | $31.6 million |
| 76. | Graduate Leverage | $30.5 million |